Section 179 and the $2,500 Rule for Equipment
Most of what you buy for freelance work costs less than $2,500, and there is a rule that lets you deduct anything under that line in the year you bought it. No spreading it across years, no extra form. Section 179 and bonus depreciation — the two elections everyone brings up — only start to matter above that line, and most freelancers never get there.
Depreciation, in plain words
Depreciation is one word for one idea. Something you buy lasts several years, so you deduct it a piece at a time instead of all at once.
A $4,000 camera body you will shoot with for five years does not come off your income in one lump. It comes off in slices.
That is the default treatment for equipment. Everything else in this article is a way around it.
The word puts people off and sends the whole question to an accountant. It should not. For most freelancers the default never comes up.
Under $2,500, it is just an expense
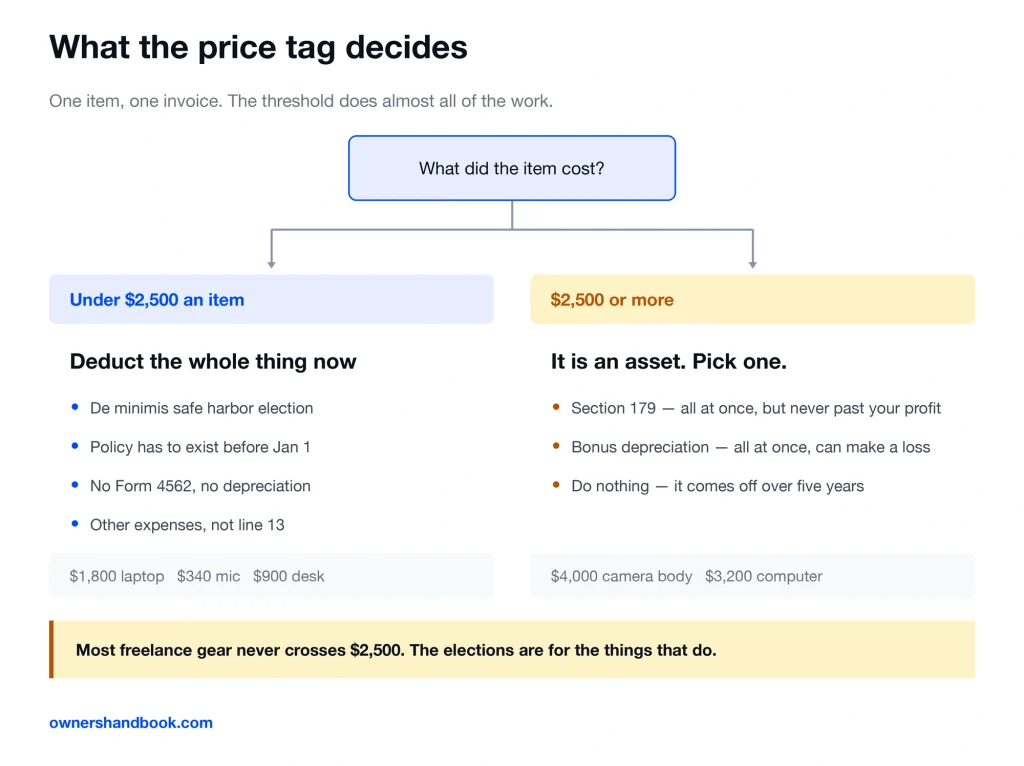
The de minimis safe harbor is a rule that lets you skip depreciation entirely for cheap things.
If you do not have an applicable financial statement — an audited statement, which almost no freelancer has — your threshold is $2,500 per invoice, or per item if the invoice lists items separately.
Under that, you deduct it now. An $1,800 laptop, a $340 microphone, a $900 desk, a $600 lens. All of it, this year.
There is one condition, and it is the one people miss. You need an accounting policy in place at the beginning of the tax year saying you expense items under your threshold.
Not written in April. In place on January 1.
The IRS does not require a taxpayer without an applicable financial statement to put that policy in writing. Write it down anyway. It is three sentences and it costs you nothing.
Then you attach a short election statement to your return. It is an annual election, so it does not carry itself forward.
These amounts do not go on line 13 with depreciation. They go in Part V of Schedule C as other expenses, which flows up to line 27a.
Above that line, three ways to go
| What the item cost | How it comes off | Form |
|---|---|---|
| $2,500 or less | All of it, this year, as an ordinary expense | None |
| Over $2,500 | Section 179, all at once, capped at your profit | Form 4562 |
| Over $2,500 | Bonus depreciation, all at once, can create a loss | Form 4562 |
| Over $2,500 | Regular depreciation, spread over the asset’s life | Form 4562 |
Once an item crosses $2,500, it is an asset, and you get to choose how fast it comes off.
Section 179 lets you elect to deduct the whole cost in the year you place the item in service.
Bonus depreciation does roughly the same thing, automatically, unless you elect out of it.
Or you do nothing and let it depreciate normally, which for a camera or a computer means five years of write-offs.
They are not interchangeable. The differences show up exactly in the years when your income was unusual.
Section 179 and bonus depreciation are not the same thing
| How they differ | Section 179 | Bonus depreciation |
|---|---|---|
| Can it push you into a loss | No. It stops at your profit. | Yes. It can take you below zero. |
| Choose item by item | Yes. Write one thing off now, spread another. | No. It applies to a whole class of assets at once. |
| The part you cannot use this year | Waits for next year | Nothing waits. There is no cap to run into. |
| Yearly dollar limit | Yes | No |
Start with the dollar caps, because for a freelancer they are not the binding part.
For tax years beginning in 2026 you can elect up to $2,560,000 under Section 179. That cap starts shrinking once you place more than $4,090,000 of equipment in service in one year.
You are not going to hit that. Nobody reading this is.
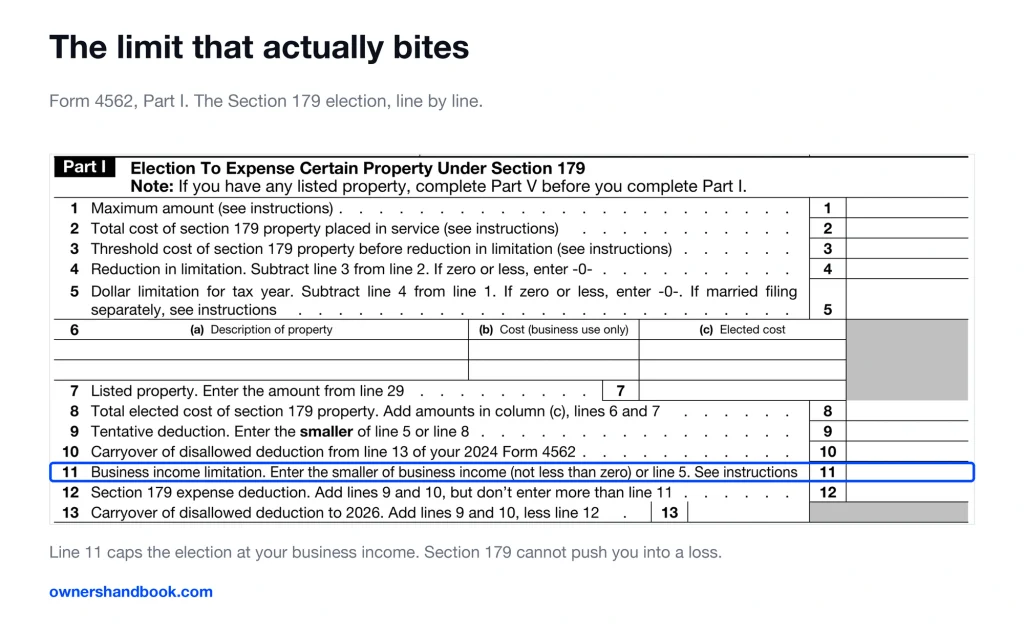
The limit that actually bites is a different one. Section 179 cannot take your business income below zero.
Say your profit before equipment is $9,000 and you bought a $12,000 setup. Section 179 gives you $9,000 this year. The other $3,000 carries forward to a year with income to absorb it.
Bonus depreciation has no such ceiling. It can push your Schedule C into a loss, and a loss can offset other income on your return, like a spouse’s wages or your own W-2 job.
Bonus is back at 100% and it is permanent now. The law restored it for qualifying property acquired after January 19, 2025.
It also applies by default. If you want less than the full amount, you have to elect out, and you elect out for a whole class of property at a time.
So the choice is real. Section 179 is item by item and you name the amount. Bonus is all or nothing across the class.
Why all at once is not always best
The instinct is to deduct everything the moment you are allowed to. Sometimes that is the wrong move.
A deduction is not worth a fixed amount. It is worth whatever tax you would have paid on that dollar.
So $4,000 written off in a $22,000 year is worth less than the same $4,000 in a $95,000 year. Same expense, different value.
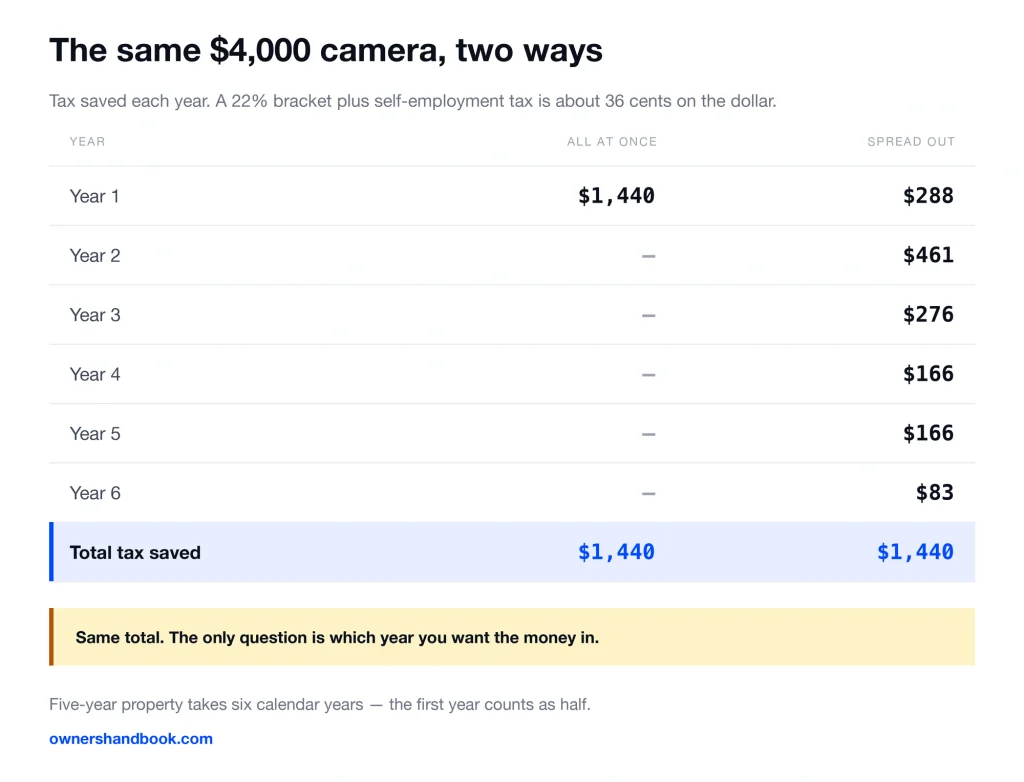
If this is your first year and you barely made money, taking the whole thing now can waste most of it. Spreading it lands deductions in years that have income to shield.
The Section 179 carryover is a middle path. Deduct what your income supports this year, carry the rest into next year.
None of this is a reason to leave money on the table in an ordinary year. In an ordinary year, take it now and move on.
Part business, part personal
If a machine is used for both work and life, you deduct the business share — and Section 179 puts a hard floor under that share.
You can elect Section 179 only on property you use more than 50% for business in the year you place it in service.
A $3,000 computer used 70% for work gives you a $2,100 Section 179 deduction. At 40% work use, you get no election at all, just ordinary depreciation on the business portion.
Then comes the part that surprises people. If business use later drops to 50% or less before the recovery period ends, you have to recapture.
Recapture means adding back the difference between what you already deducted and what ordinary depreciation would have given you. That difference goes into your income in the later year.
Cameras and video equipment are listed property, which carries stricter proof requirements. Computers are not, and have not been since 2017.
So keep a note of how the camera actually gets used. A percentage invented in April is not a record.
None of these elections change the first question. The equipment still has to be ordinary and necessary for your work before any of this applies.
Where this lands on your return
Section 179, bonus depreciation, and ordinary depreciation all run through Form 4562 and land on Schedule C line 13.
You file Form 4562 if you placed property in service this year, if you are claiming a Section 179 election, or if you have listed property at all.
De minimis items skip every bit of that. No Form 4562, no line 13, nothing to track for six years.
That is the quiet argument for staying under $2,500 where you can. It is not only a faster deduction. It is one less form and one less schedule to maintain.
One more thing worth planning around. Placed in service, not paid for, is what starts the clock. A camera bought in December and first used in January is next year’s deduction.
Frequently asked questions
Does the $2,500 limit apply per item or per purchase?
Per invoice, or per item if the invoice breaks the items out separately. One invoice for four $700 monitors qualifies item by item, not as a single $2,800 purchase.
I already owned the laptop and then started using it for work. What now?
You convert it, and your starting basis is the lower of what you paid or what it was worth the day it went into business use. Converted property generally does not qualify for a Section 179 election.
Do I have to put my $2,500 policy in writing?
Not if you have no applicable financial statement. It still has to exist before the year begins, and a dated one-page note is the easiest way to show that it did.
Can buying equipment create a tax loss?
Bonus depreciation can produce one. Section 179 cannot, because it stops at your business income, and the unused part carries forward instead.
I bought a $4,000 camera. Do I get $4,000 back?
No. You get $4,000 off your income. In a 22% bracket, with self-employment tax on top, that is roughly $1,440 back.
What happens if I sell the equipment later?
Selling it for more than its remaining basis produces taxable income. If you wrote it off in full, the basis is zero, so the whole sale price is generally income.
Sources
IRS, Tangible Property Final Regulations
https://www.irs.gov/businesses/small-businesses-self-employed/tangible-property-final-regulations
IRS, Publication 946, How To Depreciate Property
https://www.irs.gov/publications/p946
IRS, About Form 4562, Depreciation and Amortization
https://www.irs.gov/forms-pubs/about-form-4562
IRS, Instructions for Schedule C
https://www.irs.gov/instructions/i1040sc
IRS, Revenue Procedure 2025-32
https://www.irs.gov/pub/irs-drop/rp-25-32.pdf
IRS, Guidance on the Additional First Year Depreciation Deduction
IRS, Additional First Year Depreciation Deduction (Bonus) FAQ
https://www.irs.gov/newsroom/additional-first-year-depreciation-deduction-bonus-faq