Health Insurance in 2026: The Subsidy Cliff Is Back
The enhanced premium tax credits expired on December 31, 2025. For 2026 the old cutoff is back, and it is a cliff: if your household income lands above 400% of the federal poverty level — roughly $62,600 for one person, $84,600 for two, $128,600 for a family of four — the credit that lowers your marketplace premium goes to zero. Not smaller. Zero.
The line, in dollars
The cutoff is 400% of the federal poverty level, or FPL — the income floor the government publishes every January for each household size.
Your 2026 coverage is measured against the 2025 guidelines. That is not an error. The marketplace always runs a year behind, because the numbers have to exist before open enrollment opens.
| Household size | 100% of poverty, 2025 | 400%, your 2026 cutoff |
|---|---|---|
| 1 | $15,650 | $62,600 |
| 2 | $21,150 | $84,600 |
| 3 | $26,650 | $106,600 |
| 4 | $32,150 | $128,600 |
Alaska and Hawaii run on their own, higher guidelines. If you live there, look yours up rather than using this table.
The income being measured is modified adjusted gross income, or MAGI — your adjusted gross income plus a short list of add-backs like tax-exempt interest and untaxed Social Security.
For most freelancers, MAGI and AGI are the same number.
What happens at the line
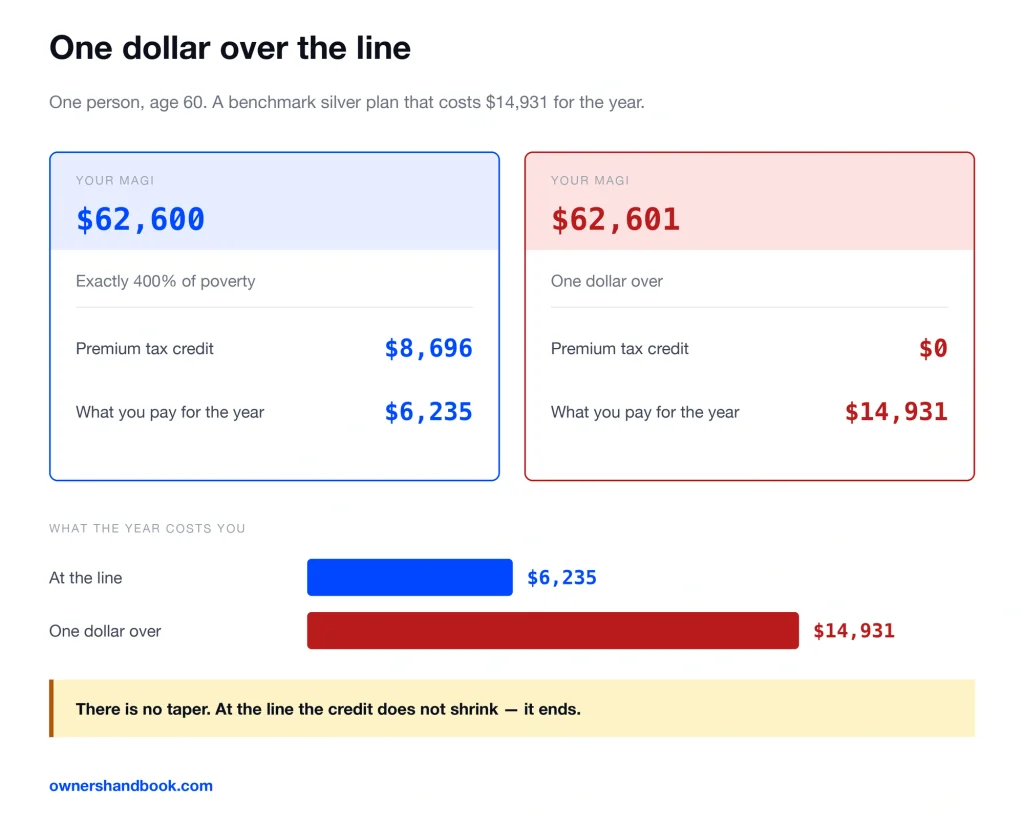
At $62,600 you qualify. At $62,601 you do not. There is no taper, no partial credit, and no rounding in your favor.
Here is the arithmetic on a real plan. Take one person, age 60, whose benchmark silver plan costs $14,931 for the year.
At exactly 400%, the law caps what you have to contribute at 9.96% of income for 2026. That is $6,235. The premium tax credit — the subsidy the government pays your insurer — covers the remaining $8,696.
One dollar more of income and that credit is $0. The same plan now costs you $14,931.
That is the whole shape of the problem. It is not that premiums rise as you earn more. It is that the credit ends all at once.
For scale: enrollees between 400% and 500% of poverty were 3% of 2025 sign-ups but 27% of the drop in enrollment going into 2026.
Your premiums come off, but not where you think
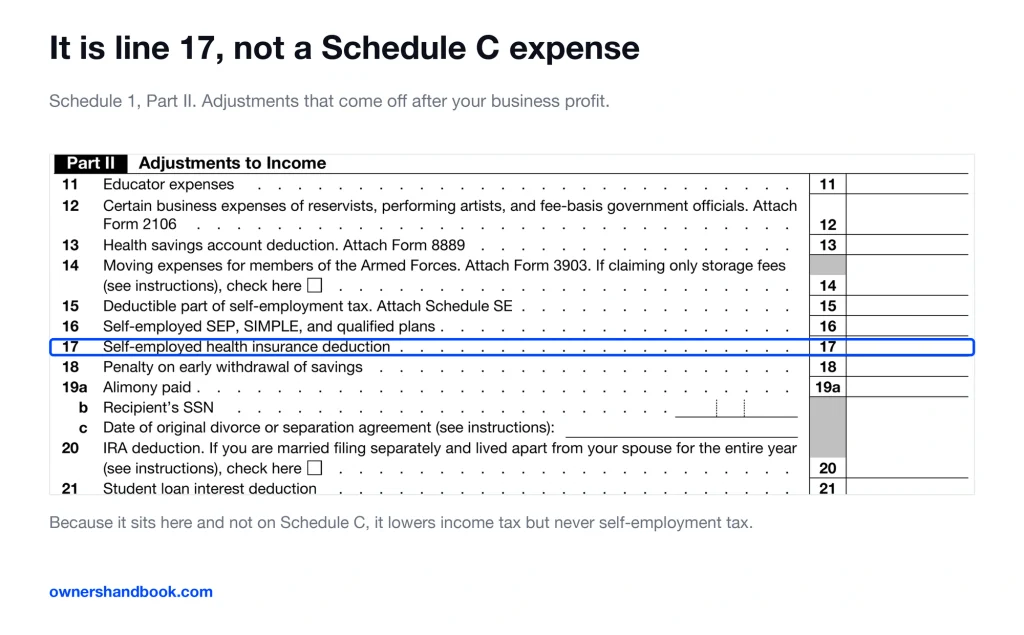
Whatever you pay for coverage is deductible. It just does not sit on Schedule C with your other business expenses.
It goes on Schedule 1, line 17, as the self-employed health insurance deduction, authorized by section 162(l) of the tax code.
That placement makes it an above-the-line deduction, meaning it comes off before your AGI is figured rather than after. Which is exactly why it matters here.
Two limits define it.
It cannot exceed your net earnings from the business the plan is tied to. If the year ended in a loss, the deduction is zero.
And it does not reduce self-employment tax. Only Schedule C expenses do that. This one lowers income tax and lowers AGI, and nothing else.
It covers medical, dental, vision, and qualified long-term care premiums — for you, your spouse, your dependents, and your children under 27.
The deduction and the credit chase each other
Look at the loop. The deduction lowers your MAGI. A lower MAGI raises your premium tax credit. A bigger credit means you paid less out of pocket, which shrinks the deduction.
Each number is an input to the other. The IRS knows, and Publication 974 gives you two ways out.
The iterative method: compute both, feed the result back in, repeat until the figures stop moving. Three or four rounds usually settles it.
The simplified method: a fixed formula that reaches an answer in one pass.
You will not run either by hand. Tax software does one of them quietly. What you need to know is that the two numbers are linked, so changing one changes the other.
Lower your MAGI before December 31
If a December project would push you across the line, the move is on the deduction side.
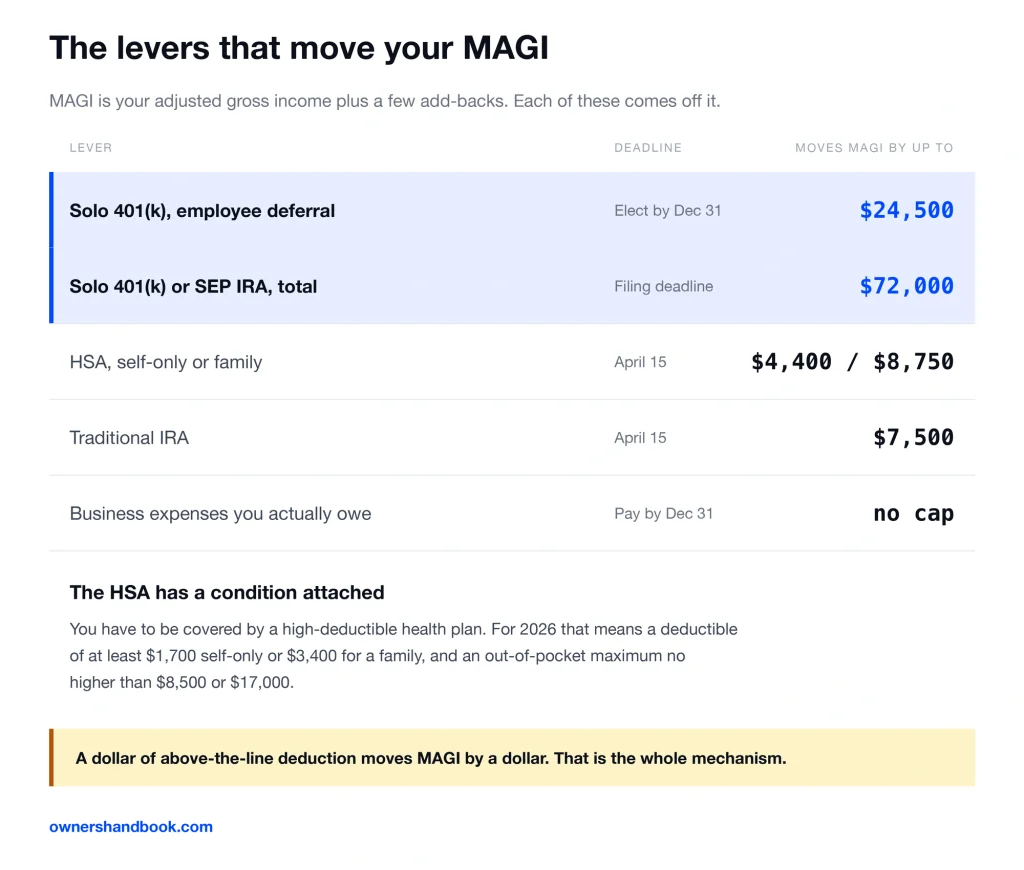
Every dollar of above-the-line deduction pulls MAGI down by a dollar. Enough of them and you land back under 400%.
| Lever | 2026 limit | When it has to happen |
|---|---|---|
| Solo 401(k), employee deferral | $24,500 | Elect by December 31 |
| Solo 401(k) or SEP IRA, total | $72,000 | Fund by your filing deadline |
| HSA, self-only | $4,400 | April 15 |
| HSA, family | $8,750 | April 15 |
| Traditional IRA | $7,500 | April 15 |
| Business expenses you actually owe | No cap | Pay by December 31 |
The HSA has a condition attached. You have to be covered by a high-deductible health plan, which for 2026 means a deductible of at least $1,700 self-only or $3,400 for a family.
That plan’s out-of-pocket maximum also cannot exceed $8,500 self-only or $17,000 for a family.
An HSA is the rare account that is deductible going in, untaxed while it grows, and untaxed coming out for medical costs. If you are eligible, it is the cheapest lever on the list.
One caution on the retirement accounts. Money you contribute to clear the cliff is money you cannot spend. The tax result is real, and so is the lockup.
The months you cannot claim
The health insurance deduction has a rule that catches people who change jobs mid-year.
You cannot take it for any month you were eligible to participate in a subsidized health plan through your own employer or your spouse’s.
Eligible, not enrolled. Declining your spouse’s plan does not hand the deduction back to you.
So it is figured month by month. Take a W-2 job with benefits in September, and the deduction covers January through August only.
That same eligibility works against the premium tax credit. If an employer plan is available to you and it counts as affordable, the marketplace credit is off the table for those months.
What to do before the year closes
Three moves, in this order.
Write down one number: what you expect your 2026 MAGI to be. Then write the 400% cutoff for your household size next to it. Most people have never seen those two figures side by side.
Watch the gap as December work comes in. A cash-basis freelancer controls when an invoice gets paid, and a January payment is January income.
Then use open enrollment. For 2027 coverage it runs November 1, 2026 through January 15, 2027, and you choose a plan by stating the income you expect to earn.
That estimate has teeth. If you take the credit in advance each month, the marketplace pays your insurer now and Form 8962 reconciles it when you file.
Guess low, end up over 400%, and you repay the entire advance credit. Under 400% there are dollar caps on what you give back. At 400% and above there is no cap at all.
That is the sentence worth remembering. The cliff is not only a larger premium. It is a bill in April for credit you already spent.
Frequently asked questions
Is the 400% cutoff based on my Schedule C profit or my total income?
Neither exactly. It is household MAGI, which starts from your profit but adds a spouse’s wages, interest, and everything else that lands on the return.
Does the cliff apply if I could get insurance through my spouse’s job?
No, because the premium tax credit is already unavailable for any month you were eligible for that employer plan. The self-employed health insurance deduction is gone for those months too.
Can I just deduct premiums on Schedule C instead?
No. Health insurance is not a Schedule C expense. It belongs on Schedule 1, line 17, which is why it cuts income tax and AGI but leaves self-employment tax untouched.
What happens if I go over 400% after taking the credit every month?
You repay all of it when you file. The repayment caps that protect people under 400% of poverty do not apply once you reach the line.
Does a Solo 401(k) contribution really change my subsidy eligibility?
Yes. It is an above-the-line deduction, so it lowers AGI and therefore MAGI. For 2026 the employee deferral alone can be up to $24,500.
What is the cutoff for 2027 coverage?
2027 uses the 2026 poverty guidelines, which are $15,960 for one person and $33,000 for four. Four times those figures is $63,840 and $132,000, unless Congress changes the rule first.
Sources
HHS, Poverty Guidelines
https://aspe.hhs.gov/topics/poverty-economic-mobility/poverty-guidelines
KFF, What We Know So Far About 2026 ACA Marketplace Enrollment and Premiums
KFF, A Steep Subsidy Cliff Looms for Older Middle-Income Enrollees
IRS, Eligibility for the Premium Tax Credit
IRS, Revenue Procedure 2025-25, 2026 Applicable Percentage Table
https://www.irs.gov/pub/irs-drop/rp-25-25.pdf
IRS, Instructions for Form 7206, Self-Employed Health Insurance Deduction
https://www.irs.gov/instructions/i7206
IRS, Publication 974, Premium Tax Credit
https://www.irs.gov/publications/p974
IRS, Instructions for Form 8962, Premium Tax Credit
https://www.irs.gov/instructions/i8962
IRS, Revenue Procedure 2025-19, 2026 HSA and HDHP Limits
https://www.irs.gov/pub/irs-drop/rp-25-19.pdf
IRS, 401(k) Limit Increases to $24,500 for 2026
https://www.irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500
HealthCare.gov, Dates and Deadlines