Business Expenses Are Not Itemized Deductions
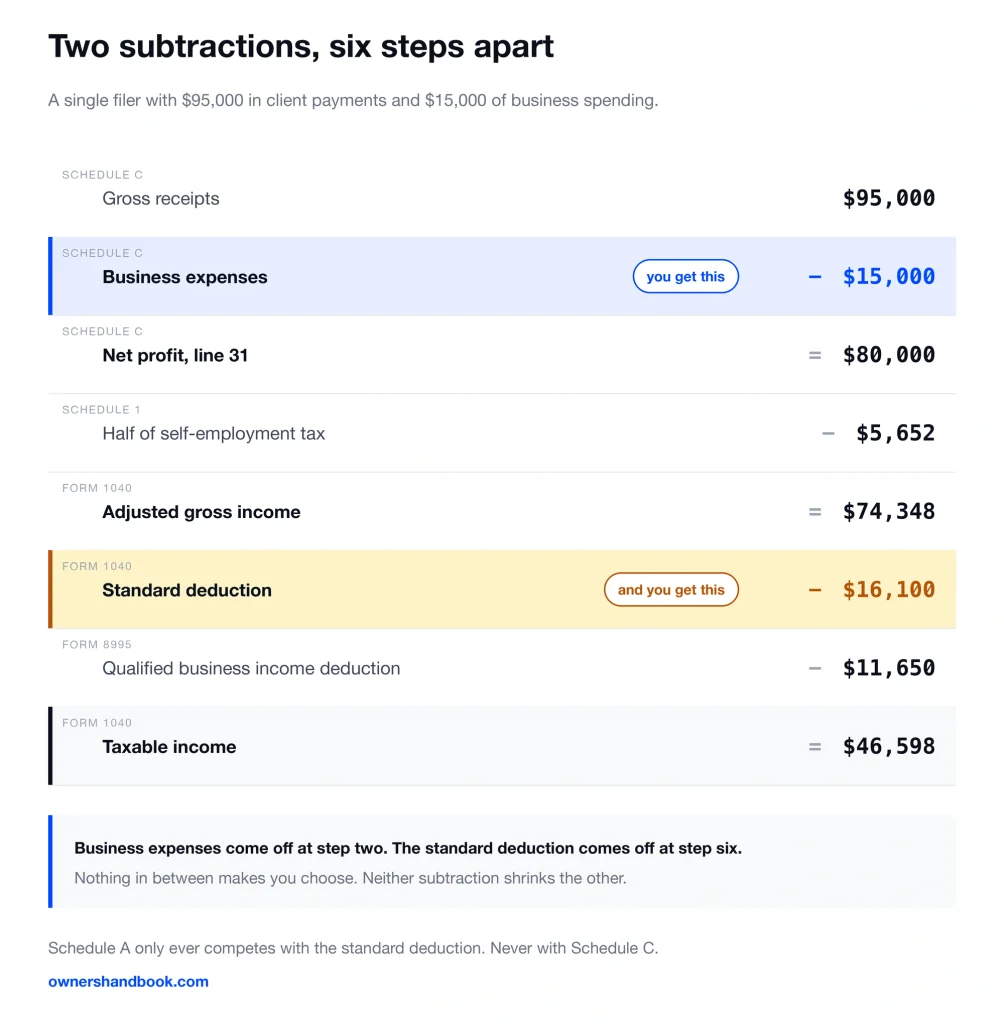
Business expenses are not itemized deductions. They come off on Schedule C, before your adjusted gross income is even calculated, and you get every one of them whether you take the standard deduction or itemize. Taking the $16,100 standard deduction does not cost you your laptop, your software, or your mileage. These are two different lists at two different stages, and you get both.
Two lists that never compete
The mistake sounds reasonable, which is why it is so common.
You hear that you choose between the standard deduction and itemizing. You take the standard deduction. You conclude that your business spending was covered by it, and you leave Schedule C’s expense section thin or empty.
It was not covered. Nothing on Schedule A has anything to do with your business.
Schedule C is your business’s own profit-and-loss statement. Money in at the top, money out below it, profit at the bottom.
Schedule A is a list of personal deductions — your mortgage interest, your state taxes, your charitable giving. That is the list the standard deduction replaces.
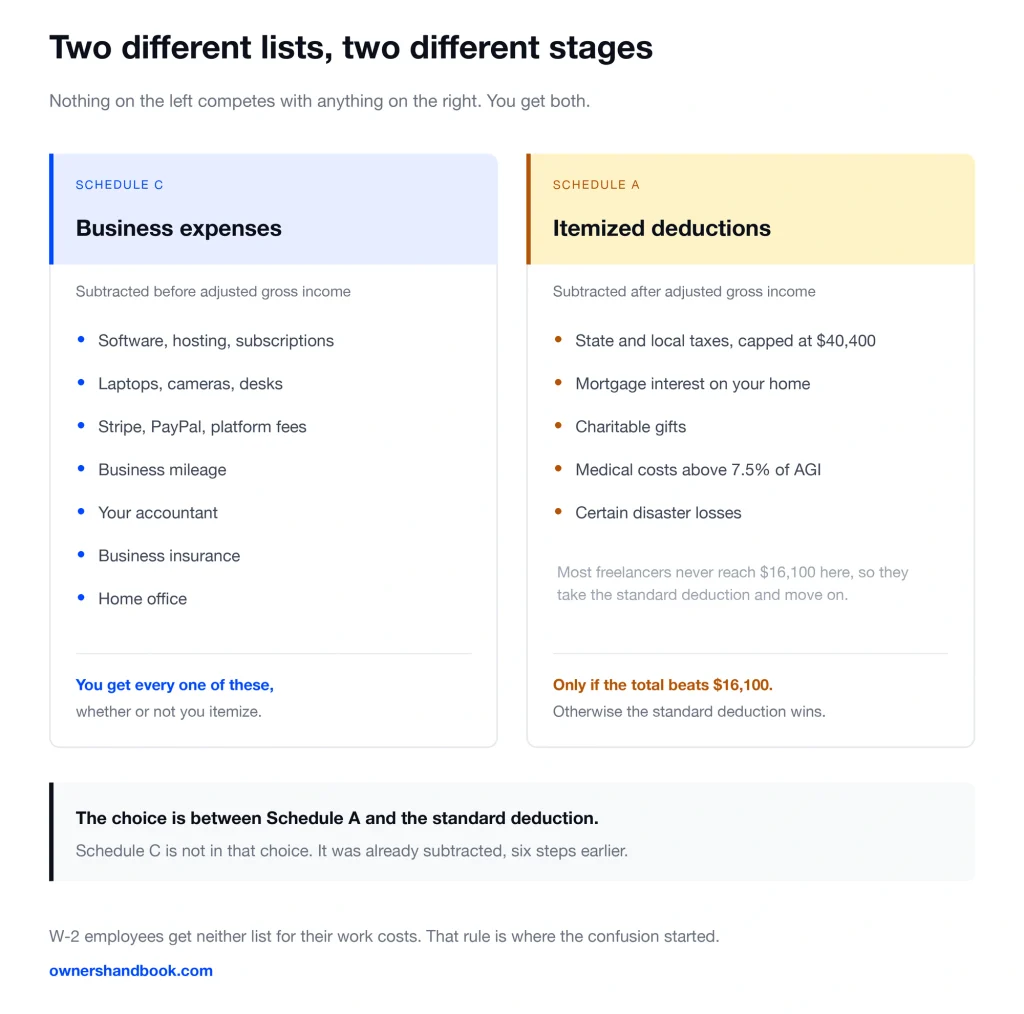
The choice you make is between the standard deduction and Schedule A. Schedule C is not in that conversation. It already happened.
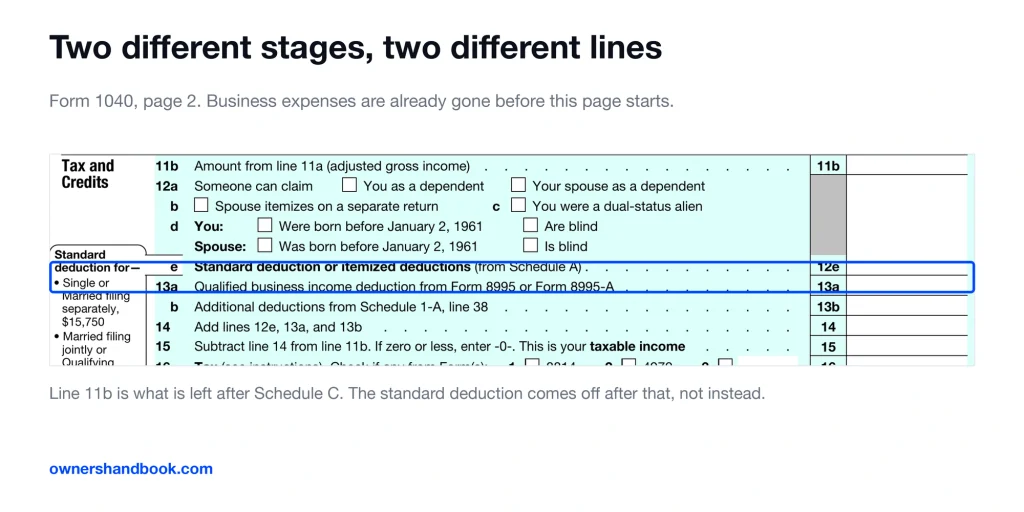
By the time your return asks whether you want the standard deduction, your business expenses have been subtracted for several steps. The question is about what is left over.
| Schedule C, business expenses | Schedule A, itemized deductions |
|---|---|
| Software, hosting, subscriptions | State and local taxes, capped at $40,400 in 2026 |
| Laptops, cameras, desks | Mortgage interest on your home |
| Stripe, PayPal, and platform fees | Charitable gifts |
| Business mileage | Medical costs above 7.5% of your AGI |
| Your accountant, business insurance | Certain federally declared disaster losses |
| Comes off before AGI | Comes off after AGI |
| You get these either way | Only if the total beats $16,100 |
What a business expense does that the standard deduction cannot
A Schedule C expense lowers your net profit. Net profit is the number self-employment tax is charged on.
So a business expense cuts two taxes. Income tax, and the 15.3% self-employment tax that funds Social Security and Medicare.
The standard deduction cuts one. It comes off after self-employment tax has already been figured, so it never touches it.
That is why $1,000 of business expense is worth more to you than $1,000 of anything on Schedule A. It is doing twice the work.
There is a second difference. The standard deduction is one fixed number, the same for everyone with your filing status. Business expenses are whatever you actually spent, with no ceiling on them.
A year with $40,000 of legitimate spending deducts $40,000. The standard deduction stays $16,100 regardless, and you still get it.
What actually goes on Schedule A
Four things, for most people.
State and local taxes — income tax or sales tax, plus property tax. Capped at $40,400 for 2026, or $20,200 if you file separately.
Mortgage interest on your home. Your home, not your studio.
Charitable contributions to qualified organizations.
Medical and dental expenses, but only the part above 7.5% of your adjusted gross income. Most people never clear that line.
Read that list again and notice what is missing. No laptops. No software. No mileage. No client lunches. Schedule A is a list of personal costs Congress decided to subsidize, not a list of what it costs to run your business.
Most freelancers do not itemize at all, because $16,100 is more than their personal deductions add up to. That is fine. It changes nothing about Schedule C.
The order of operations
The forms run in a fixed sequence, and knowing it settles the question permanently.
Gross receipts. Everything clients paid you.
Minus business expenses. Schedule C, Part II.
Equals net profit. Schedule C line 31. This is the number that goes to Schedule SE for self-employment tax.
Minus above-the-line adjustments, a short list of deductions that come off before the standard deduction is even considered. Half of your self-employment tax, self-employed health insurance, retirement contributions. These sit on Schedule 1.
Equals adjusted gross income, or AGI — the subtotal the rest of the return keys off.
Minus the standard deduction or your itemized total, whichever is larger.
Minus the qualified business income deduction, generally 20% of your business profit. You get this whether you itemize or not.
Equals taxable income.
Business expenses are step two. The standard deduction is step six. There is no stage where one displaces the other.
$95,000 in, $15,000 out
Here is a single filer with $95,000 in client payments and $15,000 in real business spending, taking the standard deduction.
| Step | Amount |
|---|---|
| Gross receipts | $95,000 |
| Business expenses | −$15,000 |
| Net profit, Schedule C line 31 | $80,000 |
| Half of self-employment tax, Schedule 1 | −$5,652 |
| Adjusted gross income | $74,348 |
| Standard deduction, single, 2026 | −$16,100 |
| Qualified business income deduction | −$11,650 |
| Taxable income | $46,598 |
Follow what the $15,000 did. It came off at the top, so net profit fell from $95,000 to $80,000.
Self-employment tax is charged on 92.35% of that profit at 15.3%. On $80,000 that is $11,304, and half of it comes off again as an adjustment.
The $16,100 standard deduction still lands in full, four rows lower. Nothing about the expenses reduced it.
The qualified business income deduction then takes another $11,650 off. Also unaffected.
Taxable income lands at $46,598, from $95,000 of client payments. Every subtraction happened, in order, none cancelling another.
What skipping the expenses costs
Run the same person again, but assume they believed the standard deduction covered their spending and reported no expenses.
Net profit becomes $95,000. Self-employment tax rises to $13,423. Taxable income lands at $57,750 instead of $46,598.
Two extra bills. About $2,119 more in self-employment tax, and about $2,073 more in income tax across the 12% and 22% brackets.
Roughly $4,200, paid on money that was already spent on the business. The receipts existed. The belief is what cost the money.
And this compounds. Someone who does it for three years has overpaid something near $12,000, with nothing on the return to signal that anything went wrong.
Why the confusion exists
This misunderstanding has a real origin, and it is worth knowing, because it is true for a different group of people.
W-2 employees genuinely cannot deduct their work expenses. Unreimbursed employee expenses were eliminated starting in 2018, and they remain gone.
An employee who buys a $2,000 laptop for the job deducts nothing. Not on Schedule A, not anywhere.
That rule got repeated widely enough that self-employed people absorbed it too. It does not apply to you. You are not an employee of your business — you are the business, and a business deducts what it spends to operate.
The only path to your deductions is Schedule C. Fill it out completely, and take the standard deduction on top of it.
Frequently asked questions
Do I lose my business deductions if I take the standard deduction?
No. Business expenses come off on Schedule C, before adjusted gross income. The standard deduction comes off after. You get both, in full.
Should I itemize instead so I can deduct my laptop?
Itemizing has no effect on your laptop either way. The laptop belongs on Schedule C. Itemize only if your mortgage interest, state taxes, and charitable gifts together beat $16,100.
Where do my business expenses go if not on Schedule A?
Schedule C, Part II, lines 8 through 27. Anything without a line of its own gets written into Part V and totalled on line 27.
Does the standard deduction lower my self-employment tax?
No. Self-employment tax is calculated on Schedule C net profit, which is settled before the standard deduction appears. Only business expenses reduce it.
I have a W-2 job and freelance on the side. Can I deduct expenses from both?
Only the freelance ones. Expenses for your self-employed work go on Schedule C. Expenses tied to the W-2 job are not deductible.
Can my business expenses be larger than my business income?
Yes. That is a loss, and it generally offsets your other income for the year. A first year with equipment purchases often ends this way.
Sources
IRS, IRS releases tax inflation adjustments for tax year 2026
IRS, Topic no. 501, Should I itemize?
https://www.irs.gov/taxtopics/tc501
IRS, About Schedule A (Form 1040), Itemized Deductions
https://www.irs.gov/forms-pubs/about-schedule-a-form-1040
IRS, Instructions for Schedule A (Form 1040)
https://www.irs.gov/instructions/i1040sca
IRS, Correction to state and local income tax deduction amount in the 2026 Form 1040-ES
IRS, Instructions for Schedule C (Form 1040)
https://www.irs.gov/instructions/i1040sc
IRS, Publication 334, Tax Guide for Small Business
https://www.irs.gov/publications/p334
IRS, Qualified business income deduction
https://www.irs.gov/newsroom/qualified-business-income-deduction
IRS, Instructions for Form 2106, Employee Business Expenses