Paying Yourself Is Not a Business Expense
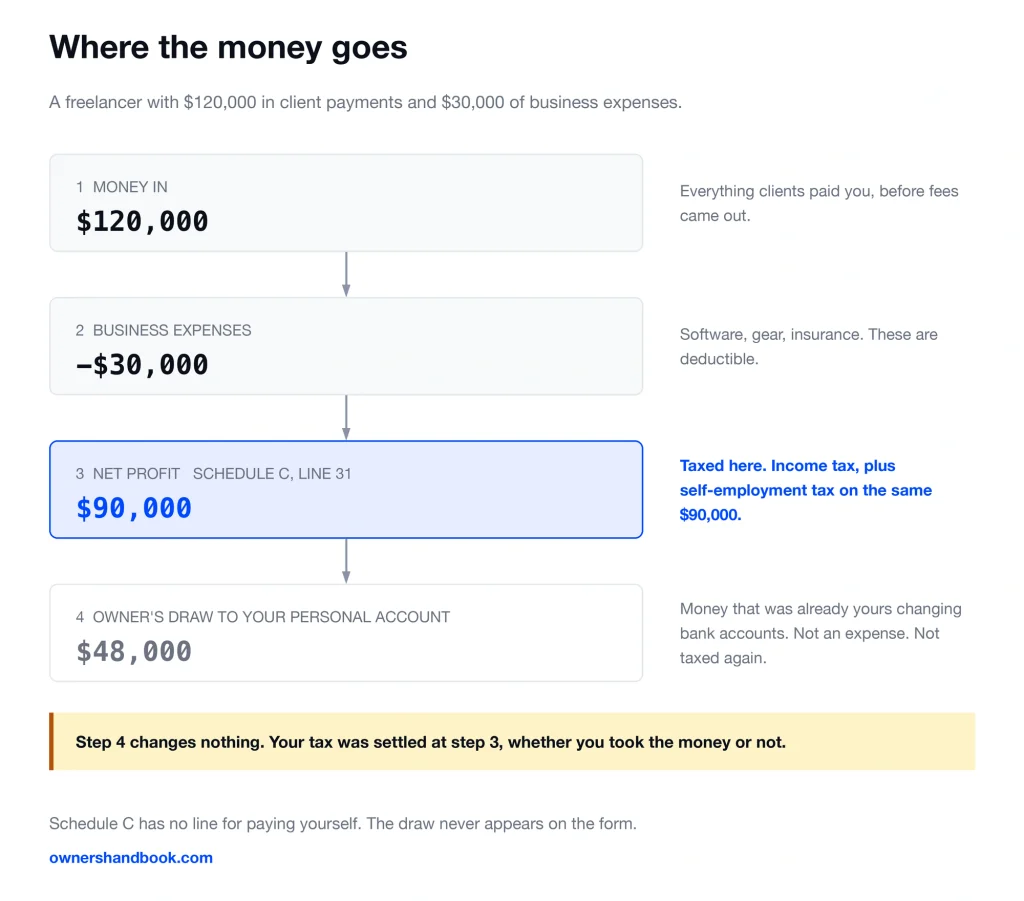
Moving money from your business account to your personal account is a draw, not an expense. It does not reduce your profit, it does not appear anywhere on Schedule C, and it does not lower your tax by a dollar. As a sole proprietor you are taxed on what the business earned, not on what you paid yourself.
A draw is not an expense
An expense is money that leaves your hands and does not come back. Rent, software, a camera, a contractor’s invoice.
The money is gone. That is why it comes off your income.
A draw is different. Money moves from one account you own to another account you own. Nothing left. Your net worth did not change by a cent.
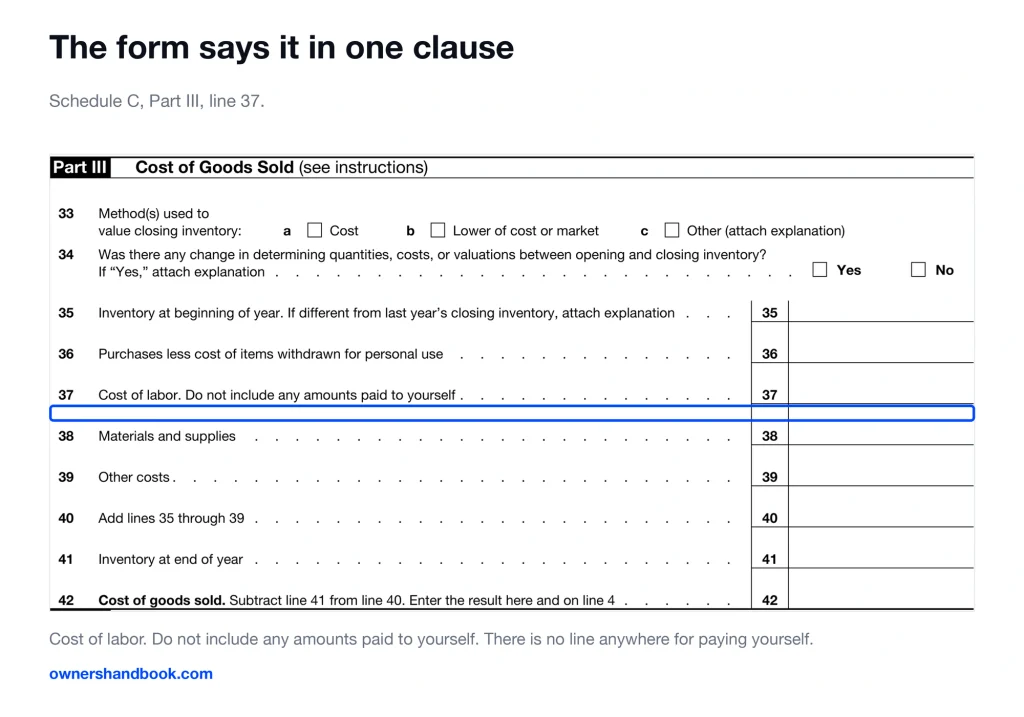
Which is why there is no line for it. Look at Schedule C, Part II. Twenty expense categories, lines 8 through 27, and not one of them is for paying the owner.
Line 26 is wages, and the instructions close that door in one sentence: do not include amounts paid to yourself.
The word draw is bookkeeping vocabulary, not tax vocabulary. Your accounting software tracks it in an owner’s equity account so the books balance. The tax return never sees it.
The tax does not care when you take the money out
This is the same rule running in the other direction, and it catches the careful people.
Say you earned $90,000 of profit and left $70,000 of it in the business account for next year’s slow months. You took only $20,000 home.
You are still taxed on $90,000.
Leaving profit in the business defers nothing. There is no corporate shell standing between you and the income.
An LLC does not create one either. The IRS calls a one owner LLC a disregarded entity, meaning the entity is ignored and its activity is reported on the owner’s own return.
Under the cash method you report income when you actually or constructively receive it. Constructive receipt means the money was credited to you and available without restriction, whether you touched it or not.
The client’s payment landed in an account you control. That is receipt. Which of your accounts it sits in afterward is a bookkeeping detail.
The mistake, in numbers
Here is the version that costs real money.
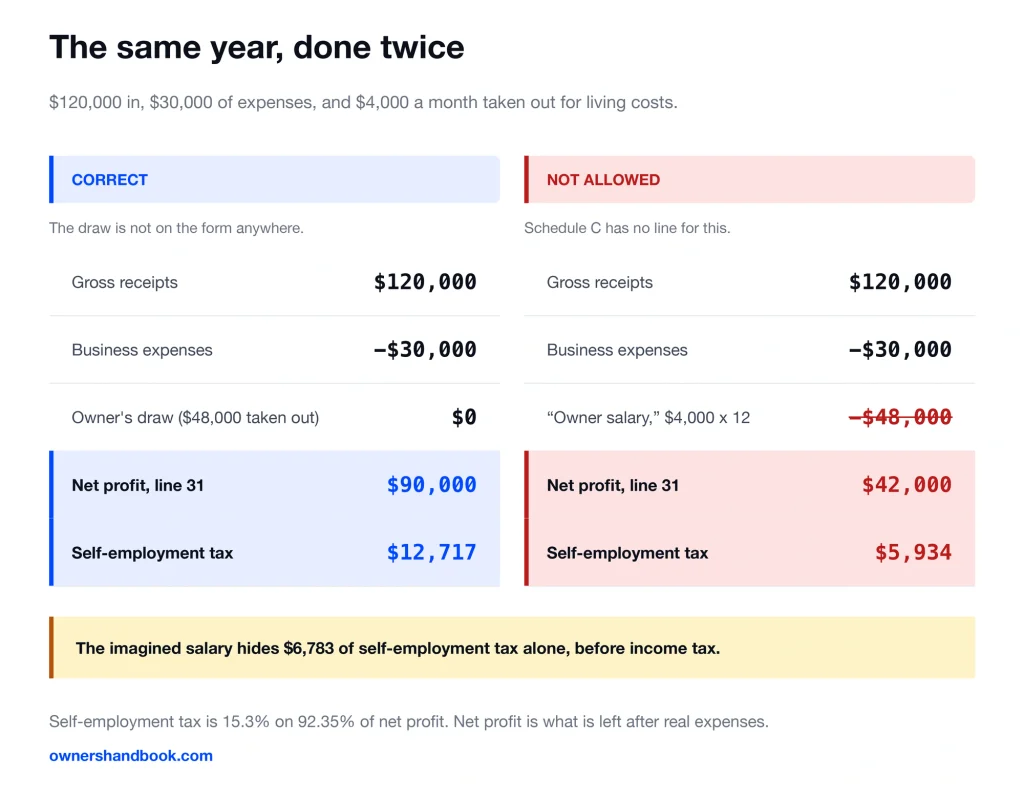
You bill $120,000 and spend $30,000 running the business. You take $4,000 a month for rent and groceries, which is $48,000 across the year.
Then you do the return and treat that $48,000 as an owner salary expense.
| Line | Done correctly | With an imagined owner salary |
|---|---|---|
| Gross receipts | $120,000 | $120,000 |
| Business expenses | −$30,000 | −$30,000 |
| Owner salary | Not a line on the form | −$48,000 |
| Net profit, line 31 | $90,000 | $42,000 |
| Self-employment tax | $12,717 | $5,934 |
The right answer is $90,000 of profit. The imagined answer is $42,000. Same year, same bank, same work.
Self-employment tax is 15.3% on 92.35% of net profit. On $90,000 that comes to $12,717. On $42,000 it comes to $5,934.
So the phantom deduction hides $6,783 of self-employment tax on its own, before income tax enters the picture.
Income tax on the same $48,000 adds roughly $9,800 more in the 22% bracket. The qualified business income deduction, a 20% write-off on profit that passes through to your personal return instead of being taxed at the business, narrows that gap somewhat but does not close it.
None of it is real money saved. The return gets corrected, and the difference comes back with interest.
You cannot put yourself on payroll
A sole proprietor and a single-member LLC owner are in the same position here. You are not an employee of your own business.
So there is no W-2 to issue yourself, nothing to withhold from your own draw, and no 1099-NEC to send yourself either.
The IRS is explicit that the paperwork does not create the relationship. You cannot designate a worker, including yourself, as an employee or an independent contractor solely by issuing a Form W-2 or a Form 1099-NEC.
Filing one anyway does not make the deduction work. It creates a mismatch that somebody has to unwind: income reported twice, and a wage form with no payroll deposits behind it.
Your Social Security and Medicare contributions are already being made. That is what self-employment tax is, computed on Schedule SE starting from your Schedule C profit.
The S corporation is where an owner is an employee
If your business elects S corporation treatment and you work in it, the rule flips. You become a shareholder employee, and you do go on payroll.
The IRS states it plainly. An S corporation must pay reasonable compensation to a shareholder employee for services provided, before non-wage distributions may be made to that shareholder.
So you take a W-2 salary at a defensible market rate, with payroll taxes withheld, and you can take distributions on top of it. The salary is deductible by the corporation. The distributions are not.
Set the salary too low and the IRS can reclassify those distributions as wages, with employment taxes attached. Courts have repeatedly upheld that power.
| Structure | How you take money out | What the business deducts |
|---|---|---|
| Sole proprietor | Owner’s draw | Nothing. A draw is not an expense. |
| Single-member LLC | Owner’s draw | Nothing. Taxed as a sole proprietorship. |
| Partnership | Draw or guaranteed payment | Reported on a Schedule K-1, never a W-2 |
| S corporation | W-2 wages, then distributions | The wages only |
What the business bank account is actually for
Publication 583 is unusually blunt. Open a business checking account when you start. Keep it separate from your personal account. Deposit all business receipts into it. Use it for business purposes only.
Then comes the line that matters here. Write checks payable to yourself only when making withdrawals from your business for personal use.
That is a draw, given a shape. One labeled transfer, on a date, out of an account that holds nothing else.
Commingling, meaning running business and personal money through a single account, destroys that shape. Every transaction then has to be sorted later from memory.
The real cost is not the sorting. It is that a mixed account makes your profit hard to prove. When someone asks where the $90,000 came from, you want a bank statement, not a story.
Paying your spouse or your child is a different thing
You cannot deduct paying yourself. You can deduct paying a family member, provided it is real work at a reasonable wage.
Hire your spouse and their wages are subject to income tax withholding and to Social Security and Medicare taxes, but not to federal unemployment tax. The wages go on Schedule C, line 26, like any other employee’s.
Hire your own child under 18 in your sole proprietorship and their pay is exempt from Social Security and Medicare taxes. Under 21, it is also exempt from federal unemployment tax. Income tax withholding applies at any age.
The condition is that it has to be genuine. Actual work, an actual rate someone else would be paid for it, actual payroll records kept as you go.
A number invented in December is not a wage, and it is the first thing that falls apart if anyone asks.
Frequently asked questions
Is an owner’s draw taxable income?
Not separately. You are taxed on the business’s net profit, and a draw is that already taxed money moving to your personal account. Reporting the draw as income would tax the same dollars twice.
Do I pay self-employment tax on what I withdraw?
No. Self-employment tax is figured from Schedule C line 31, your net profit. Schedule SE starts with that number and never asks what you took out.
Can I lower my tax by leaving profit in the business account?
No. Profit is taxed in the year you earned it, wherever the money is sitting on December 31. Leaving it in the business defers nothing.
Does forming an LLC change any of this?
Not by itself. A single-member LLC is a disregarded entity that files Schedule C, and its owner takes draws exactly like a sole proprietor. Electing S corporation treatment is the change that matters.
How much am I allowed to draw?
Whatever the business can afford. There is no tax limit on it. Keep back enough for your quarterly estimated payments, since nobody is withholding anything for you.
Should I record draws in my bookkeeping at all?
Yes. Put them in an owner’s equity account, not an expense account. The books stay balanced and the profit that goes on your return is untouched.
Sources
IRS, Instructions for Schedule C
https://www.irs.gov/instructions/i1040sc
IRS, About Schedule C (Form 1040)
https://www.irs.gov/forms-pubs/about-schedule-c-form-1040
IRS, Single Member Limited Liability Companies
IRS, Paying Yourself
https://www.irs.gov/businesses/small-businesses-self-employed/paying-yourself
IRS, Self-Employment Tax (Social Security and Medicare Taxes)
IRS, About Schedule SE (Form 1040)
https://www.irs.gov/forms-pubs/about-schedule-se-form-1040
IRS, S Corporation Compensation and Medical Insurance Issues
IRS, Publication 583, Starting a Business and Keeping Records
https://www.irs.gov/publications/p583
IRS, Publication 538, Accounting Periods and Methods
https://www.irs.gov/publications/p538
IRS, Family Help
https://www.irs.gov/businesses/small-businesses-self-employed/family-help
IRS, Married Couples in Business
https://www.irs.gov/businesses/small-businesses-self-employed/married-couples-in-business