Quarterly Estimated Taxes in 2026: The Four Dates
Four dates: April 15, June 15, September 15, and January 15 of the following year. Send 100% of last year’s total tax, split into four, and the IRS cannot penalize you no matter what you actually end up owing. Make that 110% if last year’s adjusted gross income was over $150,000. If you miss one, the cost is interest at roughly 7% a year on the shortfall, not a flat fine.
The dates are not what you think
Most people hear “quarterly” and assume every three months. Then they pay the June one in July and get a letter.
Look at what each payment actually covers.
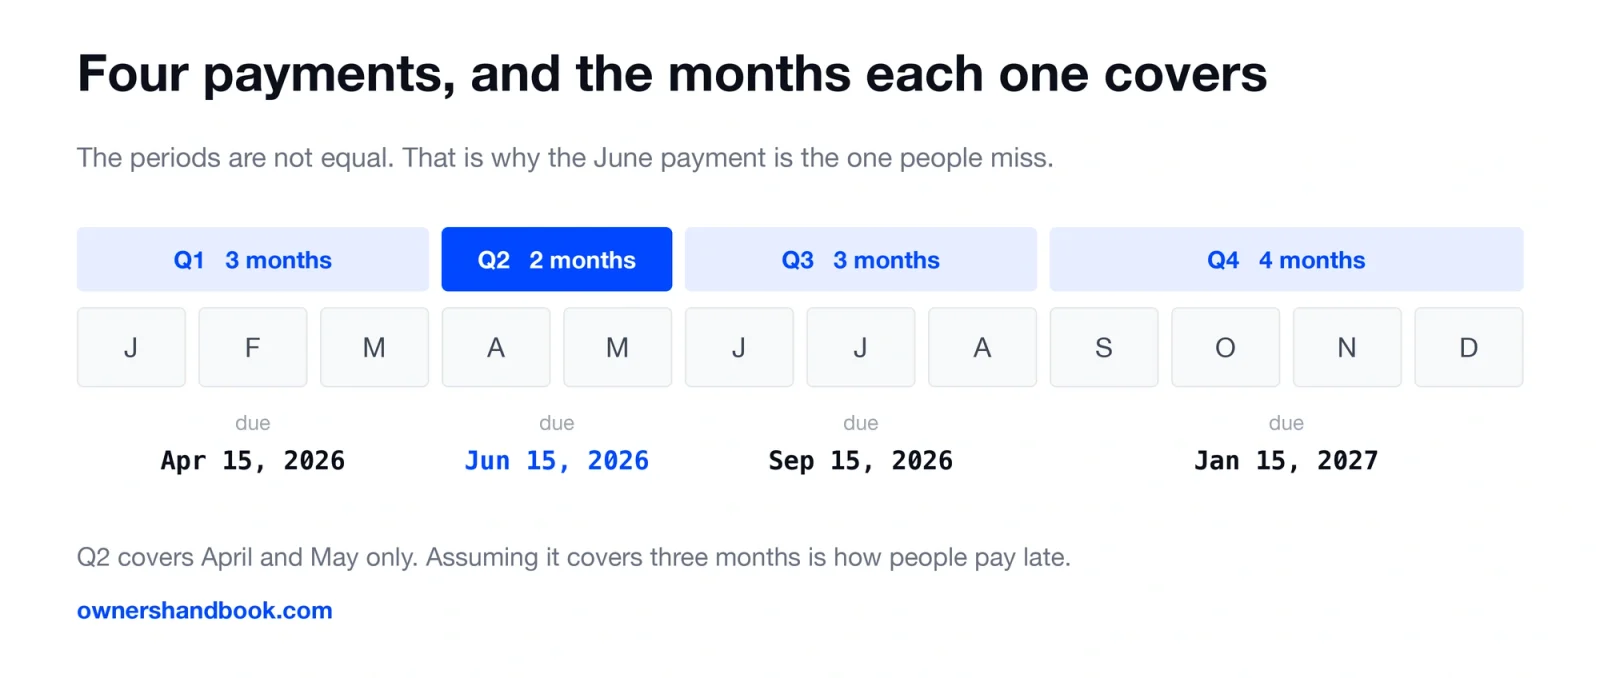
Q1 covers three months. Q2 covers two. Q3 covers three. Q4 covers four.
| Payment | Months it covers | Due date |
|---|---|---|
| Q1 | January to March, 3 months | April 15, 2026 |
| Q2 | April to May, 2 months | June 15, 2026 |
| Q3 | June to August, 3 months | September 15, 2026 |
| Q4 | September to December, 4 months | January 15, 2027 |
The IRS did not design this to be logical. It is a legacy of how the calendar and the filing season line up, and nobody has fixed it. Put the four dates in your calendar and stop trying to reason about them.
One more thing. If a date falls on a weekend or holiday, it moves to the next business day. For 2026 all four land on weekdays, so there is no shift this year.
How much to send
There are two ways to arrive at a number. One requires you to predict the future.
The forecasting method: estimate your full-year income, calculate the tax, divide by four. This is accurate if your income is steady and worthless if it is not.
The safe harbor: pay a fixed percentage of what you owed last year, and the penalty cannot touch you.
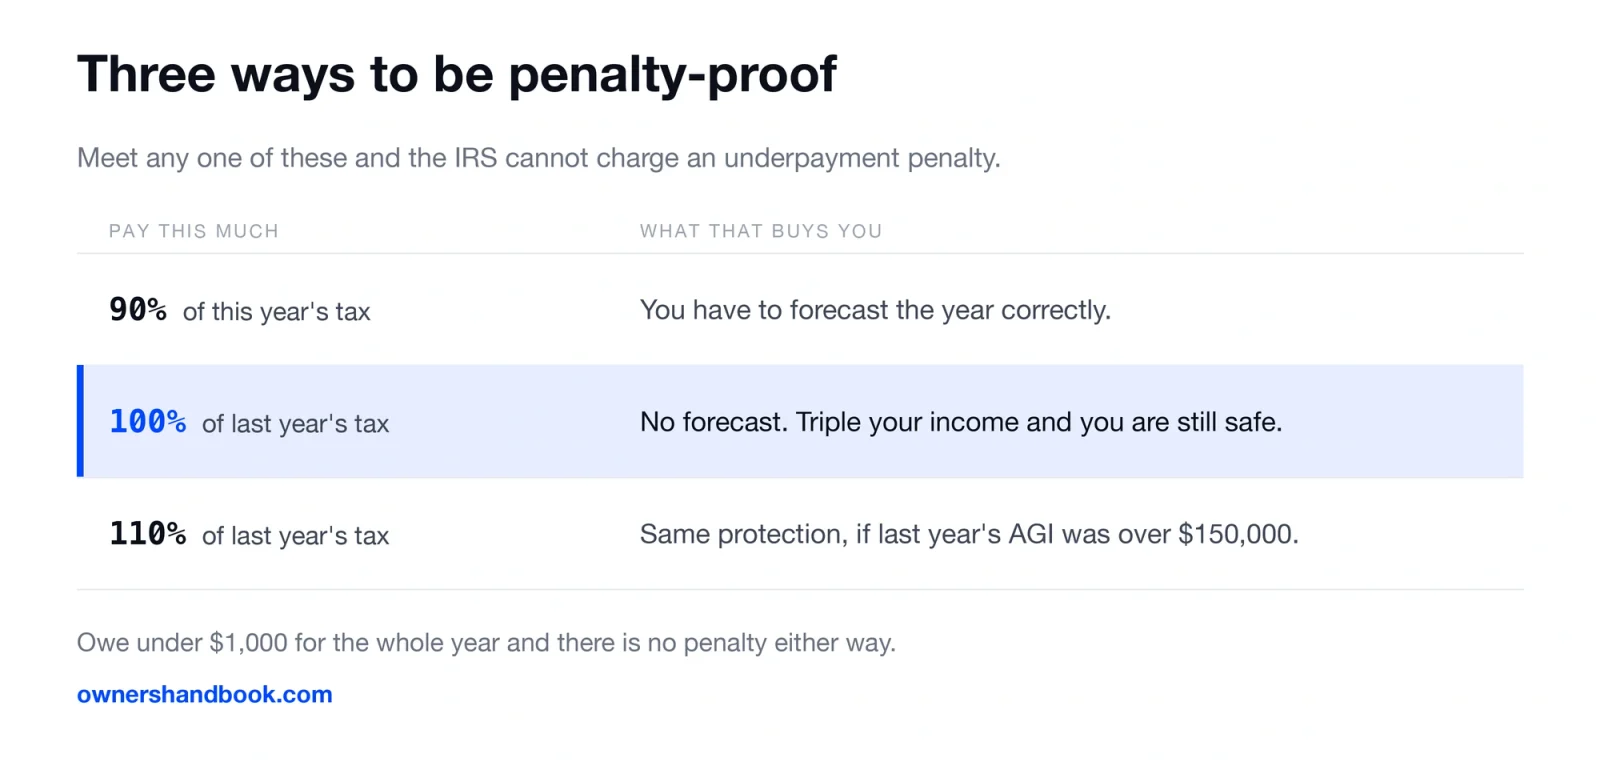
| Pay this much | What that buys you |
|---|---|
| 90% of this year’s tax | Nothing unless your forecast is right |
| 100% of last year’s tax | Immunity. Your income can triple and the penalty cannot touch you. |
| 110% of last year’s tax | The same, if last year’s AGI was over $150,000 |
Read that middle row again. If you pay 100% of last year’s total tax and then triple your income, you still owe no penalty. You will owe the tax itself in April, but not a cent of penalty on top.
That is the whole point of the safe harbor. You are not trying to guess correctly. You are buying immunity while you figure out the real number.
The 110% version applies if your adjusted gross income last year was over $150,000.
Adjusted gross income, or AGI, is your total income after a short list of specific deductions but before the standard deduction. On your 1040 it sits at the bottom of the first page.
For married filing separately the line is $75,000.
Where to find your number
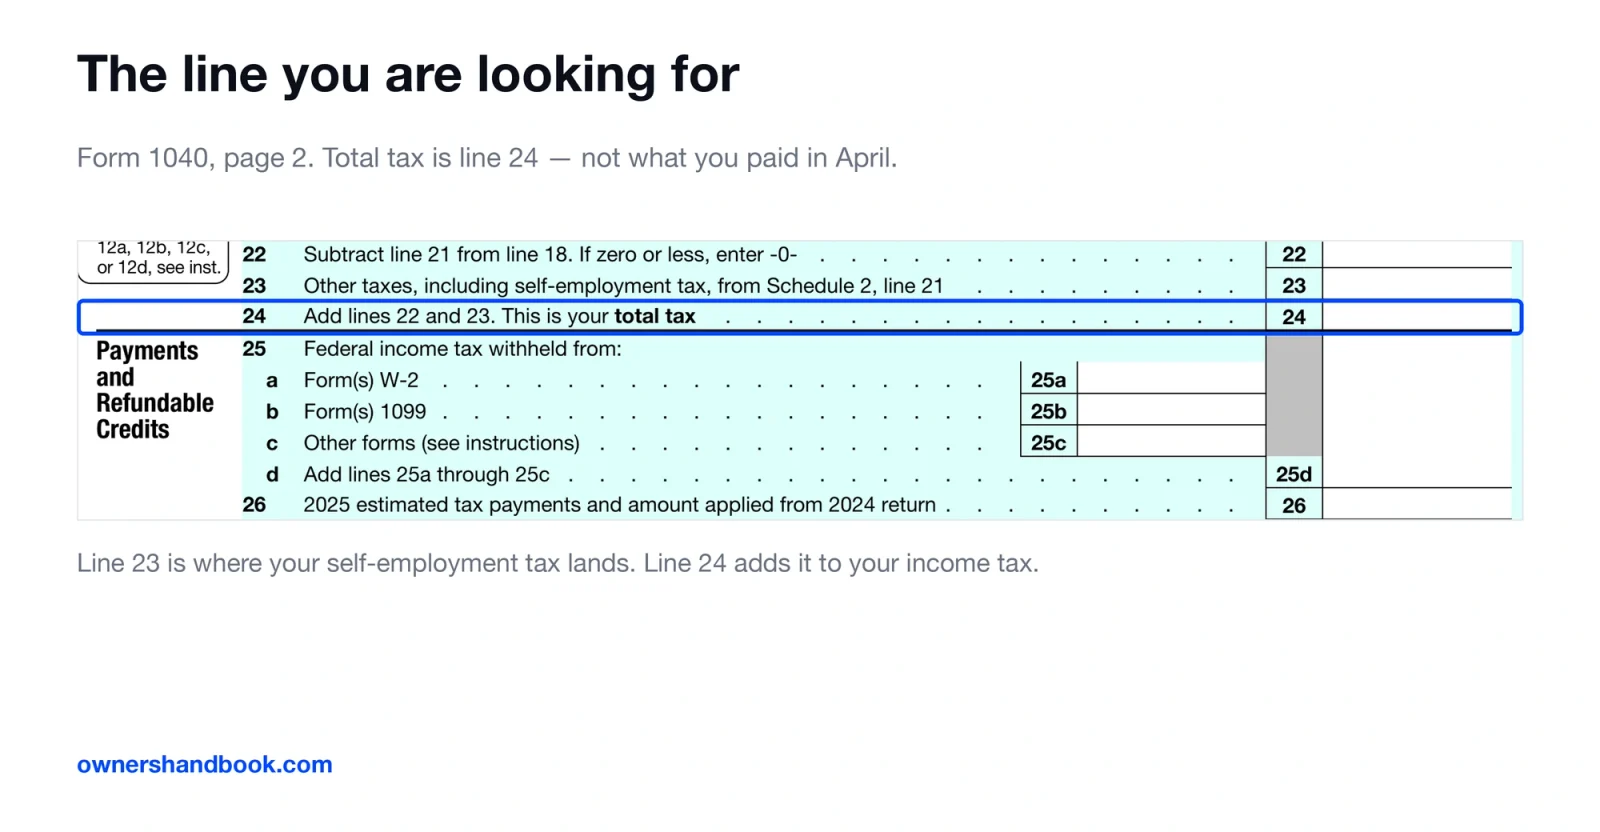
Pull up last year’s Form 1040 and look for the line labeled total tax, near the bottom of the second page.
That is the whole bill for the year, before anything you already paid was taken off it.
It is not the line called amount you owe. That one is what was left after withholding and estimated payments, and it is usually much smaller. It is not your refund either.
People grab the wrong number here constantly, and it is always the same mistake: using what they wrote the check for in April instead of the full year’s tax.
Divide total tax by four. That is your quarterly payment, or a quarter of 110% of it if your adjusted gross income was over $150,000. There is a calculator that works this out if you would rather put your own figures in.
If this is your first year with self-employment income and you have no prior return showing tax, the safe harbor has nothing to lock onto. Estimate from projected profit instead, set aside 25% to 30%, and expect to adjust in year two.
Projected profit means revenue minus the expenses you will actually claim, which is the arithmetic Schedule C does. Running Schedule C once with rough numbers in June gives you a far better estimate than guessing from deposits.
The penalty is interest, not a fine
This is the part almost everyone gets wrong, and getting it wrong leads to bad decisions.
The IRS does not charge a flat penalty for a late estimated payment. It charges interest on the amount you underpaid, running from the day it was due until the day you pay it.
The rate is the federal short-term rate plus three percentage points. It is reset four times a year and compounds daily.
In 2026 it has run between 6% and 7%.
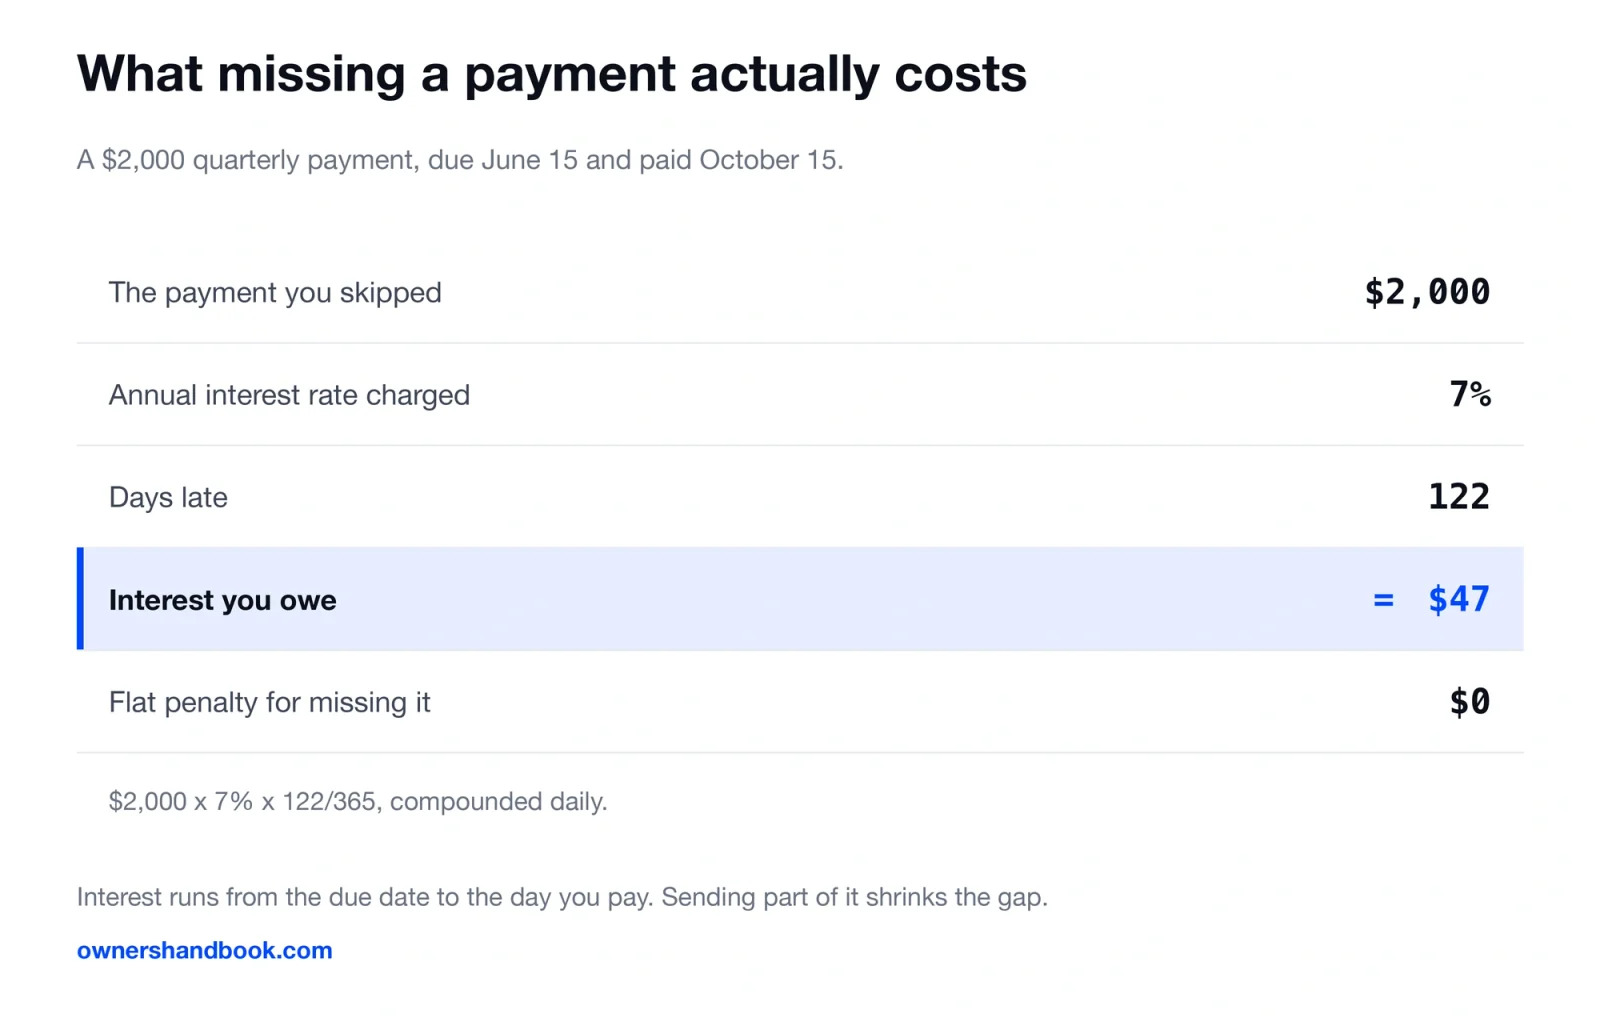
Forty-seven dollars. That is the actual cost of missing a $2,000 payment by four months.
Knowing this changes the decision in front of you. If you are short in June, do not skip the payment and hope. Send what you can. The interest only accrues on the gap.
And if you owe less than $1,000 for the year after withholding and credits, there is no penalty at all.
If you have already missed payments this year, there is a way back. Send what you can now, because the interest only runs on the gap.
How to actually pay
IRS Direct Pay. It is free, it takes about three minutes, and it works from a browser.
Go to irs.gov/directpay. Choose Estimated Tax as the reason and 1040ES as the form. Enter the tax year. Verify your identity with a prior year return, then pay from a checking account.
Save the confirmation number. If a payment ever goes missing, that number is what resolves it.
Two things to avoid.
Paying by card costs a processing fee of roughly 2%. On a $3,000 payment that is $60 you did not need to spend.
Mailing a check means the postmark date counts. It has to be in the mail before the deadline, not on it.
One thing this page does not cover. If your state taxes income, it almost certainly wants its own quarterly payments, on its own schedule, through its own website. Federal is half the job.
Can I increase my W-2 withholding instead of paying quarterly?
Yes, and if you have a job alongside the freelancing it is usually the better move. Everything above assumes estimated payments are your only option. If you also draw a W-2 paycheck, they are not.
Withholding is treated as though it was paid evenly across the entire year, regardless of when it actually came out. Estimated payments are credited on the day you make them.
So you can raise your withholding in November and the IRS treats that money as if it arrived in equal installments starting in January. The underpayment penalty vanishes.
File a new Form W-4 with your employer and put the extra amount on line 4(c). The IRS Tax Withholding Estimator will tell you what to put there.
Three things this buys you. No four dates to remember, because payroll handles it. No penalty for a quarter you underpaid earlier in the year, because withholding is retroactively spread. And no separate transfer to make, which is the step people actually miss.
The limit is arithmetic: your paycheck has to be big enough to absorb it. Someone earning $30,000 from a part-time job and $90,000 freelancing cannot withhold their way out of the whole bill. Cover what you can through the W-4 and pay the rest as estimates.
This is covered in more detail in the self-employment tax guide.
What if your income is seasonal
A photographer who earns most of the year’s money between May and September should not be sending four equal payments.
The IRS allows an annualized income installment method that matches each payment to what you actually earned in that period. It lives on Form 2210, Schedule AI.
It works. It also requires you to track income by quarter and fill out an extra schedule. For most people the safe harbor achieves the same protection with none of the paperwork.
Use the annualized method if your income is genuinely lumpy and the safe harbor number is painfully high. Otherwise skip it.
Frequently asked questions
What happens if I skip a payment entirely?
You owe interest on the full amount from its due date until you pay. There is no separate fine and no penalty for the act of missing it.
Can I pay more than the safe harbor amount?
Yes. Overpaying reduces what you owe in April and costs you nothing but the use of the money in the meantime.
Do I have to pay if I only made a little?
If you expect to owe less than $1,000 after withholding and credits, no. Self-employment tax also does not apply below $400 in net earnings for the year.
What if I paid too much?
It comes back as a refund when you file, or you can apply it to the next year’s first quarter.
Does the state have its own quarterly schedule?
Usually yes, and the dates do not always match the federal ones. Nine states have no income tax. Everyone else should check their state revenue department.
Can I change the amount partway through the year?
Yes. Each payment stands on its own. If your income drops in August you can send less in September.
Sources
IRS, Estimated Taxes
https://www.irs.gov/businesses/small-businesses-self-employed/estimated-taxes
IRS, Topic 306: Penalty for Underpayment of Estimated Tax
https://www.irs.gov/taxtopics/tc306
IRS, Quarterly Interest Rates
https://www.irs.gov/payments/quarterly-interest-rates
IRS, Form 2210
https://www.irs.gov/forms-pubs/about-form-2210
IRS, Direct Pay
https://www.irs.gov/payments/direct-pay
IRS, Tax Withholding Estimator