Quarterly Estimated Tax Calculator for Freelancers (2026)
Four dates, and a number you have to work out yourself. The IRS does not send a bill for estimated taxes — it expects you to know what to send and to send it on time. This calculator works out the safe harbor for 2026 and splits it into the four payments.
Quarterly estimated tax calculator
Works out your safe harbor for 2026 and what each of the four payments should be.
The line labelled total tax on your 2025 Form 1040. Not what you owed in April.
Decides whether your safe harbor is 100% or 110%.
Your best estimate for 2026. Leave blank if you have no idea.
From a W-2 job, if you have one.
| Safe harbor on last year’s tax (100%) | $0 |
| Safe harbor on this year’s estimate (90%) | — |
| The smaller one, which is all the law requires | $0 |
| Less what is already withheld | $0 |
| Left to pay in estimates | $0 |
The four payments
| April 15, 2026 — covers Jan 1 to Mar 31 | $0 |
| June 15, 2026 — covers Apr 1 to May 31, only two months | $0 |
| September 15, 2026 — covers Jun 1 to Aug 31 | $0 |
| January 15, 2027 — covers Sep 1 to Dec 31, four months | $0 |
Figures current for tax year 2026. The safe harbor rules and the $150,000 threshold
come from IRS Form 1040-ES.
Runs entirely in your browser — nothing you type is sent anywhere or stored.
This calculator is for informational purposes only and does not constitute legal, accounting, or tax advice.
It estimates federal quarterly payments for the 2026 tax year and does not account for state or local taxes,
credits, or your individual circumstances. If a due date falls on a weekend or holiday, the payment is on time
the next business day. Consult your own tax advisor for guidance on your situation.
Everything below explains what the calculator just did, and what to do with the answer.
What the safe harbor actually protects you from
The penalty for underpaying estimated tax is not a fine. It is interest, charged per quarter, on whatever you were short at the time.
That last part matters more than people expect. Paying the whole year in April does not undo a missed June payment, because the interest already ran from June to April. The clock is per period.
The safe harbor is the way out. Hit it and there is no penalty at all, no matter what your actual tax turns out to be.
| You are safe if you pay | The catch |
|---|---|
| 100% of last year’s total tax | 110% if last year’s AGI was over $150,000 |
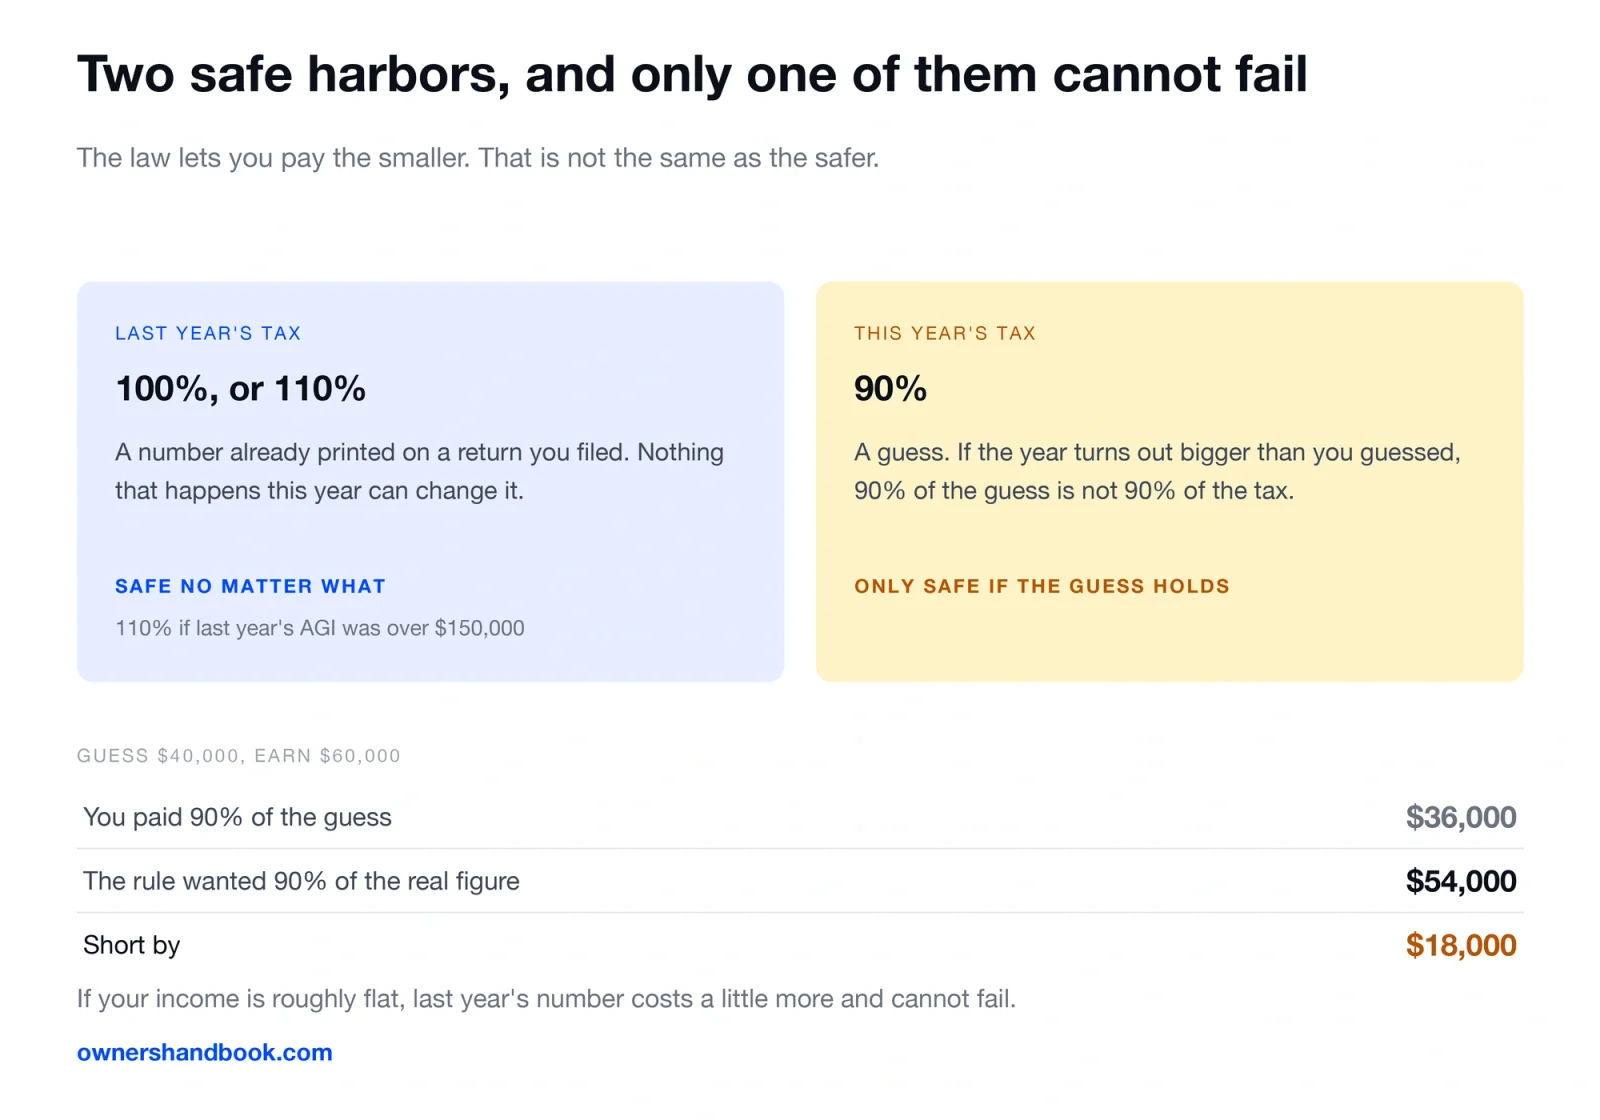
| 90% of this year’s actual tax | You have to guess this year correctly |
The law lets you pay the smaller of the two. But the two are not equally safe, and that is the part most calculators skip.
Why the smaller number is not always the safer one
Last year’s tax is a fixed number. It is printed on a return you already filed. Nothing that happens in 2026 can change it, so paying 100% of it — or 110% — is safe regardless of how the year goes.
This year’s 90% is an estimate. If you guess $40,000 and pay 90% of that, you have paid $36,000. If the year turns out to be $60,000, the rule wanted 90% of $60,000, which is $54,000. You are $18,000 short and the penalty applies.
So the current-year route is cheaper when your income is falling and dangerous when it is rising. The calculator shows both and tells you which one it used.
If your income is roughly flat, use last year’s number. It costs a little more and it cannot fail.
The $150,000 line, which catches people quietly
Form 1040-ES puts it plainly: if your adjusted gross income last year was more than $150,000 — or $75,000 if you file married filing separately — substitute 110% for 100%.
Nobody tells you when you cross it. The rule applies to last year’s AGI, so it is decided before the year even starts, and the first time most people notice is when a penalty appears on a return they thought was safe.
A freelancer whose good year pushed AGI to $160,000 owes 110% of that year’s tax across the following year’s four payments. On a $30,000 tax bill that is $33,000 rather than $30,000 — $750 more per quarter.
The calculator asks for AGI for exactly this reason.
The four dates, and why they are not quarters
| Due | Covers | Length |
|---|---|---|
| April 15, 2026 | January 1 to March 31 | 3 months |
| June 15, 2026 | April 1 to May 31 | 2 months |
| September 15, 2026 | June 1 to August 31 | 3 months |
| January 15, 2027 | September 1 to December 31 | 4 months |
The word quarterly is doing some damage here. The second period is two months and the fourth is four, so the June payment arrives sooner than a quarter after April, and the January one arrives long after the year has ended.
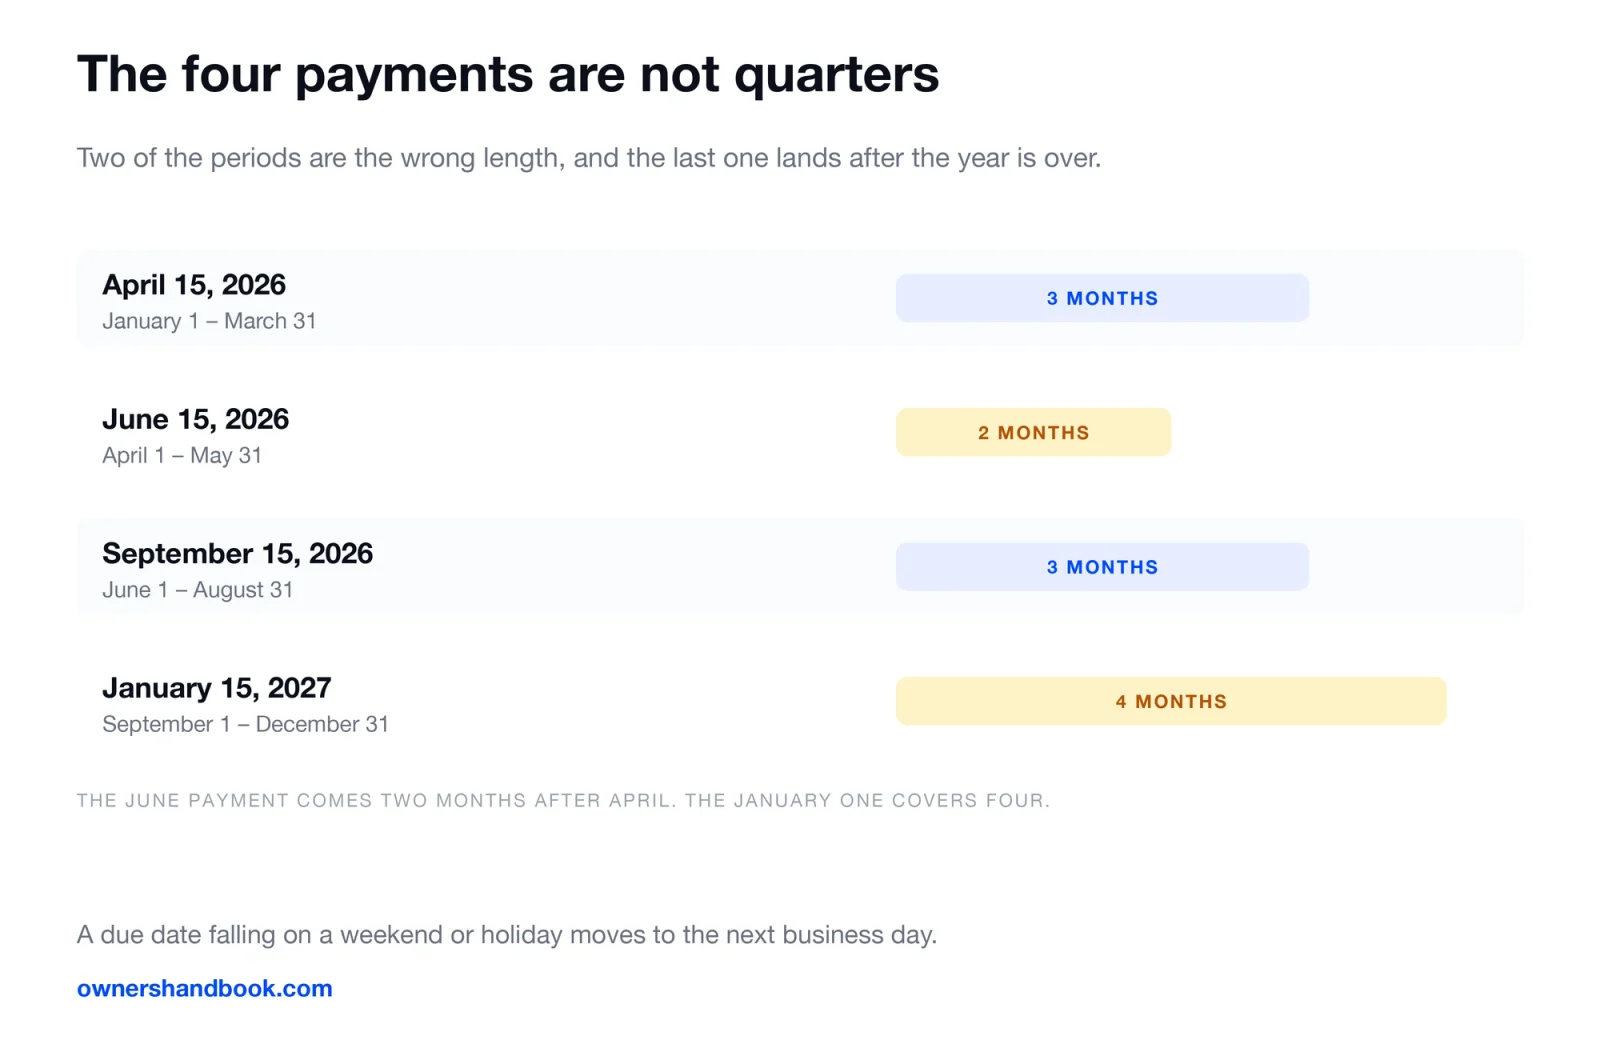
If a due date lands on a weekend or a holiday, the payment is on time on the next business day.
There is one more date worth knowing about. If you file your return and pay the balance in full by January 31, you can skip the January 15 payment entirely.
Where the numbers on the form come from
Last year’s total tax. On Form 1040 this is the line labelled total tax, near the bottom of page two. It is not the amount you owed in April — that figure is what was left after withholding and any estimates you already made, and it is usually much smaller.
Last year’s AGI. Also on page one of Form 1040, near the bottom. It is what decides 100% versus 110%.
This year’s expected tax. Leave it blank if you genuinely do not know. The calculator will fall back to last year’s safe harbor, which is the conservative answer.
Tax already withheld. From a W-2 job. This one has a useful property described below.
If you also have a job, withholding beats estimates
Withholding is treated as though it arrived evenly across the whole year, no matter when it actually came out of your paycheck. Estimated payments are credited on the day you make them.
So raising your W-4 withholding in November covers a shortfall from March. A November estimated payment does not.
That makes the W-4 the better instrument whenever you have wages to work with. File a new one with your employer and put the extra amount on line 4(c). The limit is arithmetic — your paycheck has to be big enough to absorb it — so someone earning $30,000 from a part-time job and $90,000 freelancing will cover part of the bill that way and pay the rest as estimates.
How to actually send it
Three ways, all free.
IRS Direct Pay takes a payment straight from a bank account with no account to create. Choose “Estimated Tax” and the year 2026.
EFTPS requires enrolling first, which takes several days because they mail you a PIN, but it keeps a record of every payment and lets you schedule them in advance.
Your IRS Online Account shows what you have already paid, which is the answer to the question people actually have in April.
Card payments work too and carry a processing fee of roughly 2%. Not worth it unless you are chasing card rewards that beat the fee.
What happens if you missed one
Send it as soon as you can rather than waiting for the next date. The interest stops accruing on the day the money arrives, so a late payment in July costs less than the same payment in September.
Then keep the remaining dates. A missed quarter does not invalidate the safe harbor for the others.
There is a form for this. Form 2210 calculates the underpayment penalty, and it includes an annualized income method that helps if your income arrived unevenly — a good fourth quarter after three quiet ones, for instance. Most tax software fills it in for you, and the IRS will also compute the penalty and bill you if you leave it alone.
Frequently asked questions
Do I have to pay quarterly in my first year of freelancing?
Usually yes, if you expect to owe $1,000 or more. But there is an exception worth knowing: if you owed no tax at all for the previous full twelve-month year and were a US citizen or resident throughout it, you are not required to make estimated payments this year no matter what you earn. The tax still arrives in April, so set the money aside anyway.
What if my income is wildly uneven?
The four payments do not have to be equal. Form 2210’s annualized income method lets you pay in proportion to when you actually earned, which helps freelancers whose year is back-loaded. It is more paperwork, and the safe harbor is simpler if you can afford the even split.
Can I just pay it all in April instead?
You can, and you will owe interest for the quarters you skipped. The penalty accrues per period, so paying in full at the end does not erase the earlier shortfalls.
Do I pay state estimates too?
Probably, if your state taxes income. The dates and rules vary — some states mirror the federal schedule, some do not. This calculator is federal only.
I overpaid. What happens?
It comes back as a refund, or you can apply it to next year’s first payment when you file. Overpaying is not penalised, it just costs you the use of the money in the meantime.
Does the calculator send my numbers anywhere?
No. It runs entirely in your browser. Nothing you type is transmitted or stored.
Sources
IRS, Form 1040-ES, Estimated Tax for Individuals
https://www.irs.gov/pub/irs-pdf/f1040es.pdf
IRS, Estimated Taxes
https://www.irs.gov/businesses/small-businesses-self-employed/estimated-taxes
IRS, Publication 505, Tax Withholding and Estimated Tax
https://www.irs.gov/pub/irs-pdf/p505.pdf
IRS, Form 2210, Underpayment of Estimated Tax
https://www.irs.gov/pub/irs-pdf/f2210.pdf
IRS, Direct Pay
https://www.irs.gov/payments/direct-pay
IRS, Electronic Federal Tax Payment System
https://www.irs.gov/payments/eftps-the-electronic-federal-tax-payment-system