Massachusetts Is 5% Until It Is 9%
Massachusetts taxes freelance profit at a flat 5%, and that is state income tax charged on top of everything you already owe the United States. On $90,000 of Massachusetts taxable income it comes to $4,500.
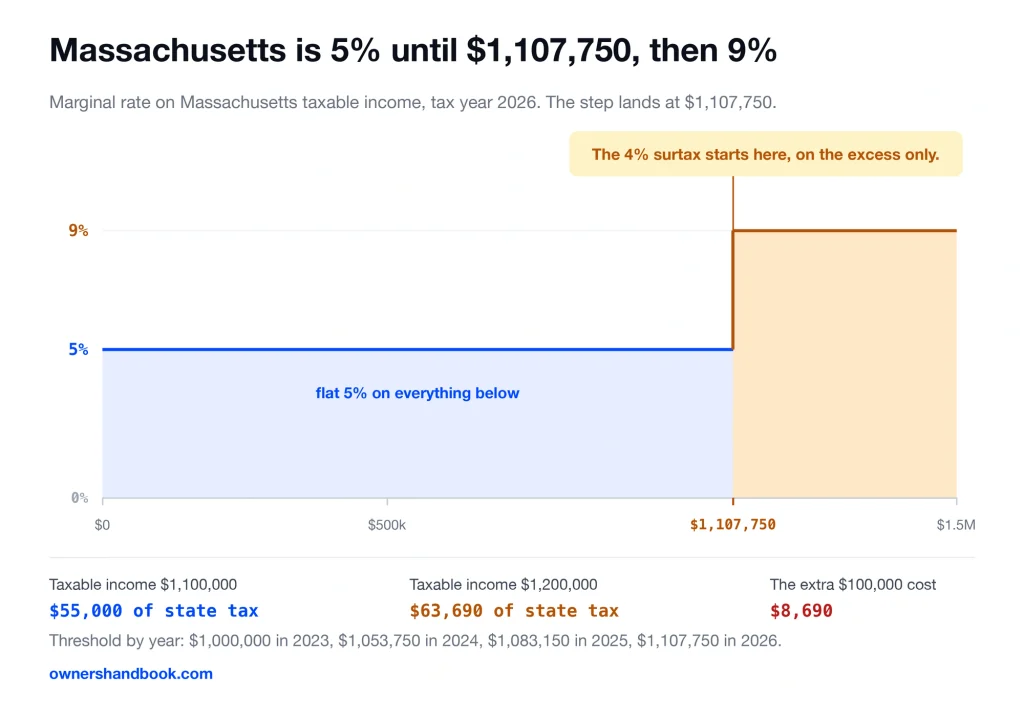
Then, above $1,107,750 of taxable income in 2026, a 4% surtax lands on the excess. From that dollar on, the state’s marginal rate is 9%.
One rate, and then a second one
Massachusetts has no brackets. Wages, business income, pensions and long-term capital gains all sit at a flat 5.00%, and that is the whole rate schedule for a normal freelance year.
A few categories break the pattern. Short-term capital gains are taxed at 8.5%, and long-term gains on collectibles at 12% after a 50% deduction.
None of this is self-employment tax. Social Security and Medicare are federal programs, so the 15.3% you calculate on Schedule SE does not repeat at the state level. Massachusetts charges income tax only.
The 4% surtax began with tax year 2023 and runs through M.G.L. c. 62, sections 4(d) and 5A. It applies to taxable income above a threshold that moves every year.
What the threshold does to the next dollar
Marginal rate is what the next dollar costs, not what the whole year costs. Below $1,107,750 yours is 5%. Above it, 9%.
Two freelancers, same city, same trade, one good year apart.
The one with $1,100,000 of Massachusetts taxable income owes $55,000 to the state. The one with $1,200,000 owes $63,690. That extra $100,000 of income cost $8,690.
It is not a cliff in the cruel sense. Crossing the line does not retroactively tax the first million at 9%, and only the excess gets surtaxed.
| Massachusetts taxable income | 5% tax | 4% surtax | Total state tax |
|---|---|---|---|
| $1,000,000 | $50,000 | $0 | $50,000 |
| $1,100,000 | $55,000 | $0 | $55,000 |
| $1,107,750 | $55,388 | $0 | $55,388 |
| $1,200,000 | $60,000 | $3,690 | $63,690 |
| $1,500,000 | $75,000 | $15,690 | $90,690 |
Read the last row carefully. Even at $1,500,000 the blended rate is 6.05%, because most of the income is still sitting in the 5% layer.
Last year’s threshold is the wrong number
It started at $1,000,000 for tax year 2023 and has been indexed for inflation every year since.
$1,053,750 for 2024. $1,083,150 for 2025. $1,107,750 for 2026.
Any calculator, article or spreadsheet still using a flat million is now off by more than $100,000 of income, which is $4,310 of tax. Pull the current figure from the Department of Revenue each January.
It is taxable income, not profit, and gains count
Massachusetts adds three buckets together to test you against the threshold.
Part A is short-term capital gains, gains on collectibles, and most interest and dividends. Part B is everything else, your Schedule C profit included. Part C is long-term capital gains.
Any bucket that comes out negative is treated as zero. A losing Part A year cannot be used to shelter a strong Part B one.
That is how a freelancer who never earns near a million in a normal year still pays the surtax. Sell the practice, sell a building, or land one enormous project, and that single year clears the line.
Gain on selling your own home counts too, to the extent it is taxable at all after the federal exclusion. The DOR says plainly there is no carve-out for a personal residence.
One more consequence. Once the surtax applies to you, you must file your return and make every payment electronically. Paper stops being an option.
Two federal deductions Massachusetts does not give you
This is the reason your state taxable income runs higher than your federal one, and almost nobody warns you about it.
Federally you deduct half your self-employment tax. Massachusetts does not allow that deduction. It substitutes a much smaller one for Social Security, Medicare and self-employment tax actually paid, capped at $2,000 per person.
The QBI deduction, the federal 20% write-off on qualified business income, is not allowed at all. TIR 18-14 explains the mechanism: the Tax Cuts and Jobs Act wrote section 199A out of the federal provision Massachusetts adopts.
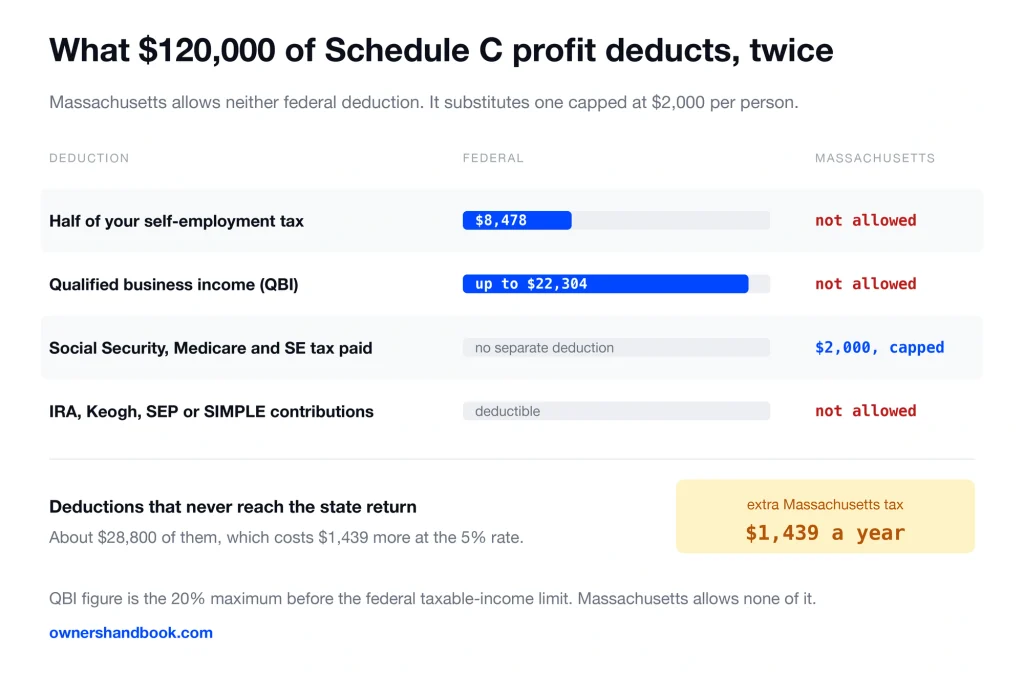
Take $120,000 of Schedule C profit. Self-employment tax on it is $16,955, and half of that, $8,478, comes off your federal income. Massachusetts hands you $2,000 and stops.
Add the QBI deduction, worth at most $22,304 on that profit, and roughly $28,800 of deductions never reach the state return.
At 5%, that gap costs about $1,439 in extra Massachusetts tax every year, on a return where nothing looks unusual.
| On $120,000 of Schedule C profit | Federal | Massachusetts |
|---|---|---|
| Half of self-employment tax | $8,478 | not allowed |
| Qualified business income (QBI) | up to $22,304 | not allowed |
| Social Security, Medicare and self-employment tax paid | — | $2,000, capped |
| IRA, Keogh, SEP or SIMPLE contributions | deductible | not allowed |
| Net operating loss carried to another year | allowed | not allowed |
Massachusetts does follow the federal home office safe harbor, at $5 per square foot up to 300 square feet and a $1,500 maximum.
Form 1-ES and the $400 line
The threshold that forces you into estimated payments is low. You must make them if you expect to owe more than $400 on income that is not subject to withholding.
At a 5% rate, $400 of tax is $8,000 of taxable income. Almost any freelancer with one real client clears it.
The form is Form 1-ES and the portal is MassTaxConnect. None of it connects to your federal quarterly estimated taxes, which run on their own form, their own portal, and their own money.
The 2026 Form 1-ES sets four equal installments: April 15, 2026, June 15, 2026, September 15, 2026 and January 15, 2027. No uneven split, unlike California.
One wrinkle. The DOR’s estimated payments web page lists June 16 for the second installment while the DOR’s own Form 1-ES says June 15. Pay on the 15th and the disagreement cannot reach you.
The safe harbor is 100%, with no step-up
Massachusetts wants 80% of the year’s tax paid in during the year, rather than the 90% the IRS asks for.
A safe harbor is the amount you can pay and be immune from an underpayment penalty no matter what the year turns out to be. Massachusetts grants one, and it is unusually generous.
Form M-2210 waives the penalty if your estimated payments and withholding equal the tax shown on your prior-year return, divided across the four due dates. That return has to cover a full 12 months.
Now notice what is absent. There is no 110% version for high earners, the way the IRS and California both impose one.
That matters most in exactly the year you would expect it to. Sell the business in March, pay four installments totaling last year’s ordinary tax, and the surtax settles up in April with no penalty riding on it.
There is also a flat exception when your tax due after credits and withholding is $400 or less.
No city or town adds anything
Massachusetts has no local income tax. Not Boston, not Cambridge, not anywhere in the Commonwealth.
The DOR publishes one table listing every tax rate in Massachusetts, local options included. Those options cover hotel rooms, restaurant meals, marijuana and a Boston car rental surcharge. Income is not among them.
So the full state answer for a Massachusetts freelancer is 5%, or 9% above the threshold, and nothing underneath it. Set against Philadelphia or New York City, that is a genuine simplification.
What the 5% does not settle is which state gets the money when you live in one place and work in another. The general state tax guide covers that, along with the credit for taxes paid to another state.
Frequently asked questions
Do I pay self-employment tax to Massachusetts?
No. Social Security and Medicare are federal, so Schedule SE goes only to the IRS. Massachusetts charges income tax, and the two are separate calculations.
My taxable income was $1,120,000. Is all of it taxed at 9%?
No. Only the $12,250 above the 2026 threshold of $1,107,750 gets the extra 4%, which is $490. The first $1,107,750 stays at 5%.
Does Massachusetts follow the federal QBI deduction?
No. Per TIR 18-14 the section 199A deduction is not allowed under Massachusetts law, so your state taxable income runs higher than your federal taxable income.
I sold my business this year. Does that count toward the surtax threshold?
Yes. Long-term capital gains are Part C income, and Part C is added to Parts A and B when the state tests you against the threshold.
Do I have to make estimated payments if I only freelance on the side?
If you expect to owe more than $400 on income not subject to withholding, yes. If you also hold a Massachusetts W-2 job, raising withholding there can cover it instead.
What happens if I underpay a Massachusetts installment?
An additional charge accrues on the underpayment for the period it was short. You settle it on Form M-2210 with your annual return, where you also claim any exception.
Sources
Massachusetts Department of Revenue, Massachusetts Tax Rates
https://www.mass.gov/info-details/massachusetts-tax-rates
Massachusetts Department of Revenue, Massachusetts 4% Surtax on Taxable Income
https://www.mass.gov/info-details/4-surtax-on-taxable-income-over-1000000
Massachusetts Department of Revenue, DOR Estimated Tax Payments
https://www.mass.gov/info-details/dor-estimated-tax-payments
Massachusetts Department of Revenue, 2026 Form 1-ES, Massachusetts Estimated Income Tax
Massachusetts Department of Revenue, 2025 Form M-2210, Underpayment of Massachusetts Estimated Income Tax
Massachusetts Department of Revenue, Massachusetts Business and Professional Income, Schedule C Reporting
https://www.mass.gov/info-details/learn-about-business-and-professional-income
Massachusetts Department of Revenue, TIR 18-14, Impact of Selected Provisions of the Federal Tax Cuts and Jobs Act on Massachusetts Personal Income Tax under Chapter 62
Massachusetts Department of Revenue, 2025 Form 1 Instructions
https://www.mass.gov/doc/2025-form-1-instructions/download
IRS, Self-Employment Tax
IRS, Estimated Taxes
https://www.irs.gov/businesses/small-businesses-self-employed/estimated-taxes