Do You Need a Receipt for That? The $75 Rule
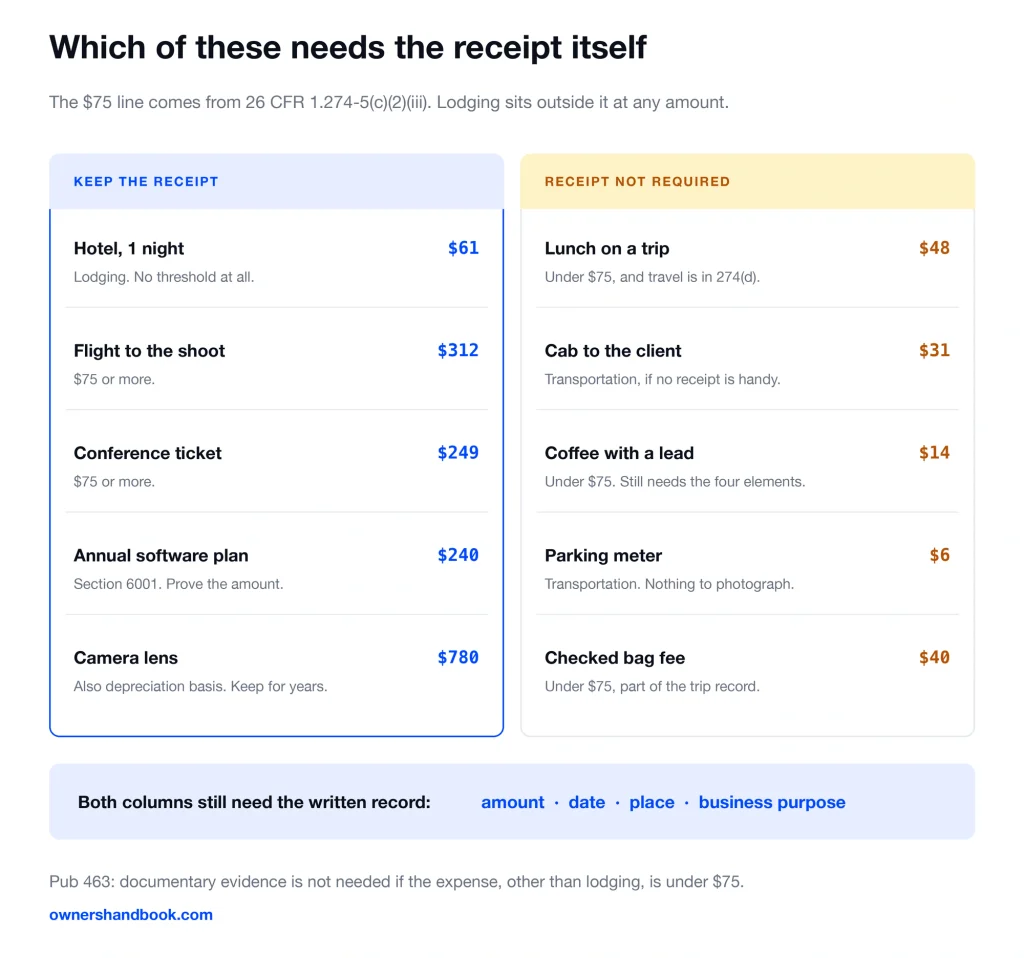
Keep the receipt for every lodging bill, and for every expense of $75 or more. That threshold is written into the regulations, at 26 CFR 1.274-5(c)(2)(iii).
Under $75, the receipt itself stops being required. The record does not. You still write down the amount, the date, the place, and the business reason.
Most people hear the first half and stop. That gap is what this page is about.
The $75 line, and where it is written
The rule lives in the regulation under section 274(d). Substantiation — proving a deduction was real, which is your job, not your preparer’s.
It requires documentary evidence, “such as receipts, paid bills, or similar evidence,” for two things. Any expenditure for lodging while traveling away from home. And any other expenditure of $75 or more.
A third clause most summaries drop: for transportation charges, documentary evidence is not required if it is not readily available.
Publication 463 puts it the other way. Documentary evidence is not needed if “your expense, other than lodging, is less than $75.”
Lodging has no floor. A $61 motel room on a two-day shoot needs the folio, same as a $400 hotel night.
The threshold is per expenditure, not per day or per trip. Three $40 lunches on one trip are three separate expenditures, each under it.
It is not a rule for every expense
Here is the part that gets repeated wrong. The $75 threshold sits inside section 274(d), which covers a specific list.
Travel away from home, including meals and lodging on the trip. Gifts. Listed property, which is the category your car sits in.
A $52 software subscription is not on that list. Neither is a $60 box of business cards.
Those run on section 6001 instead: keep records sufficient to establish the amounts shown on your return. No dollar floor appears there at all.
So the relief lands on the categories examined hardest, and nowhere else. Keep everything, then know which ones you are allowed to be missing.
| What you bought | Receipt required | Which rule |
|---|---|---|
| Hotel, $61 for one night | Yes, always | Lodging has no threshold |
| Flight, $312 | Yes | $75 or more |
| Lunch on a business trip, $48 | No | Under $75 — record still required |
| Subway fare, $2.90 | No | Transportation, receipt not readily available |
| Laptop stand, $54 | No stated threshold | Section 6001, prove the amount |
| Annual software, $240 | Keep it | Section 6001, and it is over $75 |
What a record actually has to say
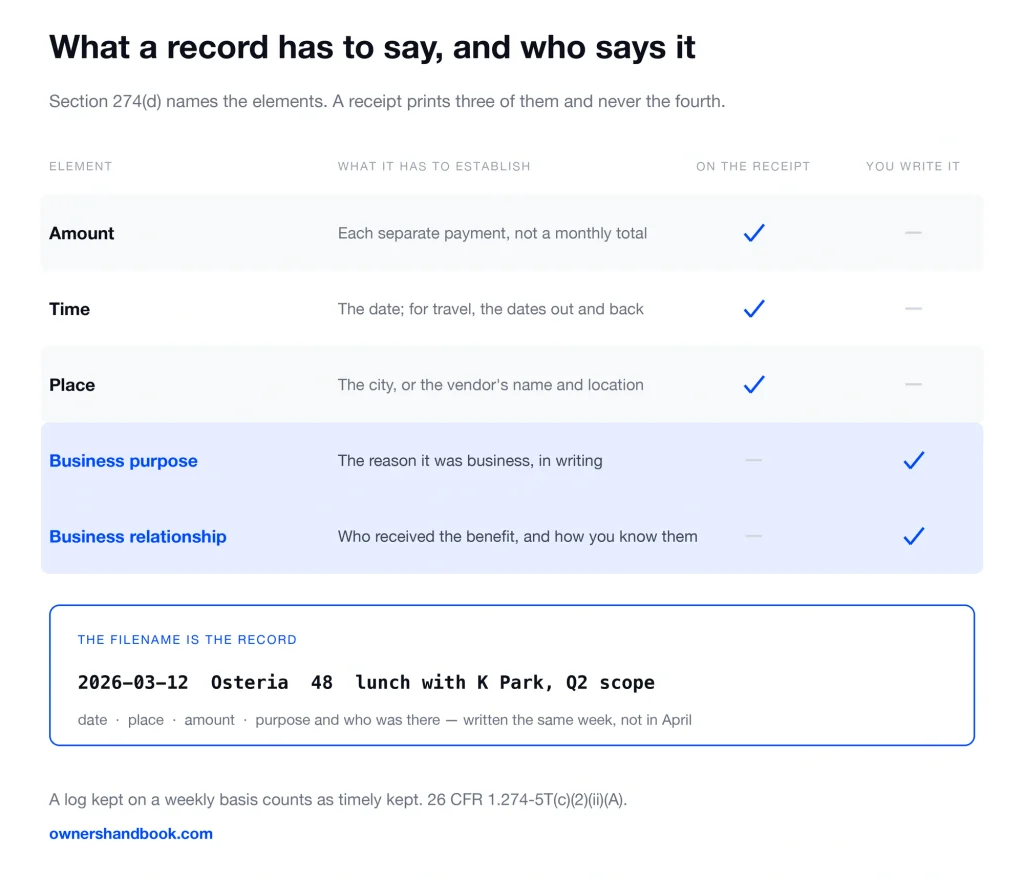
Section 274(d) names four elements, plus a fifth when somebody else received the benefit.
Amount. Time. Place. Business purpose. And the business relationship to you of the person receiving the benefit — the element that matters for gifts and for a client meal.
A receipt hands you three of them. The register slip shows $48, March 12, and the name of the restaurant.
It cannot show the fourth. No merchant prints why.
A written statement of business purpose is generally required, in the regulation’s words. The one exception is narrow: where the purpose is evident from surrounding circumstances.
Timing is its own requirement. Record each element at or near the time of the expense, while you have “full present knowledge” of it.
Not the same day, though. A log kept weekly counts as timely kept. Friday afternoon is inside the rule. April is not.
Publication 463 is blunt about why. “A timely kept record has more value than a statement prepared later when there is generally a lack of accurate recall.”
| Element | What it means | Who supplies it |
|---|---|---|
| Amount | Each separate payment, not a monthly total | The receipt |
| Time | The date; for travel, dates out and back | The receipt |
| Place | The city, or the vendor’s name and location | The receipt |
| Business purpose | The reason, written down | You, that week |
| Business relationship | Who got the benefit and how you know them | You |
Your card statement is not a receipt
The most expensive misunderstanding in freelance bookkeeping. The regulation answers it directly.
A cancelled check plus a bill from the payee ordinarily establishes the cost. A cancelled check alone “would not by itself support a business expenditure without other evidence showing that the check was used for a certain business purpose.”
A card statement is the same animal. It proves $340 left your account and landed at an electronics store.
It does not prove the thing in the bag was a monitor for your desk rather than a television.
The IRS does list card statements among acceptable supporting documents. That same page also asks for a description of the item purchased. One piece of the file, never the whole file.
A photo of the receipt is a record
You do not need the paper. The IRS has accepted imaged records since Revenue Procedure 97-22, issued in 1997 and still the governing guidance.
It covers this exact case: a system that images hardcopy records onto electronic storage. Those are records under section 6001.
Section 7 permits destroying the original paper, once you have tested that your system reproduces compliant copies.
The conditions are ordinary. Accurate transfer, an index you can search, and the ability to produce a legible hard copy on request. “All requirements that apply to hard copy books and records also apply to electronic records.”
So the phone photo qualifies. A camera roll of 900 unlabeled photos technically qualifies and practically does not — retrieval is part of the requirement.
Where documentation gets tested hardest
Four categories produce most of the argument, and three carry their own statutory rules. For base rates, see the audit article.
Vehicle. Your car is listed property, so the strict rules cover every mile. Date, miles, destination, business reason, plus odometer readings at both ends of the year.
The standard mileage rate is worth nothing without that log. Nine thousand business miles is roughly $6,700 of deduction resting on a spreadsheet.
Travel. Dates out and back, days on business, the destination, the business reason. Lodging receipted every time, any amount.
Meals. Since 2018 the statute’s strict list reads travel, gifts and listed property, so a lunch in your own city is not technically a traveling expense. Read that as a technicality, not permission.
Write down who was at the table and what it was about. That line costs ten seconds.
Home office. Different evidence entirely. Square footage of the room and of the whole home, plus, under the actual expense method, the bills behind the percentage.
When the receipt is gone
Losing one receipt is survivable. Losing the category is not.
Records destroyed by “fire, flood, earthquake, or other casualty” — circumstances beyond your control — can be substantiated by reasonable reconstruction. That is a right, written in.
A receipt that went through the wash is not a casualty. There the fallback is the statute’s second route: your own statement, plus corroborating evidence.
The corroboration is tiered. For amount, time, place or date it must be direct or documentary. For business purpose or relationship it may be circumstantial.
The Cohan rule is what people reach for here. Cohan v. Commissioner, 39 F.2d 540 (2d Cir. 1930), let a court approximate a deduction clearly incurred but not proved to the dollar.
It does not survive contact with section 274(d). The regulation says so in one line: “This limitation supersedes the doctrine found in Cohan v. Commissioner.”
So approximation might still rescue a lost $90 supplies invoice. It will not rescue travel, gifts, or your car. There, no record means no deduction.
A filing system you can run in ten minutes a week
One business account and one business card. The statement then works as an index of what to go find, not a pile to sort.
One folder per tax year, twelve subfolders by month. Name every file the way you would search for it: date, vendor, amount, purpose.
2026-03-12 Osteria 48 lunch with K Park Q2 scope
That filename carries the element the receipt left out, and it sorts onto a Schedule C line without a second pass.
Capture the purpose while you are still standing there. Ten seconds now beats an hour of reconstruction in April that produces weaker evidence.
Disclosure: I run this site and also run Mozey, at mozey.co, whose receipt scanning reads a photographed receipt, categorizes it, and rolls it into a Schedule C-shaped summary. Described at /mozey-what-it-is/.
How long all of it has to survive is a separate question — three years usually, six in one case, indefinitely if you never filed. The record-keeping article covers it.
Frequently asked questions
Do I really not need a receipt for a $60 client dinner?
Not the receipt. Publication 463 exempts expenses other than lodging under $75. You still need a written record of amount, date, place, business purpose, and who was there.
Does the $75 rule cover software, supplies and equipment?
No. It sits in the regulation under section 274(d), covering travel, gifts and listed property such as your car. Everything else runs on section 6001, which sets no dollar floor and still expects proof.
I lost the receipt. Is my bank statement enough?
Usually not alone. A statement shows amount and payee, not what was bought or why it was business. The regulation says a payment record by itself does not support a deduction without other evidence of purpose.
Can I throw away the paper after I photograph it?
Revenue Procedure 97-22 permits it once you have tested that your system reproduces legible, complete copies. A searchable folder of named files meets that. A raw camera roll does not.
Do I have to write a business purpose on every single receipt?
Generally yes, in writing. The regulation waives it only where purpose is evident from circumstances, such as a driver on an established delivery route. Assume you are not that case.
I never kept a mileage log. Can I write one now from my calendar?
You can reconstruct, and something beats nothing. But section 274(d) blocks approximation for vehicles, and a record built from memory is the first thing to fall apart under examination.
Sources
IRS, Publication 463, Travel, Gift, and Car Expenses
https://www.irs.gov/publications/p463
eCFR, 26 CFR 1.274-5, Substantiation requirements
https://www.ecfr.gov/current/title-26/section-1.274-5
eCFR, 26 CFR 1.274-5T, Substantiation requirements (temporary)
https://www.ecfr.gov/current/title-26/section-1.274-5T
Legal Information Institute, 26 U.S.C. 274, Disallowance of certain entertainment, etc., expenses
https://www.law.cornell.edu/uscode/text/26/274
Legal Information Institute, 26 U.S.C. 6001, Notice or regulations requiring records
https://www.law.cornell.edu/uscode/text/26/6001
IRS, What kind of records should I keep
https://www.irs.gov/businesses/small-businesses-self-employed/what-kind-of-records-should-i-keep
IRS, Burden of proof
https://www.irs.gov/businesses/small-businesses-self-employed/burden-of-proof
IRS, Recordkeeping
https://www.irs.gov/businesses/small-businesses-self-employed/recordkeeping
IRS, Revenue Procedure 97-22
https://www.irs.gov/pub/irs-tege/rp-97-22.pdf
IRS, Publication 583, Starting a Business and Keeping Records