S Corp and You Never Ran Payroll: What Happens Now
You elected S corporation status, took money out of the business all year, and never ran a payroll. Nothing has gone wrong yet — nobody has sent you anything. But the return that reports the year is due in March, and what you put on it decides how this ends.
Here is what the rule actually says, what the IRS can do about it, and what is still fixable.
The rule, in the IRS’s own words
There is no ambiguity in the standard itself:
S corporations must pay reasonable compensation to a shareholder-employee in return for services that the employee provides to the corporation before non-wage distributions may be made to the shareholder-employee.
Read the order in that sentence. Wages come before distributions, not instead of them and not after.
That is the whole election. An S corporation saves you payroll tax on the distribution half of your income precisely because the salary half was already taxed. Take everything as a distribution and the arrangement has no salary half at all.
What the IRS can do about it
Also from the IRS, directly:
The IRS has the authority to reclassify payments made to shareholders from non-wage distributions (which are not subject to employment taxes) to wages (which are subject to employment taxes).
Reclassification is the mechanism. They do not fine you for failing to run payroll — they decide that what you took was wages, and then everything that should have followed wages follows.
| What follows a reclassification | Why |
|---|---|
| Social Security and Medicare tax on the reclassified amount | 15.3% combined, employer and employee halves |
| Failure to deposit penalties | The tax was due on a schedule you did not follow |
| Failure to file penalties on payroll returns | Forms 941 and W-2 that were never filed |
| Interest | Running from each original due date |
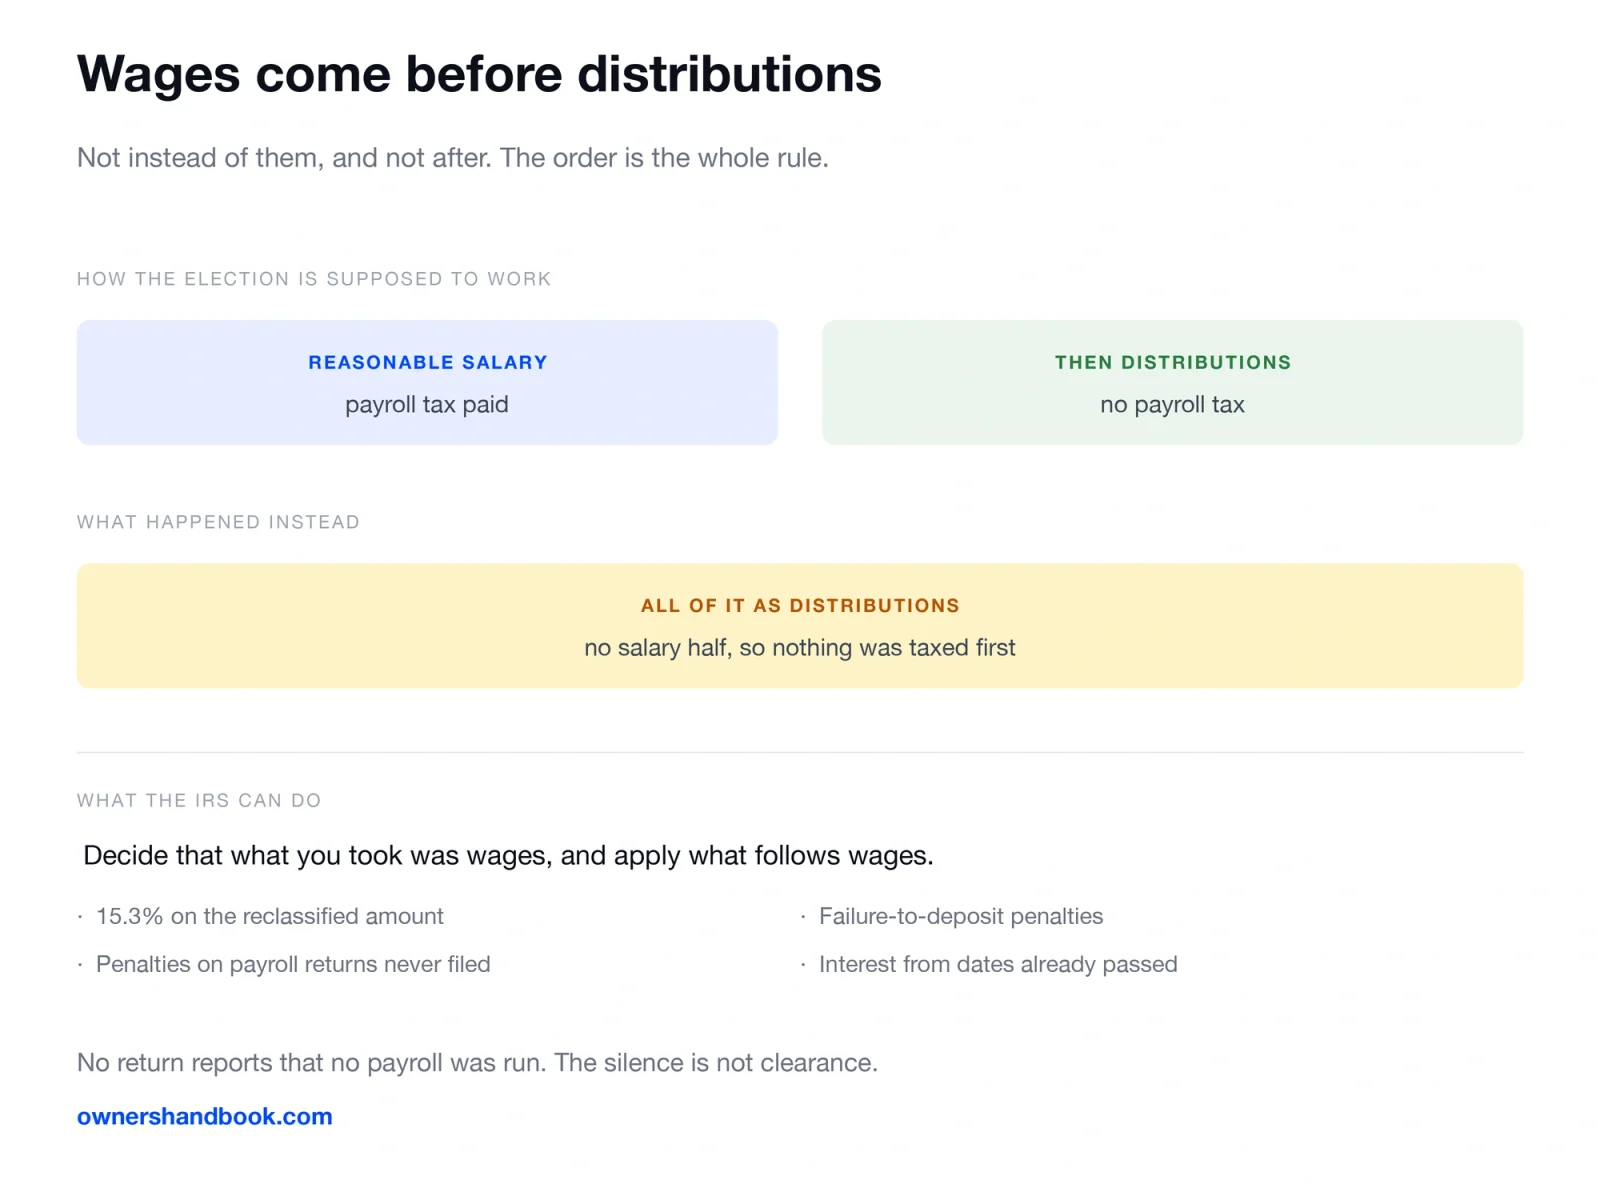
The exposure is not the 15.3% alone. It is the 15.3% plus the penalties for the filings that should have accompanied it, plus interest from dates that have already passed.
Why nothing has happened yet
This is the part that makes people relax when they should not.
There is no return that reports “no payroll was run.” Payroll returns are filed by employers who have payroll. Having none means filing nothing, which generates no notice and no letter.
The thing that surfaces it is your Form 1120-S, which asks for officer compensation. An S corporation reporting meaningful profit, distributions to a single shareholder, and zero officer compensation is a visible pattern — and it is visible on a document you file voluntarily.
So the silence is not clearance. It is just the absence of anything that would break it.
What the IRS weighs when it decides what reasonable means
There is no formula and no percentage in the law. The IRS publishes a list of factors instead:
| Factor | What it looks at |
|---|---|
| Training and experience | What your skills command |
| Duties and responsibilities | What you actually do in the business |
| Time and effort devoted | Full time, or a few hours a week |
| Payments to non-shareholder employees | What you pay others for similar work |
| What comparable businesses pay | The market rate for the role |
| Dividend history | The pattern of distributions over time |
| Compensation agreements | Anything you wrote down |
The rules of thumb you find online — a fixed percentage, a 60/40 split — are not in this list. They are shorthand, and the absence of any percentage from the IRS’s own factors is worth noticing.
Our guide to whether the S corp election is worth it works through what a defensible number looks like for a freelancer.
If the year is not over yet
You have more room than you think, and the size of the room shrinks every week.
Run a payroll before December 31. A salary paid in December is still a salary paid during the year. It is not ideal — it compresses a year of withholding into one period — but a late salary is enormously better than no salary.
Use a payroll service rather than doing it by hand. They will file the quarterly returns, make the deposits, and produce a W-2. Doing it manually means understanding deposit schedules and penalty rules you have never had to learn.
Write down how you picked the number while the reasoning is fresh. Comparable job postings, your hours, what you would pay someone else to do the work. A contemporaneous note is worth far more than a reconstruction.
Do not simply reduce what you already took. Money already distributed is a fact. The question is what portion of it gets characterised as wages, not whether you can un-take it.
If the year is already over
The room is smaller but it is not zero, and the deadlines matter.
| What | When |
|---|---|
| Form 1120-S | March 15, or the next business day |
| Form 7004 extension | Same date, automatic six months |
| W-2 to you and to the SSA | The end of January |
| Form 941 for the fourth quarter | The end of January |
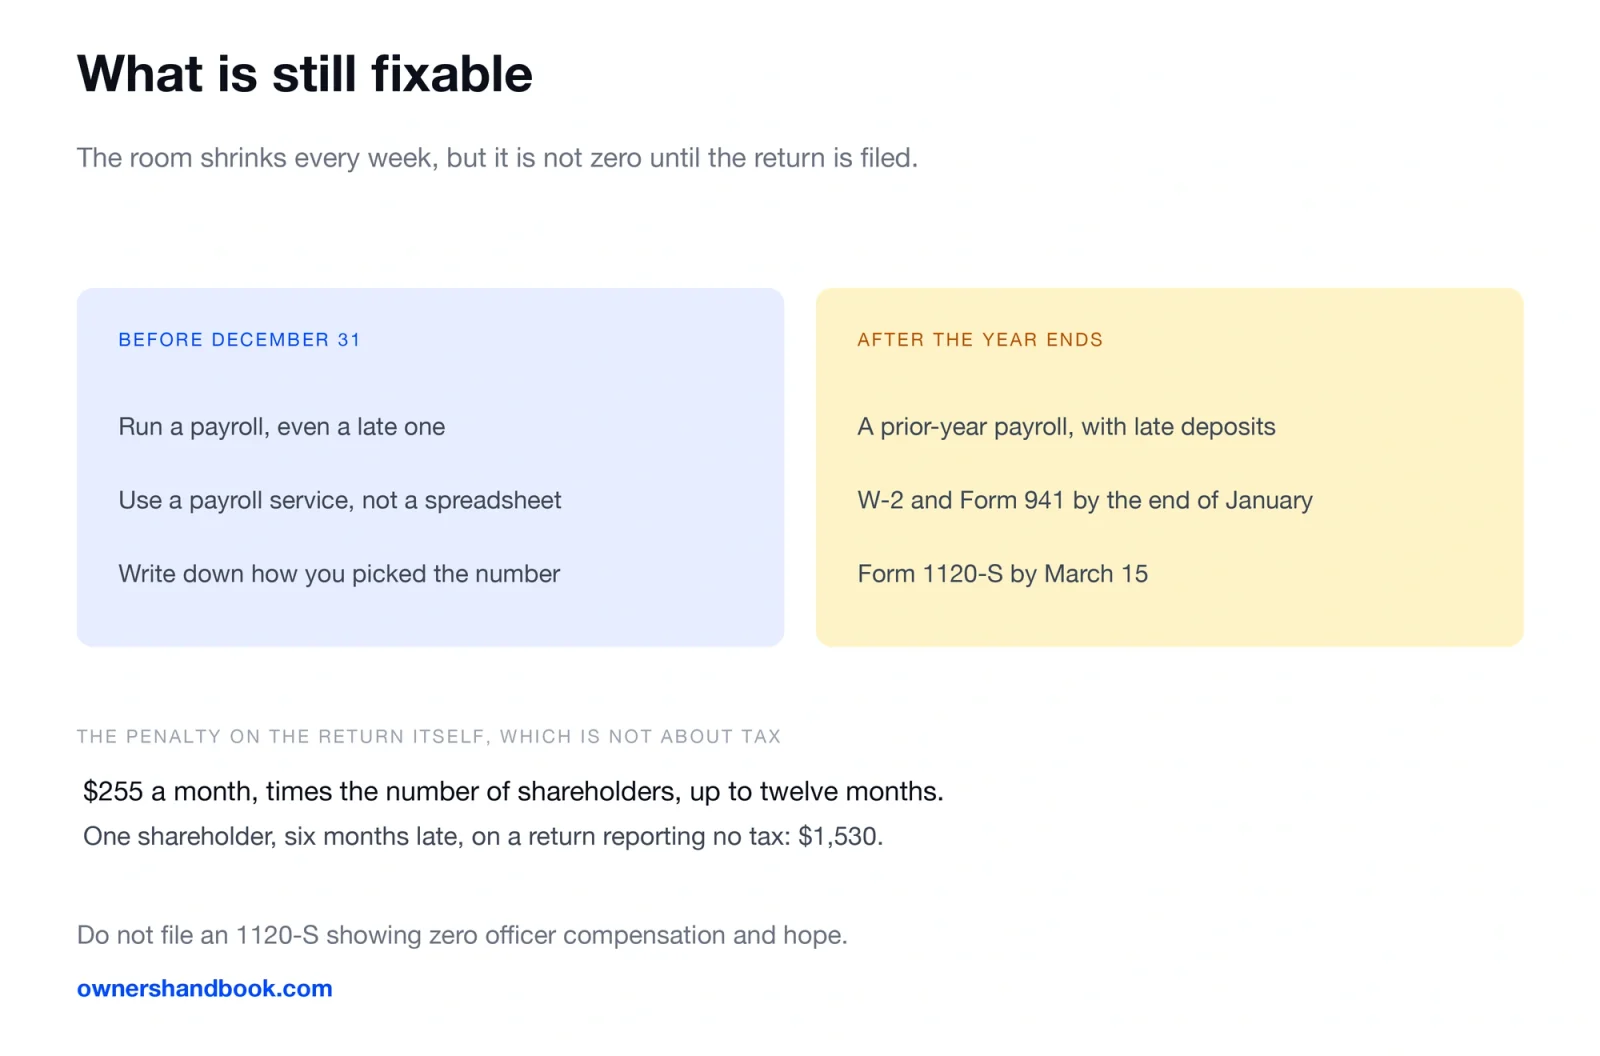
A payroll service can often still run a prior-year payroll in January, with late deposits and the penalties attached to them. That is a real cost, but it produces a W-2 and a filed set of returns, which is a different position from having neither.
What you should not do is file an 1120-S showing zero officer compensation and hope. That is the document the pattern shows up on.
The penalty on the return itself, which surprises people
Separate from anything about wages, the S corporation return carries its own penalty — and it is not based on tax owed.
For returns on which no tax is due, the penalty is $255 for each month or part of a month the return is late, up to 12 months, multiplied by the number of shareholders.
A single-shareholder S corporation six months late owes $1,530 on a return that reports no tax at all. That is why people forget to file it — the entity owes nothing, so it feels optional. It is not.
There is also a $340 penalty for each Schedule K-1 not furnished, rising to $680 where the failure is treated as intentional.
If you elected and then did nothing at all
Worth naming, because it happens: some people file Form 2553, receive the acceptance letter, and then continue exactly as before — no payroll, no separate return, everything on Schedule C.
That does not undo the election. The corporation exists for tax purposes from the effective date, and its returns are due whether or not anyone filed them.
Revoking an S election is its own procedure with its own timing, and it is not accomplished by ignoring it.
What this costs against what it saved
Run the arithmetic honestly before deciding how worried to be.
The election saves payroll tax on the distribution portion. If you never established a salary portion, the saving you booked was never the one the election offers — it was the saving from not paying payroll tax on any of it, which is not a thing the rule permits.
For many freelancers the honest conclusion is that the election was premature. Our comparison of LLC and sole proprietor and the numbers in the S corp election post cover the profit level where it starts to pay.
Frequently asked questions
Is there a percentage I can use, like 60/40?
Not in any IRS guidance. The agency publishes factors, not a formula, and no percentage appears among them. A percentage can be a starting point for your own analysis, but it is not a rule you can point to.
Can I pay myself one lump salary in December?
Yes, and it is far better than nothing. Deposit timing and the compressed withholding create some cost, but you end the year with a salary, a W-2, and filed payroll returns.
What if the business barely made anything?
Reasonable compensation is tied to the services you provided and what the business could pay. A year with almost no profit supports a small salary. A year with meaningful profit and zero salary is the pattern that draws attention.
Will the IRS definitely catch this?
Nobody can tell you that. What is knowable is that the exposure grows with time, because penalties and interest run from dates that have already passed, and that the pattern appears on a return you file yourself.
Can I just go back to being a sole proprietor?
Revoking an S election is a separate procedure with its own timing, and the corporation’s obligations continue until it takes effect. Ignoring the election does not end it.
Do I need payroll if I took no money out at all?
If you provided services and took nothing — no distributions, no draws — there is nothing to reclassify. The rule is triggered by distributions made without wages.
Sources
IRS, S corporation compensation and medical insurance issues
IRS, Instructions for Form 1120-S
https://www.irs.gov/pub/irs-pdf/i1120s.pdf
IRS, Instructions for Form 2553
https://www.irs.gov/instructions/i2553
IRS, Publication 509, Tax Calendars
https://www.irs.gov/pub/irs-pdf/p509.pdf
IRS, Employment taxes
https://www.irs.gov/businesses/small-businesses-self-employed/employment-taxes