Home Daycare Taxes: You Do Not Need Exclusive Use
Almost every article about the home office deduction tells you the space must be used exclusively for business. A bedroom that doubles as a guest room is out. A kitchen table is out.
If you run a daycare in your home, that rule does not apply to you.
You are the one carve-out written into the statute itself. Your playroom can be your children’s playroom in the evening. Your kitchen can be a kitchen. You still deduct — you just measure it differently, with a clock as well as a tape measure.
The exception is in the statute, not in guidance
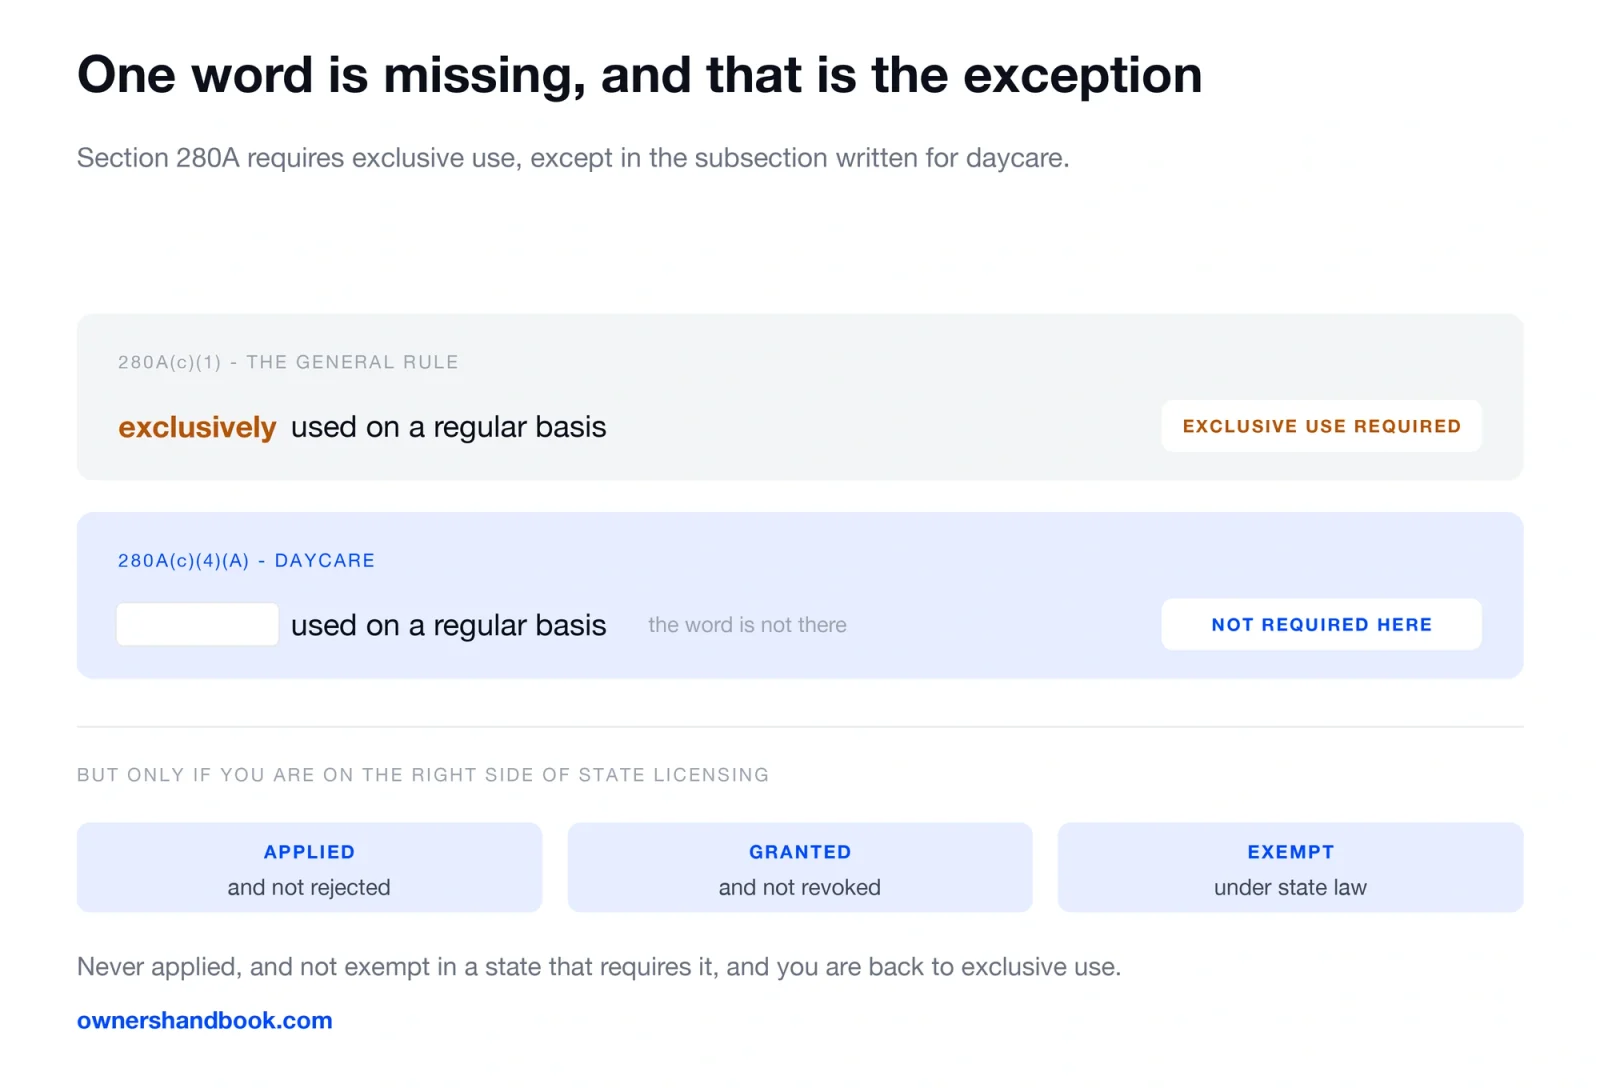
Section 280A is the law that restricts deductions for business use of a home. Subsection (c)(1) permits a deduction for a portion of the dwelling that is exclusively used on a regular basis for business. That word “exclusively” is the one that disqualifies most people.
Now read subsection (c)(4)(A), which covers daycare:
Subsection (a) shall not apply to any item to the extent that such item is allocable to the use of any portion of the dwelling unit on a regular basis in the taxpayer’s trade or business of providing day care for children, for individuals who have attained age 65, or for individuals who are physically or mentally incapable of caring for themselves.
Compare the two sentences. The daycare provision says on a regular basis. It does not say exclusively. The omission is the entire point — it is the only place in section 280A where that requirement is lifted.
Note also who is covered. It is not only children. Adult day care for people aged 65 or over, and care for people physically or mentally incapable of caring for themselves, sit in the same sentence and get the same treatment.
Our own guide to the home office deduction tells you that you need exclusive use. For most readers that is correct. For you it is not, and you should read that post as describing the general rule to which you are the stated exception.
The licensing condition, which is stricter than people expect
The exception is conditional. You do not get it merely by running a daycare — you get it by running a daycare that is on the right side of your state’s licensing system.
The statute, at (c)(4)(B), applies the exception only if the owner or operator:
(i) has applied for (and such application has not been rejected), (ii) has been granted (and such granting has not been revoked), or (iii) is exempt from having, a license, certification, registration, or approval as a day care center or as a family or group day care home under the provisions of any applicable State law.
Three doors, and you need one of them.
| Your licensing status | Does the exception apply |
|---|---|
| Licensed, registered or certified by the state | Yes |
| Applied, decision still pending | Yes — a pending application qualifies |
| Application was rejected | No |
| Licence was granted then revoked | No, from the revocation |
| Exempt from licensing under state law | Yes |
| Never applied, and not exempt | No |
The pending-application case is the one worth dwelling on, because it is generous in a way tax law rarely is. If you have filed your application and the state has not rejected it, you qualify for that period. You do not have to wait for the certificate.
The reverse is equally sharp. Operating without a licence in a state that requires one, having never applied, fails the condition — which puts you back to needing exclusive use, which you almost certainly do not have.
Publication 587 states the same condition in plainer words:
You must have applied for, been granted, or be exempt from having a license, certification, registration, or approval as a daycare center or as a family or group daycare home under state law.
How the time ratio works
Here is the trade. You are relieved of exclusive use, and in exchange you must reduce your deduction by the fraction of time the space is actually used for daycare.
The statute at (c)(4)(C) sets the formula:
the amount of the expenses attributable to that portion shall not exceed an amount which bears the same ratio to the total amount of the items allocable to such portion as the number of hours the portion is used for such purposes bears to the number of hours the portion is available for use.
Hours used, over hours available. Publication 587 implements “available” as every hour of the year — 24 × 365, or 8,760 hours.
So you compute two percentages and multiply them.
| Step | What you measure |
|---|---|
| Space percentage | Square feet used for daycare ÷ total square feet of the home |
| Time percentage | Hours used for daycare ÷ 8,760 hours in the year |
| Business-use percentage | Space percentage × time percentage |
Publication 587’s own example runs it through. A provider uses 1,600 of 3,200 square feet, which is 50%. The space is used for daycare 12 hours a day, 5 days a week, for 50 weeks — 3,000 hours. Against 8,760 hours that is 34.25%. Multiply: 50% × 34.25% = 17.12% of indirect household expenses.
A worked example of your own
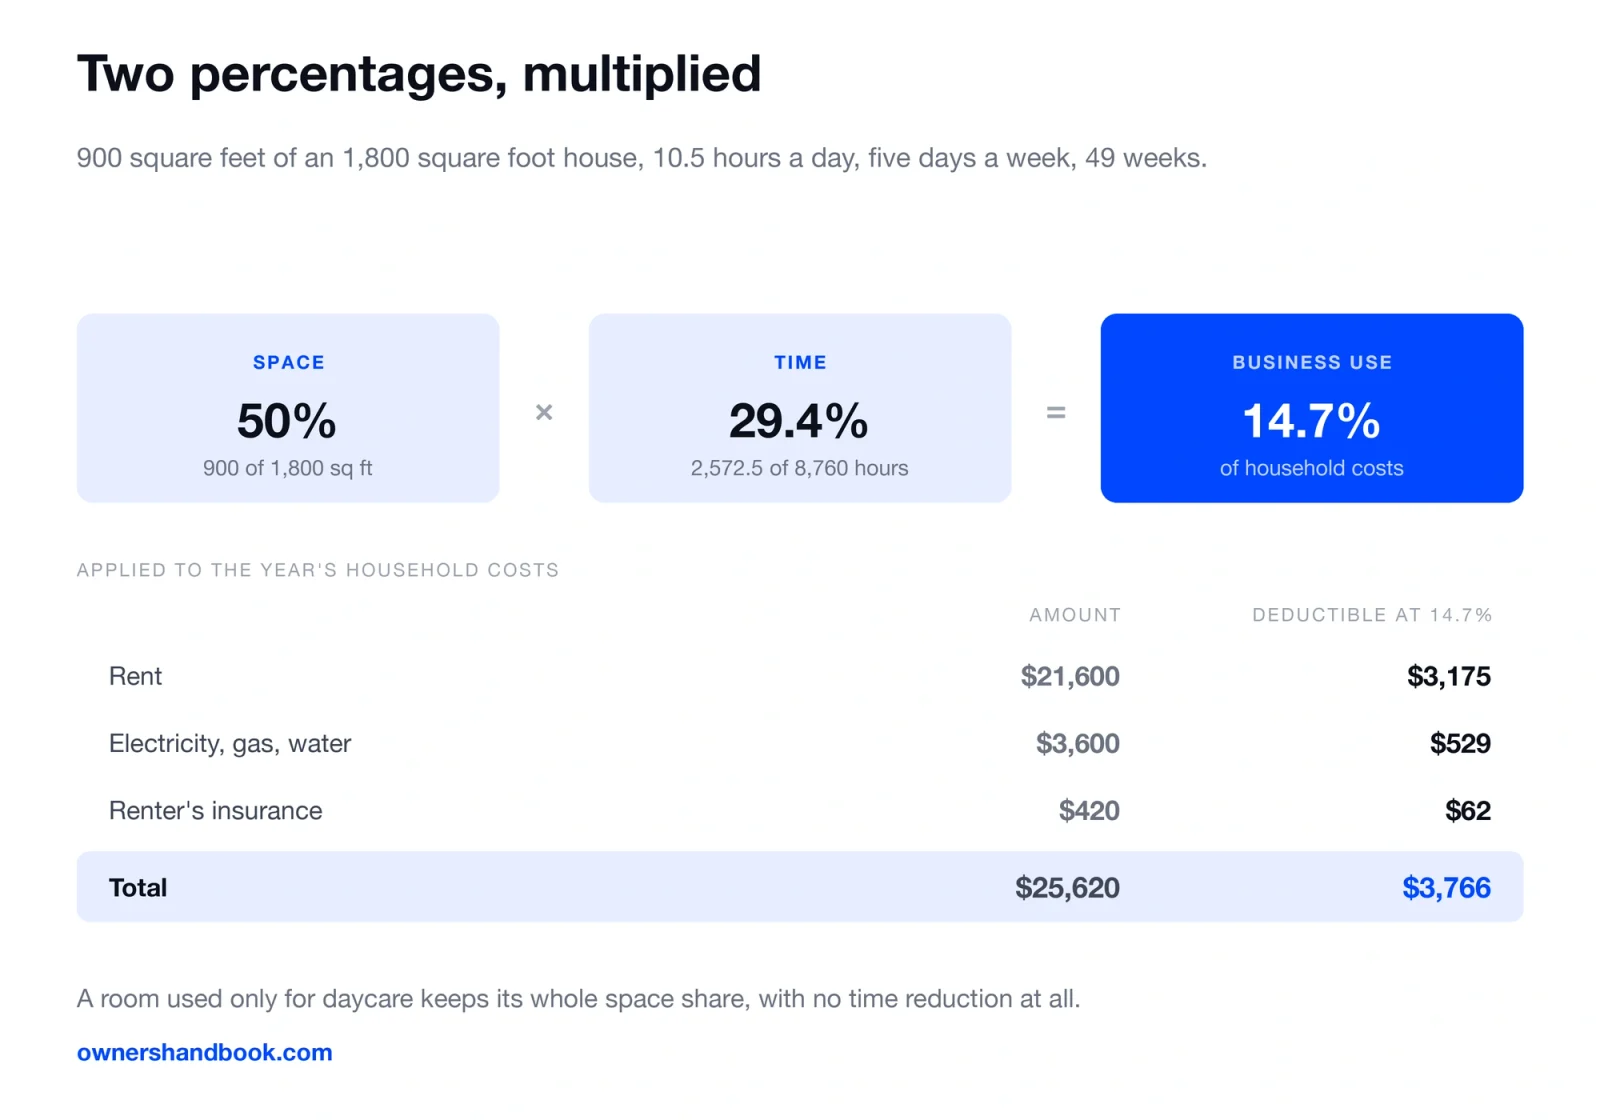
Say you use the living room, playroom and kitchen — 900 square feet of a 1,800 square foot house. Space percentage: 50%.
You operate 7am to 5.30pm, so 10.5 hours a day, five days a week, 49 weeks a year. That is 2,572.5 hours. Divided by 8,760: 29.4%.
Business-use percentage: 50% × 29.4% = 14.7%.
| Annual household cost | Amount | Deductible at 14.7% |
|---|---|---|
| Rent | $21,600 | $3,175 |
| Electricity, gas, water | $3,600 | $529 |
| Renter’s insurance | $420 | $62 |
| Total | $25,620 | $3,766 |
Two things about this. First, hours count when children are in the house, and the statute’s test is hours the portion is *used* — time spent cleaning, preparing and setting up for daycare when no child is present is still daycare use, and Publication 587 permits counting it. Log it. Second, a room used only for daycare and nothing else — a converted garage, say — keeps 100% of its space allocation without the time reduction, because the time ratio in (c)(4)(C) applies only where the portion is not used exclusively for those purposes.
You report the result on Form 8829 and carry it to Schedule C. Our walkthrough of Form 8829 line by line and the overview of Schedule C cover the mechanics.
Meals and snacks, without keeping every receipt
Food is a large cost in this business, and the IRS provides a way to deduct it without a shoebox of grocery receipts.
Publication 587 describes standard meal and snack rates that family daycare providers may use instead of substantiating actual food costs. You count meals and snacks served and multiply.
The rates are tied to the Child and Adult Care Food Program reimbursement rates. Publication 587 states that the applicable rates for 2025 are the Child and Adult Care Food Program reimbursement rates in effect on December 31, 2024, and gives them as:
| Location | Breakfast | Lunch | Dinner | Snack |
|---|---|---|---|---|
| Continental US | $1.66 | $3.15 | $3.15 | $0.93 |
| Alaska | $2.66 | $5.10 | $5.10 | $1.52 |
| Hawaii, Guam, Puerto Rico, US Virgin Islands | $2.14 | $4.09 | $4.09 | $1.22 |
Those are the figures in the current Publication 587, for tax year 2025. The rates are reset each year against the food programme, so check the edition of Publication 587 for the year you are filing rather than reusing these.
The mechanism matters more than the numbers. You may deduct up to one breakfast, one lunch, one dinner and three snacks per child per day. You still have to keep a record of the meals served — names, dates, counts — but not receipts for the food itself. Food you eat yourself is never deductible.
Providers who default to actual costs often deduct less for considerably more effort. See receipt rules for freelancers for what the record has to show.
What else changes for you
| Item | Treatment |
|---|---|
| Toys, craft supplies, car seats | Deductible; apportion if the family also uses them |
| Fencing, safety gates, outlet covers | Deductible if installed for the daycare |
| Playground equipment | Capital item, see writing off equipment |
| Licensing and inspection fees | Deductible |
| Liability insurance | Deductible |
| CPR and first aid certification | Deductible |
| Field trip mileage | Deductible at the standard rate |
Profit from the daycare is self-employment income, subject to self-employment tax and generally requiring quarterly estimated payments. Parents paying you may claim the child and dependent care credit, which means they will ask for your taxpayer identification number — and their claim reports your income to the IRS.
Frequently asked questions
Do I really not need a room used only for daycare?
Correct. Section 280A(c)(4) lifts the exclusive use requirement for daycare. You trade it for the time-based reduction.
What counts in the hours figure?
Hours the space is used for daycare, including preparation and cleaning time when no child is present. Keep a log; this number is the one most likely to be questioned.
My application is still pending. Can I deduct now?
Yes. The statute qualifies an applicant whose application “has not been rejected.” A pending application satisfies the condition for that period.
I care for an elderly parent’s friend during the day. Does this apply?
If you are in the trade or business of providing day care for individuals aged 65 or over, yes — the statute covers it in the same sentence as children.
Do I have to use the standard meal rates?
No. They are an alternative to substantiating actual costs. You may deduct actual food costs instead if your records support it, but you cannot mix methods within a year.
Sources
Legal Information Institute, 26 U.S. Code § 280A
https://www.law.cornell.edu/uscode/text/26/280A
IRS, Publication 587, Business Use of Your Home
https://www.irs.gov/publications/p587
IRS, About Form 8829, Expenses for Business Use of Your Home
https://www.irs.gov/forms-pubs/about-form-8829
IRS, About Schedule C (Form 1040), Profit or Loss From Business