Do You Send a 1099 to an LLC? Read the Letter on the W-9
The W-9 came back with the LLC box ticked, and now you are not sure whether you owe this person a 1099. The answer is not “no” — it depends on a letter written next to that box, and half the time the letter is missing.
Here is how to read the form you already have, and what to do when it does not tell you.
LLC is not an answer. The letter next to it is.
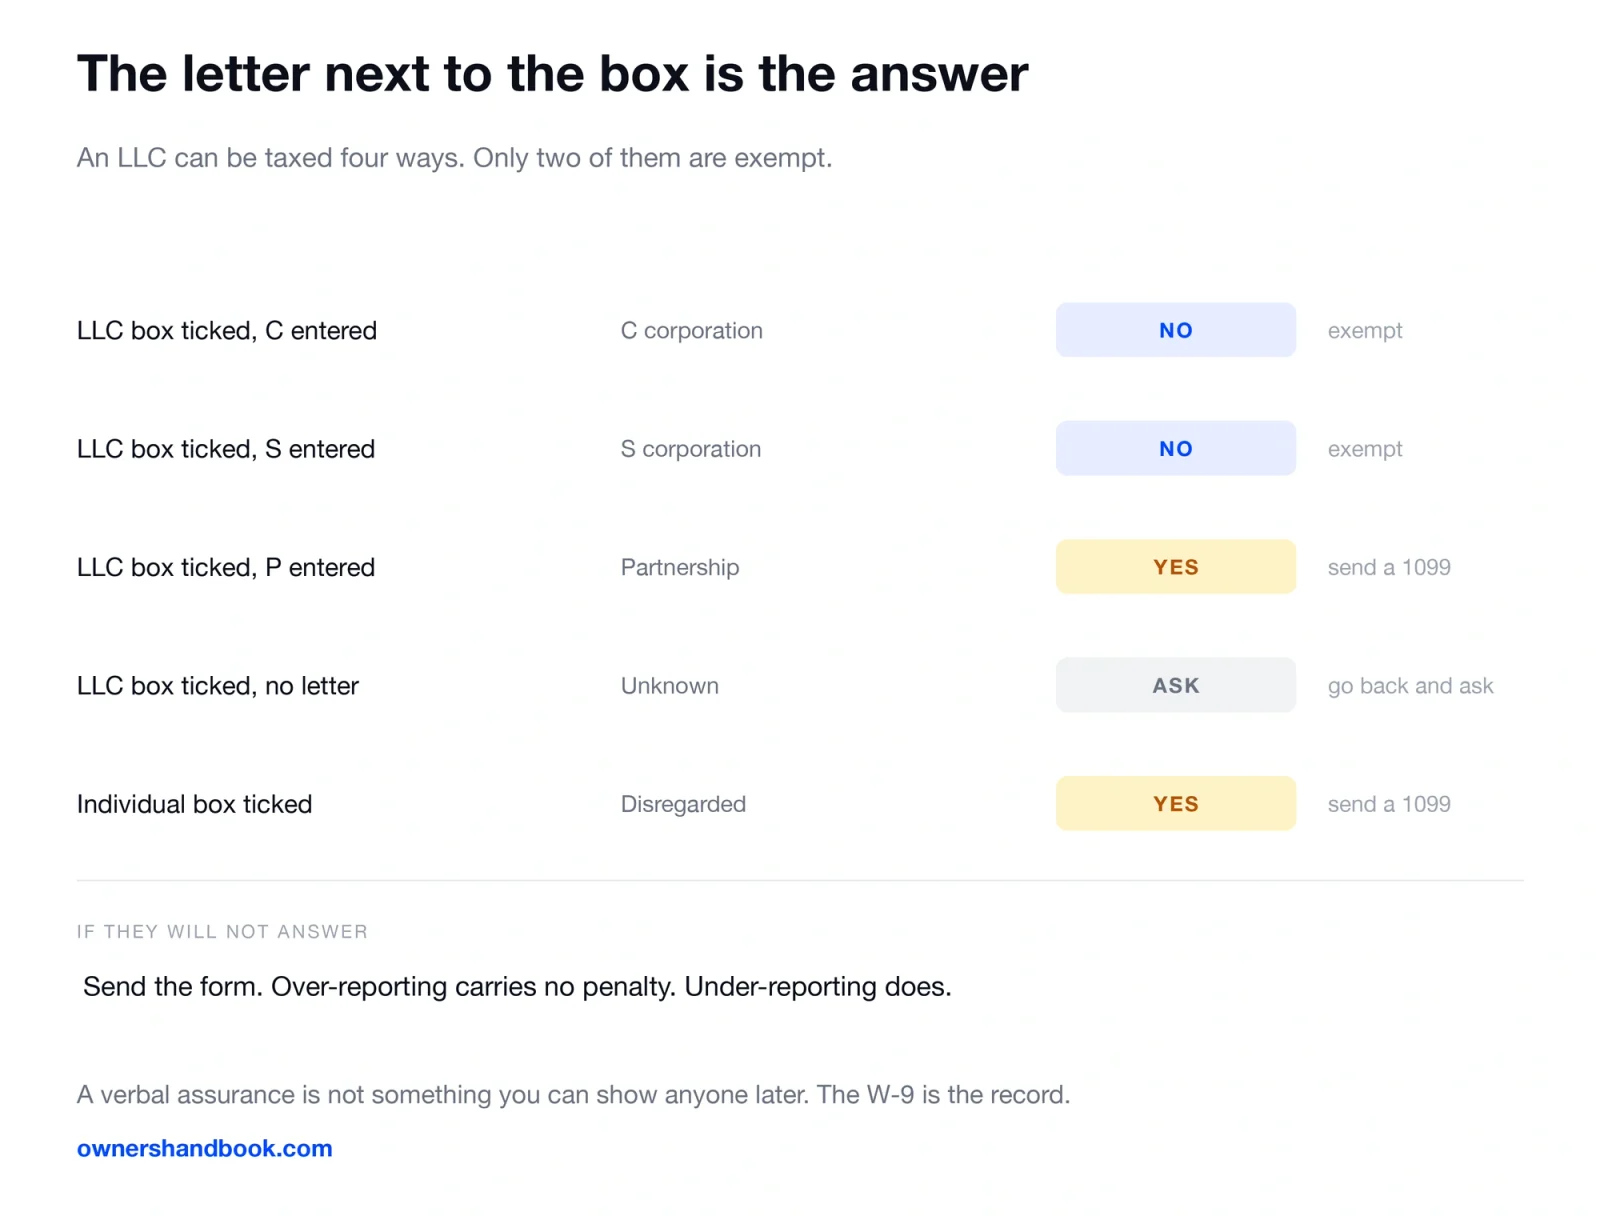
The corporate exemption is real, but it is about tax classification, not legal structure. An LLC can be taxed four different ways, and only two of them are exempt.
Form W-9 line 3 has a checkbox for limited liability company, and immediately after it a space for a single letter.
| What the W-9 shows | Taxed as | Do you send a 1099-NEC? |
|---|---|---|
| LLC box ticked, C entered | C corporation | No |
| LLC box ticked, S entered | S corporation | No |
| LLC box ticked, P entered | Partnership | Yes |
| LLC box ticked, no letter | Unknown | Find out |
| Individual/sole proprietor box ticked | Disregarded entity | Yes |
The IRS instructions state the exemption plainly — generally you do not report payments to *”a corporation (including an LLC) that is treated as a C or S corporation.”*
So a single-member LLC that never elected anything is a disregarded entity. It gets a 1099. A two-member LLC filing a partnership return gets a 1099. Only the ones that elected corporate treatment do not.
The threshold moved this year, and almost nothing online says so
Before you work out who, work out how much — because the number changed.
The IRS instructions for Forms 1099-MISC and 1099-NEC state:
For tax years beginning after 2025, the minimum threshold amount for reporting certain payments required to be reported on certain information returns and/or perform backup withholding on those payments increased to $2,000 and may be adjusted for inflation beginning in calendar year 2027.
| When you paid | Threshold |
|---|---|
| Through December 31, 2025 | $600 |
| From January 1, 2026 | $2,000 |
| 2027 onward | $2,000, possibly indexed |
The $600 floor was set in 1954 and stood for seventy years. A great deal of advice still prints it, because it was written while it was true.
Practically: a contractor you paid $1,800 in 2026 gets nothing at all. Our guide to issuing a 1099-NEC covers the mechanics once you know you owe one.
Attorneys are the exception, and the exception has two halves
This is the part people miss, and it is the one with real penalty exposure because law firms are almost always corporations.
The IRS instructions, verbatim:
Attorneys’ fees of $2,000 or more paid in the course of your trade or business are reportable in box 1a of Form 1099-NEC
And separately, for money that passes through an attorney rather than being paid for their services:
report in box 10 payments that: Are made to an attorney in the course of your trade or business in connection with legal services, but not for the attorney’s services, for example, as in a settlement agreement; Total $600 or more
| Payment to an attorney | Box | Threshold |
|---|---|---|
| Their fee for legal services | 1a | $2,000 |
| Gross proceeds passing through them | 10 | $600 |
Two different boxes, two different numbers, and the corporate exemption applies to neither. A law firm organised as a professional corporation still gets a form.
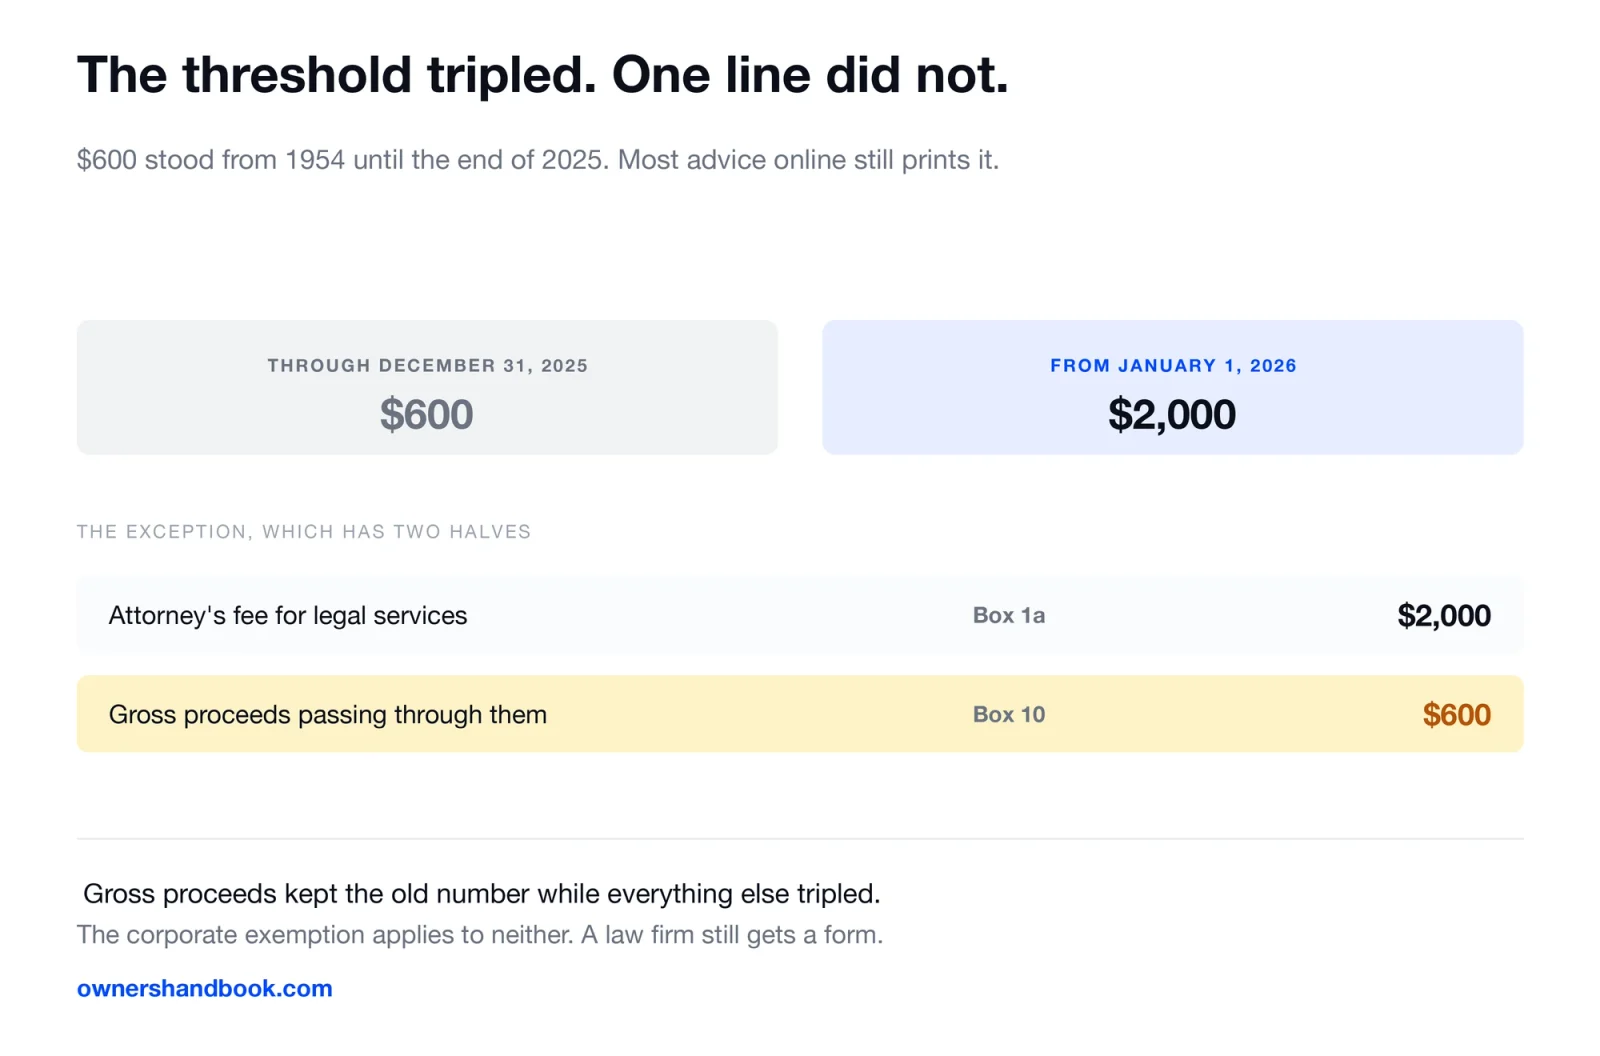
Gross proceeds is the one to watch. It kept the old $600 threshold while everything else tripled.
When the W-9 does not tell you
A W-9 with the LLC box ticked and no letter after it is the most common version of this problem.
Go back and ask. One line: “Your W-9 has the LLC box checked but no tax classification letter. Is the LLC taxed as a C corporation, an S corporation, or a partnership?” It is a thirty-second answer for them.
If they will not answer, send the form. Sending a 1099 to a payee who turns out to be exempt is not a penalty situation. Failing to send one to a payee who was not exempt is. The asymmetry decides it.
If you never got a W-9 at all, you have a larger problem than the 1099. Paying a contractor with no taxpayer identification number on file obliges you to withhold 24% of the payment and remit it — and leaves you liable for it if you did not. Our guide to Form W-9 covers what to collect and when.
Other things that do not change the answer
| What people think matters | Does it? |
|---|---|
| They have an EIN rather than an SSN | No |
| “LLC” is in their business name | No |
| They sent an invoice on letterhead | No |
| They are incorporated in Delaware | No |
| They told you they are a corporation | Not unless the W-9 says so |
The W-9 is the record. A verbal assurance is not something you can show anyone later.
What you do not report at all
The rule applies to payments for services in the course of your trade or business. Several common payments fall outside it.
| Payment | Reportable? |
|---|---|
| Goods, materials, merchandise | No — services only |
| A personal payment, unrelated to your business | No |
| Payment made by credit card or a payment app | No — the processor reports it on a 1099-K |
| Rent paid to an individual or partnership | Yes, but on 1099-MISC box 1, not NEC |
The card payment exclusion catches people. If you paid a contractor through a card or a third-party network, the processor handles the reporting. Sending a 1099-NEC as well means the income gets reported twice, which creates a problem for the recipient rather than for you — but it is still wrong. Our comparison of 1099-NEC and 1099-K covers the split.
What it costs to get this wrong
The penalties are per form, and they are charged twice — once for the copy the IRS did not get and once for the copy the contractor did not get.
| When you fix it | Per form | Small business cap |
|---|---|---|
| Within 30 days | $60 | $239,000 |
| By August 1 | $130 | $683,000 |
| After August 1, or never | $340 | $1,366,000 |
| Intentional disregard | at least $680 | no cap |
Those are two separate penalties under two separate code sections. Miss both copies for one contractor at the after-August tier and it is $680, not $340.
There is no extension for Form 1099-NEC. The thirty-day extension that covers other 1099s does not apply to it.
Frequently asked questions
The LLC has an EIN. Does that make it exempt?
No. Every LLC with employees or a corporate election has an EIN, and so do many sole proprietors. The EIN says nothing about tax classification. The letter on line 3 of the W-9 does.
What if I already sent a 1099 to an exempt corporation?
Nothing happens. There is no penalty for over-reporting, and the recipient reports their income the same way regardless.
Do I send one to a single-member LLC?
Yes, unless it elected corporate treatment. A single-member LLC that elected nothing is disregarded, and disregarded entities are not corporations.
Whose name goes on the form for a disregarded LLC?
Use the name and taxpayer identification number exactly as they appear on the W-9. If the two lines disagree with each other, ask before filing rather than guessing.
What if I paid them partly by card and partly by bank transfer?
Report only the portion you paid directly. The card portion is the processor’s to report.
Do I need to send one for payments to a foreign contractor?
Different form and different rules — Form 1099-NEC is for US persons. A foreign contractor supplies a W-8 rather than a W-9, and withholding questions arise. That is worth handling separately.
Sources
IRS, Instructions for Forms 1099-MISC and 1099-NEC
https://www.irs.gov/instructions/i1099mec
IRS, General Instructions for Certain Information Returns
https://www.irs.gov/instructions/i1099gi
IRS, About Form W-9, Request for Taxpayer Identification Number and Certification
https://www.irs.gov/forms-pubs/about-form-w-9
IRS, Information return penalties
https://www.irs.gov/payments/information-return-penalties
IRS, Limited liability company (LLC)
https://www.irs.gov/businesses/small-businesses-self-employed/limited-liability-company-llc