The W-9, Line by Line
A W-9 is one client asking one question: what name and what taxpayer ID number should we print on your 1099? Three answers finish the form — your name, your tax classification, your number — and it takes five minutes. It never goes to the IRS. It goes into your client’s files and stays there.
Where it goes, and where it never goes
The top right corner of the form says it in bold. Give form to the requester. Do not send to the IRS.
Your client needs it because they have to file an information return — a form that tells the IRS what they paid you. For freelance work that is usually a 1099-NEC.
They cannot file it without your legal name and taxpayer identification number. The W-9 is how they ask.
This is a private document between you and one company. You fill out a new one for each client, before the first invoice, not in January.
The current version is Rev. March 2024, printed in the top-left corner. Old copies live a long time in company folders, so check the date.
Lines 1 and 2 are one question
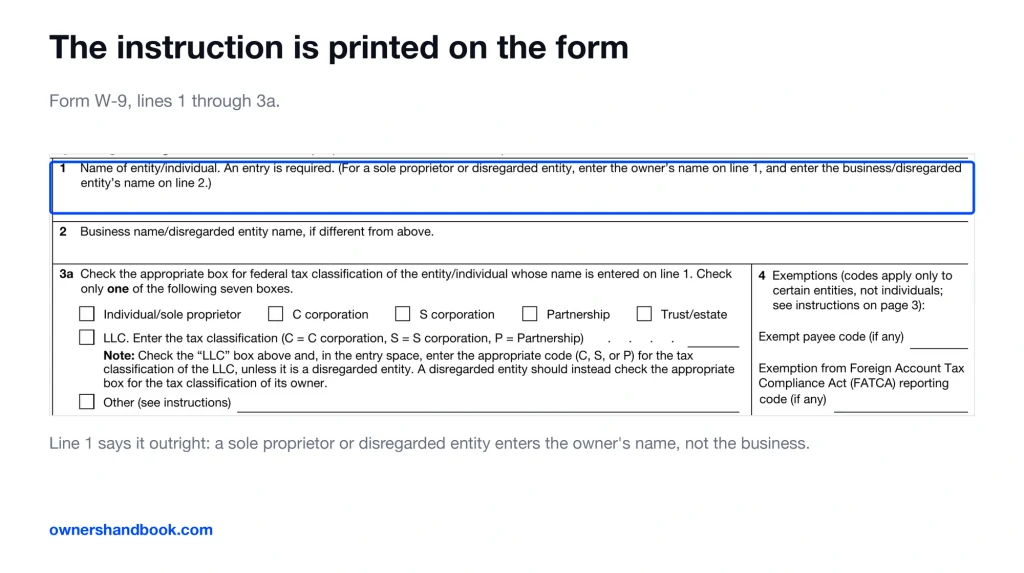
Line 1 is the name on your tax return. Line 2 is the name on your invoices. When those are the same name, line 2 stays blank.
Line 1 cannot be blank, and the name has to match your tax return.
For a sole proprietor that is your own name. Rowan Vega, exactly as it reads on Form 1040. Not Vega Studio.
The studio name goes on line 2, which the form calls your business, trade, or DBA name. DBA means doing business as — the name you work under that is not your legal name.
The single-member LLC is where this goes wrong. A single-member LLC is a disregarded entity by default, meaning the IRS looks past it and taxes the owner directly.
So line 1 is still the owner’s name. The LLC’s name drops to line 2. The instructions are blunt about it: the name on line 1 should never be a disregarded entity.
The reason is mechanical. The IRS matches the line 1 name against the number in Part I. Put the LLC on line 1 and the pair fails to match, and the notices start.
Line 3a decides the rest of the form
Line 3a is seven checkboxes and you check exactly one. Individual/sole proprietor, C corporation, S corporation, Partnership, Trust/estate, LLC, or Other.
Most freelancers check the first box. A sole proprietor checks it, and so does a single-member LLC.
That second one surprises people. A disregarded entity checks the box for the tax classification of its owner, and the owner here is an individual.
The LLC box is not for you unless your LLC elected to be taxed as something else. If you check it, you must write a letter in the space beside it — C, S, or P.
Line 3b was added in the March 2024 revision. It is for partnerships, trusts, and estates with foreign partners or beneficiaries. Skip it.
Line 4 is exemption codes, and the form settles it in one line: codes apply only to certain entities, not individuals. Individuals, sole proprietors included, are not exempt from backup withholding. Blank.
Lines 5 and 6 are your address — specifically, where this client will mail your 1099. Use one you will still read mail at in February.
Line 7 asks for account numbers. Optional, almost always blank.
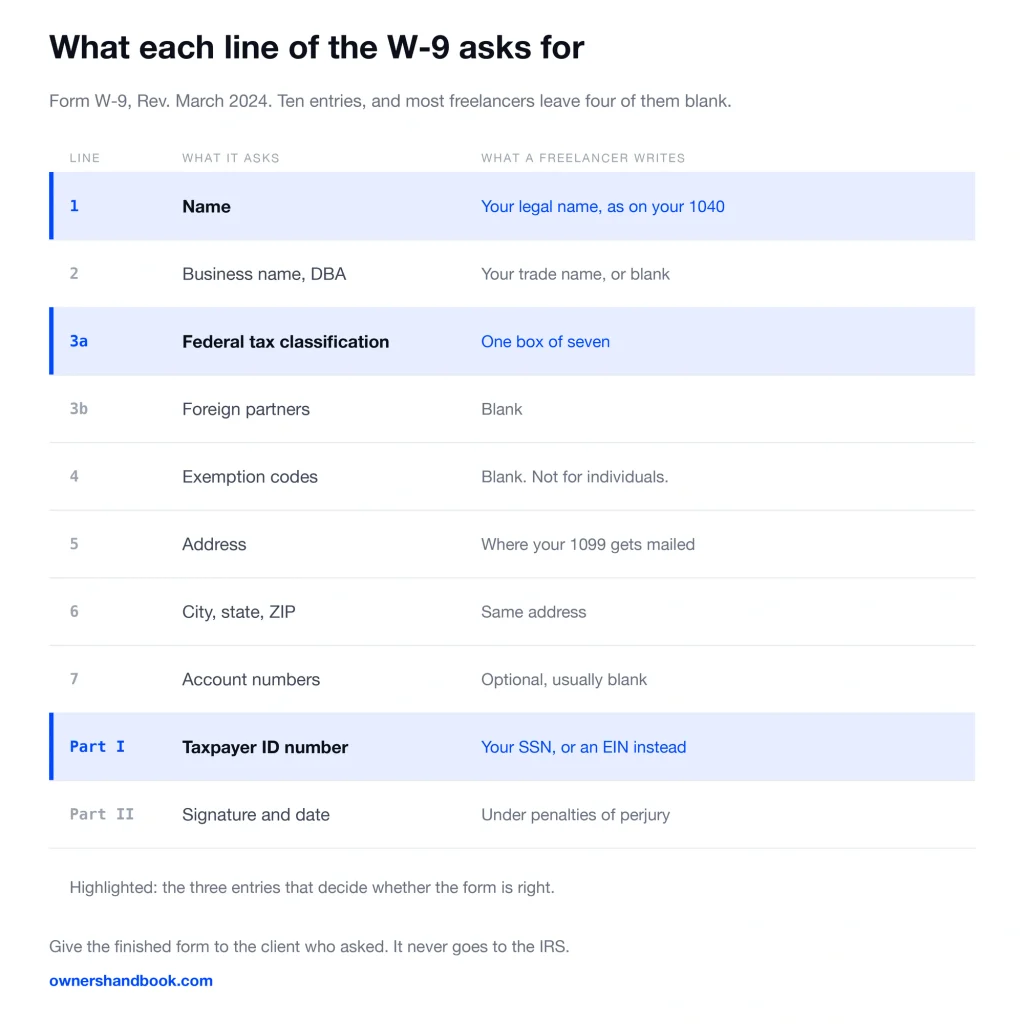
| Line | What it asks | What you write |
|---|---|---|
| 1 | Name | Your legal name, as on your 1040. Required. |
| 2 | Business name, DBA | Your trade name. Blank if it matches line 1. |
| 3a | Federal tax classification | One box of seven. Usually Individual/sole proprietor. |
| 3b | Foreign partners | Partnerships, trusts, estates only. Blank. |
| 4 | Exemption codes | Not for individuals. Blank. |
| 5 | Address | Where this client mails your 1099. |
| 6 | City, state, ZIP | Same address. |
| 7 | Account numbers | Optional. Usually blank. |
| Part I | Taxpayer ID number | SSN or EIN. One box, never both. |
| Part II | Signature and date | Under penalties of perjury. |
The same person, three ways
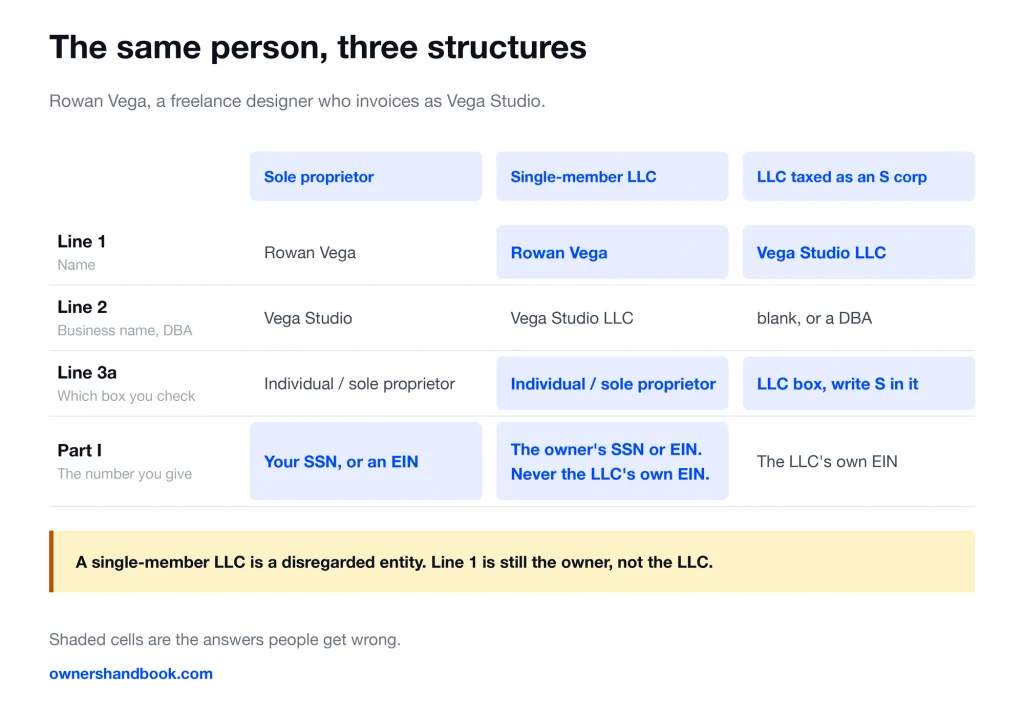
Rowan Vega is a freelance designer who invoices as Vega Studio. Here is the same person filling out the same form under three different structures.
As a sole proprietor: line 1 Rowan Vega, line 2 Vega Studio, line 3a Individual/sole proprietor.
As a single-member LLC: line 1 Rowan Vega, line 2 Vega Studio LLC, line 3a Individual/sole proprietor. The lines barely move. Only line 2 changes.
As an LLC that elected S corporation treatment: line 1 Vega Studio LLC, because now the entity files its own return. Line 3a is the LLC box with an S written in it, not the S corporation box.
The S corporation box is for a corporation that elected S status. An LLC that elected it checks LLC and writes S.
| What you are | Line 1, then line 2 | Line 3a | Part I number |
|---|---|---|---|
| Sole proprietor | Rowan Vega, then Vega Studio | Individual/sole proprietor | Your SSN, or an EIN if you have one |
| Single-member LLC | Rowan Vega, then Vega Studio LLC | Individual/sole proprietor | The owner’s SSN or EIN, never the LLC’s |
| LLC taxed as an S corp | Vega Studio LLC, then blank | LLC box, write S | The LLC’s own EIN |
Part I: your SSN is not the only option
Part I has two boxes. Social security number, or employer identification number. You fill one.
Most freelancers write the SSN because it is the only number they own. It does not have to stay that way.
An EIN is a nine-digit federal tax ID for a business. It is free, you apply online at irs.gov, and the number is issued immediately.
The form permits it in one sentence: if you are a sole proprietor and you have an EIN, you may enter either your SSN or EIN.
That matters because a W-9 is a document you hand to strangers. Every client, every agency, every marketplace. Each copy parks your social security number in somebody else’s system.
An EIN answers the same question for the same client using a number that is not the key to your credit file.
Two honest caveats before you go get one.
The IRS itself encourages sole proprietors to use their SSN, in a footnote on page 5 of the form. That is a preference, not a rule, and the choice on the line above it is still yours.
And an EIN changes nothing about your taxes. Same Schedule C, same self-employment tax. It is a label, not a structure.
One trap for single-member LLCs. If your LLC has its own EIN — you got one for payroll, or a bank demanded it — that is not the number for Part I.
A disregarded single-member LLC enters the owner’s SSN, or the owner’s EIN if the owner has one. The LLC’s EIN belongs on the LLC’s own filings.
Part II: what the signature means
Under penalties of perjury, your signature certifies four things.
That the number on this form is your correct TIN, or that you have applied for one. That you are not subject to backup withholding. That you are a U.S. person. And that any FATCA code you entered is correct.
Item 2 is the one to read twice. If the IRS has notified you that you are currently subject to backup withholding, you cross item 2 out before signing. The form instructs you to do exactly that.
FATCA is the Foreign Account Tax Compliance Act, a reporting rule aimed at accounts held outside the United States. No foreign accounts, no code, blank line.
Here is a detail almost nobody knows. For ordinary payments to a nonemployee for services, you must give a correct TIN but you are not required to sign the certification.
The one exception is if the IRS previously told you that the number you gave was wrong. Then the signature is required.
Your client will want the signature anyway, and there is no upside in arguing. Sign it.
Backup withholding at 24%
Backup withholding is what happens when this paperwork fails. Your client keeps 24% of what they owe you and sends it to the IRS instead.
It is not a penalty and the money is not gone. It appears as federal income tax withheld on your 1099 and comes off your bill in April.
It is still a quarter of your cash flow held by the government for up to a year.
For freelance work there are two realistic ways in. You never gave the client a TIN. Or the IRS told the client the TIN you gave does not match the name.
The other triggers on the form apply only to interest and dividend accounts, not to payment for services.
There are flat penalties too. Failing to furnish your correct TIN to a requester costs $50 per failure, unless the failure was due to reasonable cause. A false statement with no reasonable basis that results in no backup withholding costs $500.
Frequently asked questions
Do I send the W-9 to the IRS?
No. It goes to whoever asked for it. The IRS learns your numbers later, from the 1099 that client files.
Can I put an EIN in Part I instead of my SSN?
Yes, if you are a sole proprietor and you have an EIN. The form allows either one. The IRS encourages the SSN in a footnote, but it is your call.
My LLC has its own EIN. Does that go in Part I?
Not if it is a single-member LLC treated as a disregarded entity. Use the owner’s SSN, or the owner’s EIN. The LLC’s EIN is for payroll and bank accounts.
A client I have worked with for years suddenly wants a new W-9. Why?
Usually a system migration or a compliance sweep, sometimes a merger. Send a fresh one. A second request is not a red flag.
What happens if I just do not send it?
The client can withhold 24% of every payment and remit it to the IRS. In practice most of them will hold the payment entirely until the form arrives.
Is a W-9 the same as being an employee?
No. Employees fill out a W-4 and have tax withheld from every paycheck. A W-9 means you are paid as an independent contractor, with nothing withheld.
Sources
IRS, About Form W-9, Request for Taxpayer Identification Number and Certification
https://www.irs.gov/forms-pubs/about-form-w-9
IRS, Form W-9 (Rev. March 2024)
https://www.irs.gov/pub/irs-pdf/fw9.pdf
IRS, Instructions for the Requester of Form W-9
https://www.irs.gov/instructions/iw9
IRS, Backup Withholding
https://www.irs.gov/businesses/small-businesses-self-employed/backup-withholding
IRS, Get an Employer Identification Number
https://www.irs.gov/businesses/small-businesses-self-employed/get-an-employer-identification-number