Meals and Travel: What Survives an Audit
Business meals come off at 50%. Travel — the flight, the hotel, the rental car — comes off in full, but only if the trip kept you away from home overnight. A sandwich you ate alone at your desk is worth nothing. The same sandwich eaten alone in a hotel three states away is worth half. The receipt does not decide that. The reason does.
Two rules, not one
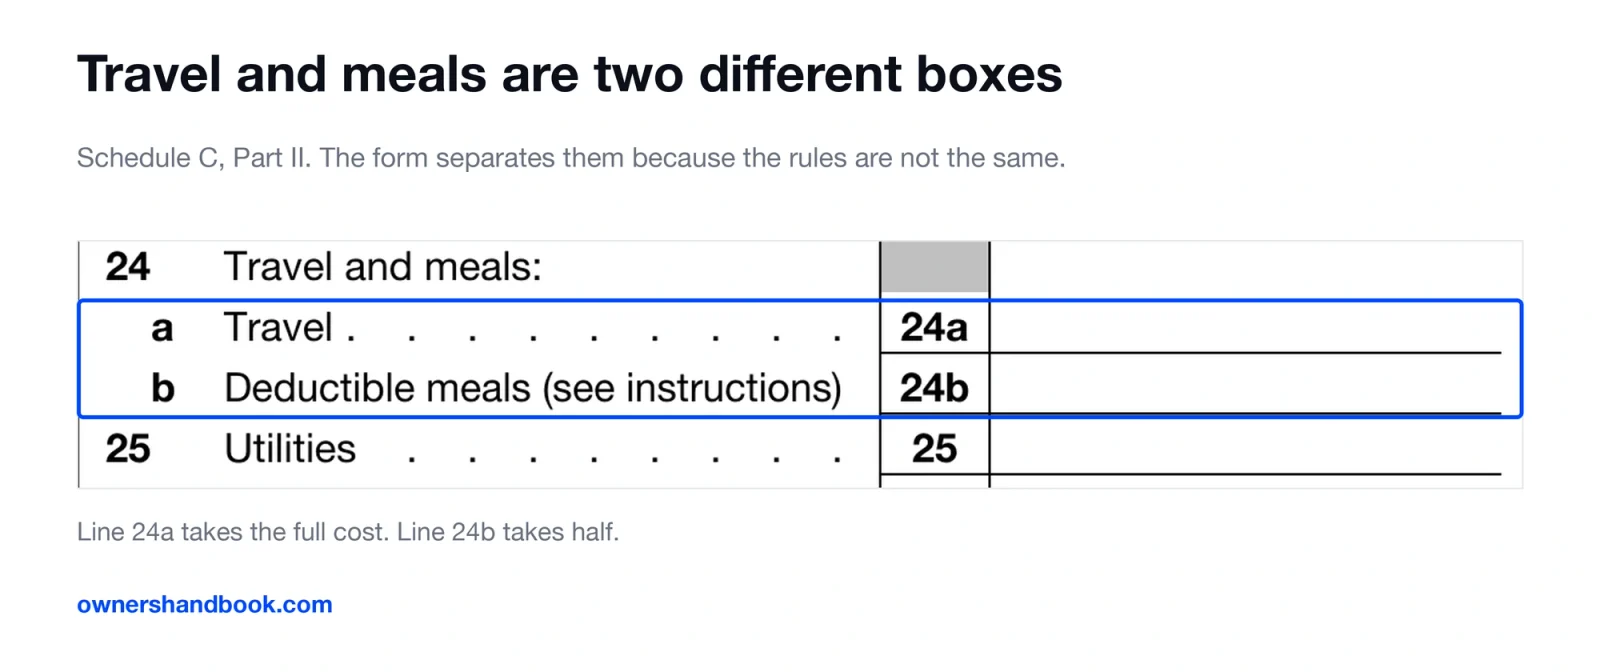
Meals and travel land on two different lines of Schedule C, and they follow two different rules.
Line 24a is travel. Lodging and transportation connected with overnight business travel away from your tax home. No meals go on this line.
Line 24b is meals. In most cases half of what you actually spent.
People treat these as one bucket because a trip produces both at once. The IRS does not. Split them the moment the money leaves.
That split is also why a trip is worth more than it first looks. The airfare comes off whole. Only the food gets cut in half.
The overnight test
Travel expenses require you to be away from home, and away from home is a defined term, not a feeling.
Your tax home — the place the rules measure from — is your regular place of business, plus the whole city or general area around it. Not your street address.
You are away from home when two things are true at once. Work keeps you out of that area substantially longer than an ordinary day, and you need to sleep or rest to do the job.
The IRS is blunt about the second half. Napping in your car does not count.
So a 200-mile round trip to shoot a wedding and drive home the same night is not travel. Your mileage still deducts. Your dinner on the road does not.
Book a hotel and the whole trip changes character. Flight, room, rental car, baggage, dry cleaning, tips — all line 24a. Meals at half on 24b.
One limit for long engagements. If a job in another city is realistically expected to run more than a year, that city becomes your new tax home and the travel deduction stops.
Which meals count, and how much
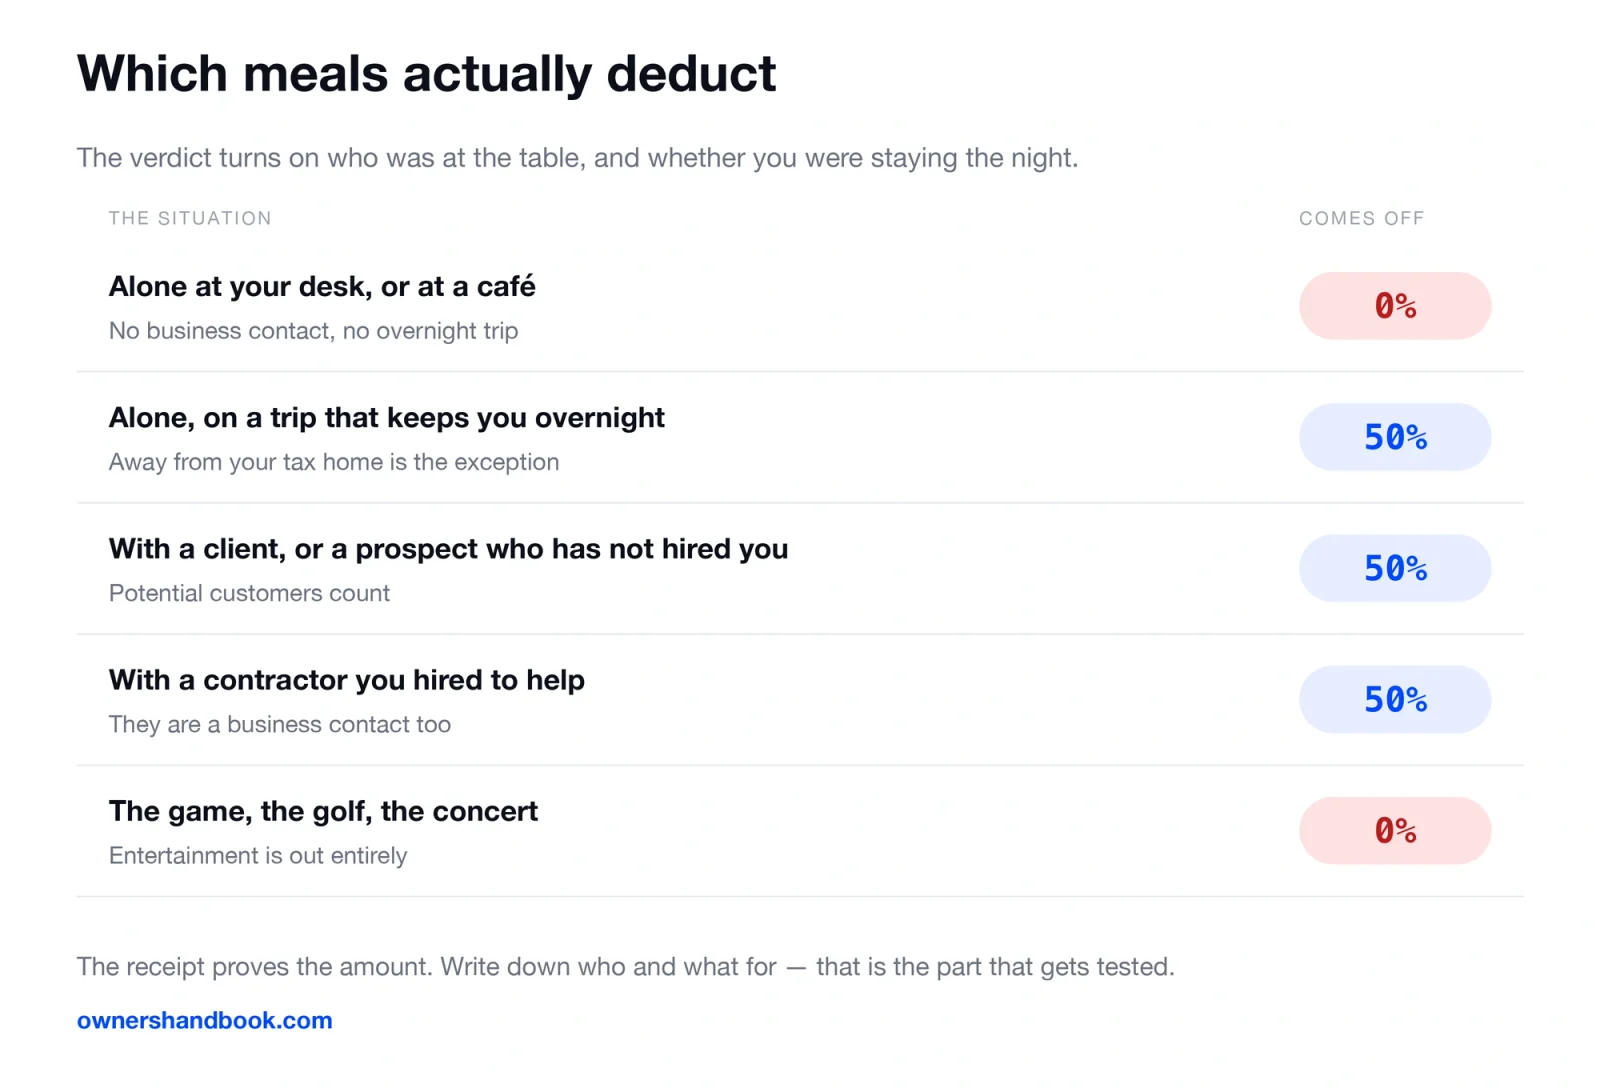
| The situation | Comes off |
|---|---|
| Alone at your desk or a cafe, no business reason | 0% |
| Alone, on a trip that keeps you overnight | 50% |
| With a client, or a prospect who has not hired you | 50% |
| With a contractor you hired | 50% |
| A concert, a round of golf, a game | 0% |
A meal is deductible when it was ordinary and necessary for the business, was not lavish, you were present, and the food went to a current or potential client, consultant, or similar business contact.
Read that last condition again. It is the one that kills most claimed meals.
Lunch alone at your desk fails it. So does lunch alone at a café because you were sick of your apartment. No business contact at the table.
Coffee with a prospect who has not hired you yet passes. Potential counts.
Dinner with a contractor you hired for a project passes. They are a business contact.
Then there is the exception that surprises people. Once you are away from home overnight, your own meals deduct at 50% with nobody else at the table.
Concrete. A $180 dinner with two clients is a $90 deduction. A $22 airport sandwich on a business trip is an $11 deduction. That same $22 sandwich at your desk on a Tuesday is $0.
One trade deducts 80%, not 50%
The 50% figure on this page is wrong for one group of readers, and the statute says so directly.
Section 274(n)(3) substitutes 80 percent for 50 percent where the food or drink is consumed while away from home by someone during, or incident to, a period of duty subject to the hours of service limitations of the Department of Transportation.
That is drivers, and certain air, rail and marine crew. If the hours-of-service rules govern your working day, every “meals are 50% deductible” article — including the rest of this one — understates your deduction by more than half again.
Our guide to owner-operator truck driver taxes works through that rate, the standard meal allowance, and the other things about that trade a general deduction guide gets wrong.
Entertainment is not a gray area
Entertainment is not deductible. Not at half, not at all.
Concert tickets, a round of golf, the game, the boat. None of it, even when real business got done there.
What matters more is what happens to the food at the same event. Food and drink bought during entertainment deduct only if they were purchased separately, or billed on their own line.
A $400 skybox package with dinner rolled in is $0. Buy that $90 dinner on its own tab and you have a $45 deduction.
And you cannot rescue it by inflating what the food cost on the invoice. The regulations name that exact move.
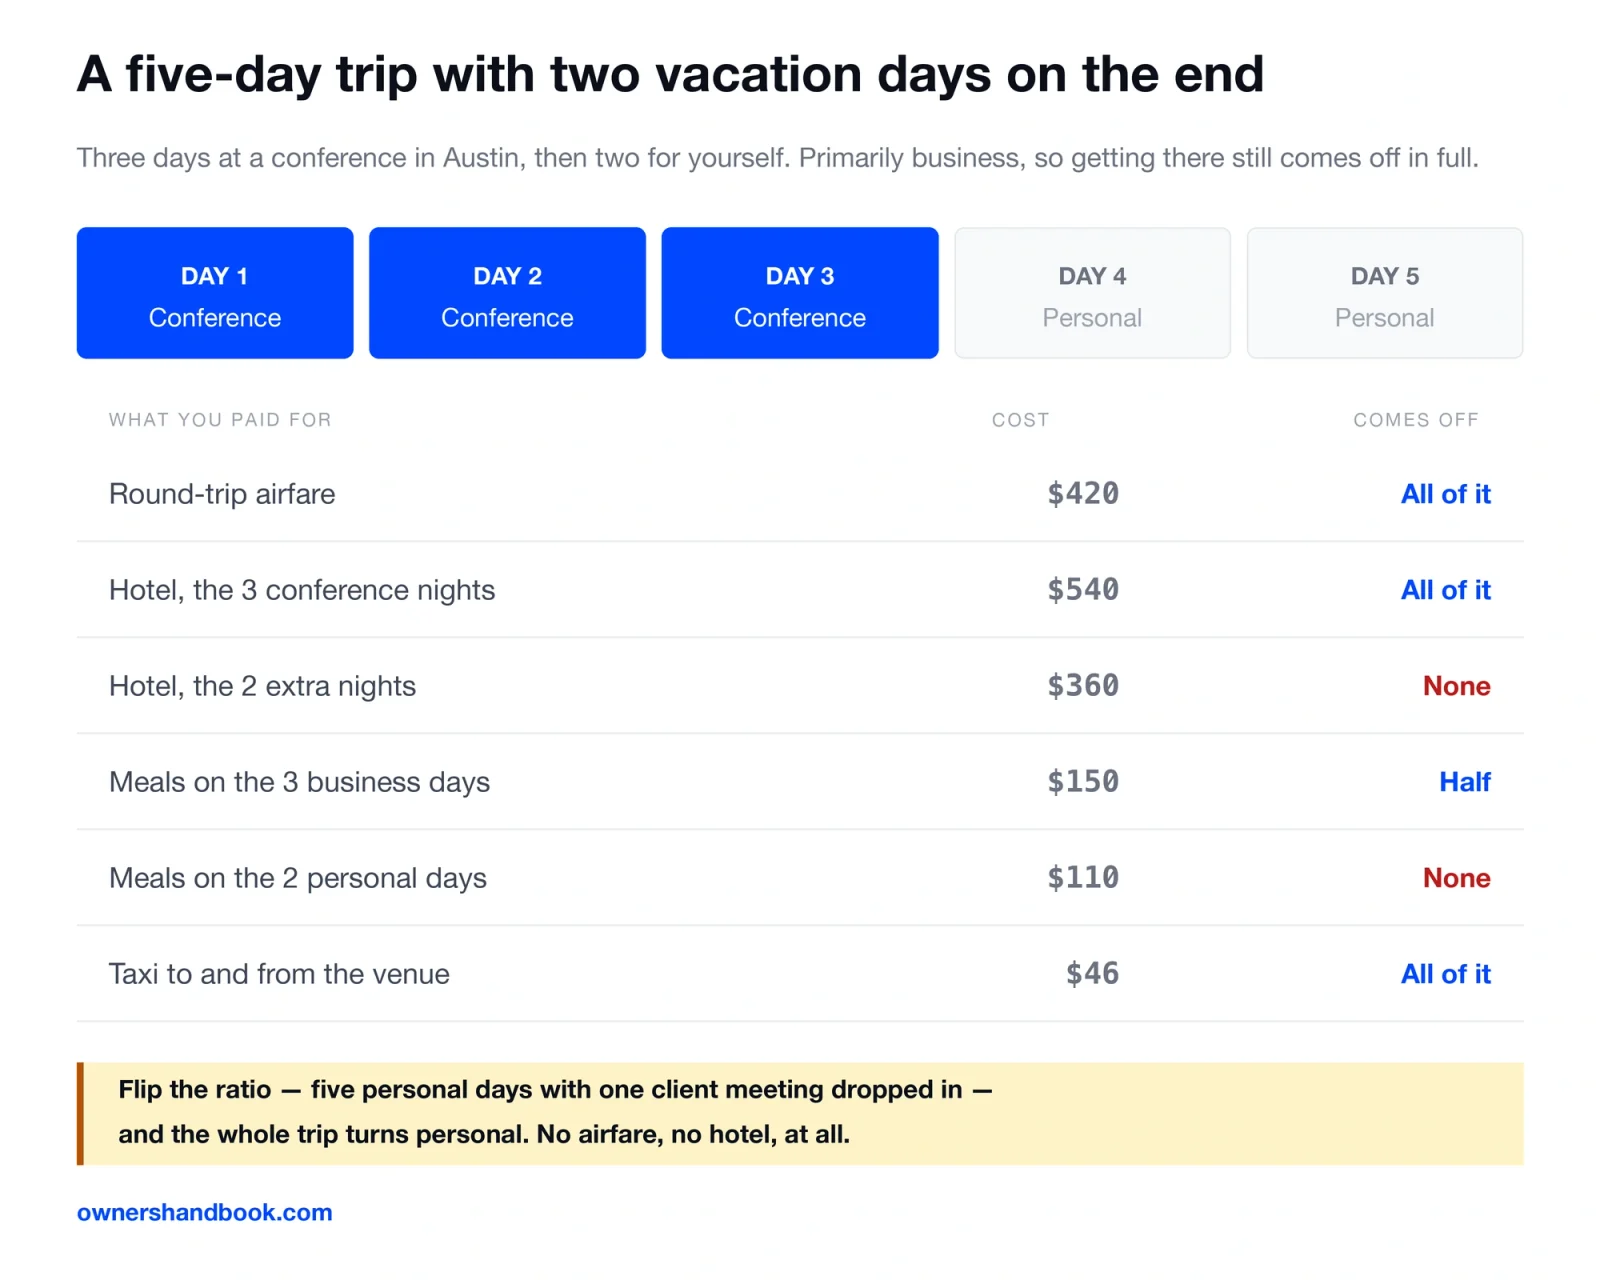
A trip with vacation days attached
| Three conference days, two personal days | Cost | Comes off |
|---|---|---|
| Round-trip airfare | $420 | All of it |
| Hotel, the 3 conference nights | $540 | All of it |
| Hotel, the 2 extra nights | $360 | None |
| Meals on the 3 business days | $150 | Half |
| Meals on the 2 personal days | $110 | None |
Say you fly to Austin for a three-day conference and stay two extra days to see the city.
The trip was primarily for business, so the round-trip airfare is fully deductible. Getting there was a business cost, and it does not shrink because you stayed longer.
Three conference nights of hotel: deductible. The two vacation nights: not.
Meals on the business days: 50%. Meals on the vacation days: nothing.
Now flip the ratio. Five vacation days with one client meeting dropped in the middle.
That trip is primarily personal, and the entire cost of it is a nondeductible personal expense. No airfare. No hotel.
You can still deduct what you spent at the destination that was directly business — the meeting’s meal, the taxi to the client’s office.
Which side of the line you land on turns on business days against personal days, so keep a calendar you could actually show someone.
One more. Your partner’s ticket is not deductible unless they are your employee traveling for a real business reason.
The receipt shows the amount, never the reason
Here is the whole category in one sentence. Meals and travel get challenged more than anything else because the proof that matters is the proof nobody keeps.
The law asks for five things: the amount, the time, the place, the business purpose, and your business relationship to the people there.
A receipt hands you three. Amount, time, place. It has never once printed why you were sitting there.
So build a 30-second habit. Before the receipt goes anywhere, write two things on it. Who, and what for.
“Maya Chen, Riverbend Design — scoped the March rebrand.” Done. That is the record.
Write it on the paper, in your phone notes, in the memo field of your expense app, in the calendar entry. Nobody cares where. They care that you wrote it near the time.
A note made the same week counts as timely. A purpose reconstructed in April from a card statement is not a record, and it is the first thing to collapse if anyone asks.
Two details worth knowing. You do not need a receipt at all for a non-lodging expense under $75 — but the written purpose still has to exist.
And a restaurant receipt only counts as adequate proof if it shows the restaurant’s name and location, the number of people served, and the date and amount.
Number of people served. That line is doing real work. Keep the itemized slip, not just the card copy.
The per diem shortcut
If tracking every meal on the road is the thing that stops you from claiming any of them, use the standard meal allowance instead.
Per diem here means a fixed daily amount for meals and incidental expenses, set by location, that you deduct in place of your actual food spending.
For most smaller U.S. localities that rate is $68 a day for the period running October 2025 through September 2026. Major cities run higher.
Self-employed people are allowed to use it. You do not have to be reimbursed by anyone to qualify.
Three catches.
The 50% limit still applies. Four days at $68 is $272, and your deduction is $136.
There is no equivalent shortcut for lodging. Your hotel deduction is always your actual cost, with the bill to match.
And on your departure day and your return day you claim three-quarters of the rate, not the whole thing.
The allowance replaces your receipts for the amount only. It does not replace the record of time, place, and business purpose. You still write those down.
Frequently asked questions
Can I deduct a coffee I bought while working at a café?
No. There is no business contact at the table and you are not away from home overnight. The café is a good office, not a deduction.
I drove three hours to a client and back the same day. Is my lunch deductible?
Only if you ate it with the client or another business contact. With no overnight stay you were never away from home, so a solo meal fails. Your mileage is still deductible.
Is the 50% limit ever 100%?
Not for ordinary freelance meals. The temporary full deduction for restaurant food covered 2021 and 2022 only and expired. Drivers and pilots under Department of Transportation hours-of-service limits get 80%.
Do I need the itemized receipt, or is the card charge enough?
Keep the itemized one. The card slip shows the amount but not the number of people served, and that is one of the things an adequate restaurant receipt has to show.
Can I deduct a conference in Hawaii?
Yes, if the conference genuinely relates to your business and the trip is primarily business. Count business days against personal days before you claim the airfare.
What if I forgot to write down the purpose at the time?
Write down what you actually remember now and note that you reconstructed it. That is weaker than a timely record but better than a blank. Then fix the habit going forward.
Sources
IRS, Publication 463, Travel, Gift, and Car Expenses
https://www.irs.gov/publications/p463
IRS, Instructions for Schedule C
https://www.irs.gov/instructions/i1040sc
IRS, Here’s what businesses need to know about the enhanced business meal deduction
IRS, Notice 2025-54, Special Per Diem Rates
https://www.irs.gov/pub/irs-drop/n-25-54.pdf
IRS, Deducting Business Expenses
https://www.irs.gov/businesses/small-businesses-self-employed/deducting-business-expenses
IRS, Recordkeeping
https://www.irs.gov/businesses/small-businesses-self-employed/recordkeeping
Internal Revenue Code section 274(n)(3), the 80 percent rate for hours-of-service workers