Ohio Taxes You Three Times. Most Freelancers Find Out Late.
Ohio’s state income tax on $80,000 of freelance profit is usually zero. The Business Income Deduction takes the first $250,000 of business income off your Ohio return, so a sole proprietor under that line owes the state nothing.
The bill comes from the other two. Your municipality taxes the same net profit. Your school district may tax it as well. Neither one is collected by the state, and nothing is withheld from a freelance payment.
All of this is Ohio state and local tax. It sits on top of United States federal income tax and the 15.3% federal self-employment tax, neither of which Ohio touches.
The state tax is the small one
Ohio taxes business income separately from everything else. Business income is what a sole proprietorship or pass-through entity produces, and your Schedule C net profit is business income.
You deduct the first $250,000 of it, or $125,000 if you are married filing separately. Anything above that is taxed at a flat 3%.
Everything that is not business income runs through the regular brackets instead. Wages, interest, a pension. For 2025 the schedule was 0% up to $26,050, then 2.75%, then 3.125% above $100,000.
Those bracket figures come from the 2025 IT 1040 instructions, the most recent booklet the Department of Taxation has published. Every local rate in this article is the current 2026 one.
Your city taxes the profit, and nobody withholds it
Ohio municipalities levy their own income tax. The Department of Taxation’s current rate table lists 679 municipalities, 667 of them with a rate above zero.
Rates run from 0.45% in Indian Hill to 3.00% in Bedford and Parma Heights. Most sit at 1.00%, 1.50%, or 2.00%. Columbus, Cleveland, Toledo, Akron, and Dayton are all 2.50%. Cincinnati is 1.80%.
The tax reaches you two ways. You owe your home municipality because you live there, and you owe any municipality where you actually performed the work.
Gahanna’s finance department states it plainly. The rate applies to income earned in the city by employment or by residence, and to business net profits located in the city.
If you live in one city and work in another, your home city usually credits what you paid the work city. Gahanna gives a 100% credit. Many cities give less.
A sole proprietor files the municipality’s individual return, not its net profit return. CCA says this directly: anyone filing a federal Schedule C, E, or F uses the individual form.
The school district is the one people miss
Ohio school districts can levy an income tax of their own. Not all do. As of January 2026, 214 of them did, and the Department of Taxation publishes the full list.
This tax is decided by where you live, not where you work. Someone who works in a taxing district but lives outside it owes that district nothing.
There are two tax bases, and the difference matters enormously to a freelancer.
The traditional base taxes modified adjusted gross income less exemptions. The earned income base taxes only wages and net earnings from self-employment. 68 of the 214 districts use the earned income base.
Here is the trap. Modified adjusted gross income means your Ohio adjusted gross income plus the business income deduction you just took. The deduction that erased your state tax does not erase this one.
The return is the SD 100. You file it alongside your IT 1040, and one SD 100 covers every district you lived in during the year.
What $80,000 actually costs in Westerville
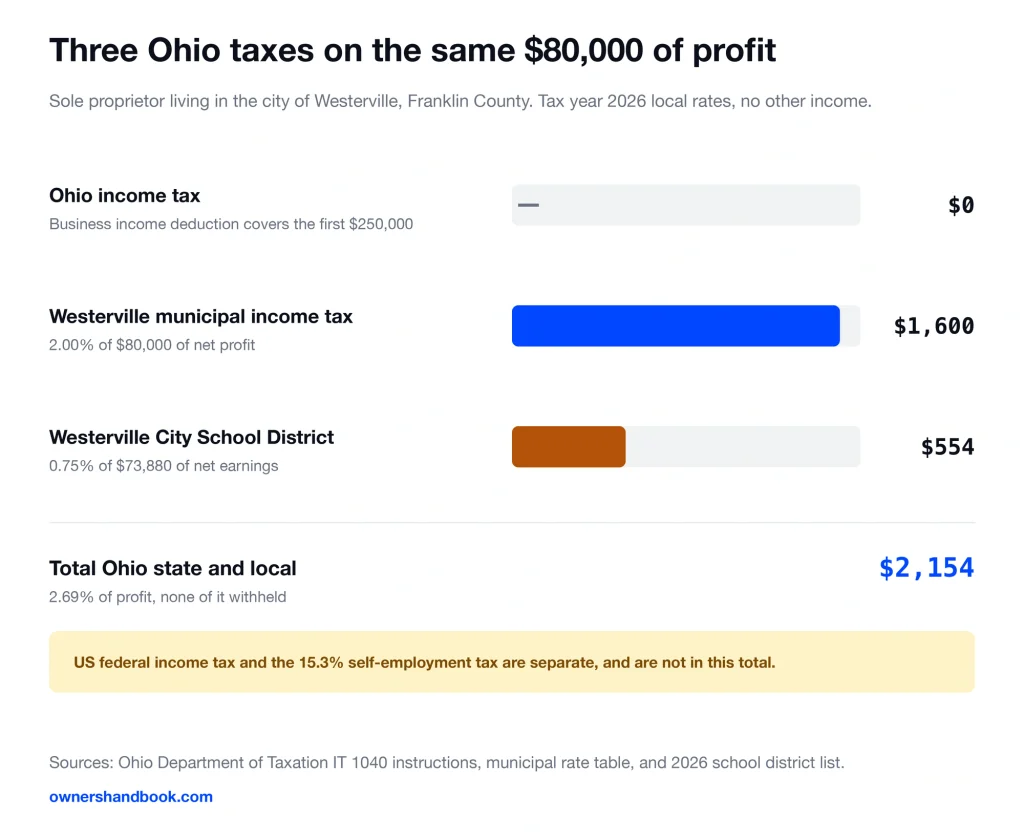
Take a freelancer who lives in the city of Westerville, in Franklin County, inside Westerville City School District. Clients paid $95,000 during 2026. After expenses, net profit is $80,000.
Ohio takes nothing. The $80,000 is business income and the deduction covers all of it.
Westerville’s municipal rate is 2.00%. On $80,000 of net profit that is $1,600.
Westerville City School District began levying an income tax in 2026, at 0.75%, on the earned income base.
That base uses your federal net earnings from self-employment: net profit times 92.35%, the same figure Schedule SE starts from. $80,000 becomes $73,880, and 0.75% of that is $554.
| Tax | Rate | Applied to | 2026 tax |
|---|---|---|---|
| Ohio income tax | 0% after the deduction | $80,000 of business income | $0 |
| Westerville municipal | 2.00% | $80,000 of net profit | $1,600 |
| Westerville CSD | 0.75% | $73,880 of net earnings | $554 |
| Total state and local | 2.69% | $80,000 of profit | $2,154 |
Two thousand one hundred fifty-four dollars. That is genuinely cheap by national standards, and not one cent of it is withheld or billed to you in advance.
Who collects the city tax depends on the city
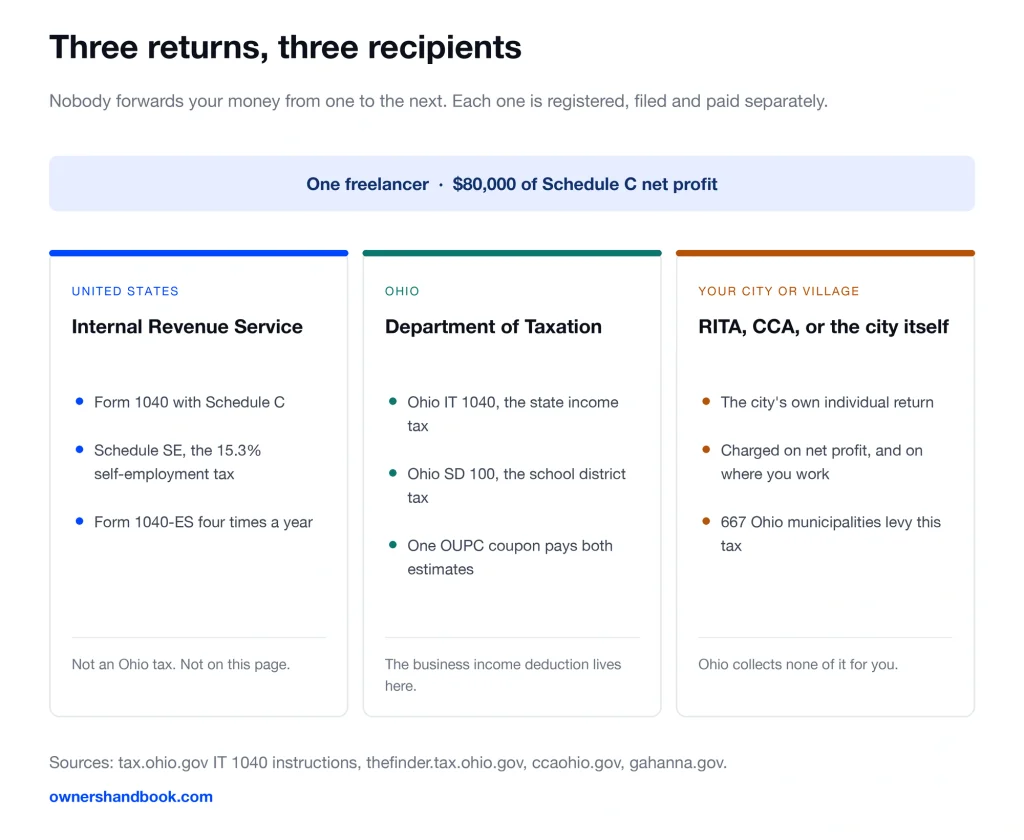
There are three possible answers, and you have to know which one is yours.
The Regional Income Tax Agency, RITA, administers income tax collection for member municipalities across the state. Gahanna is one, and its finance page names RITA as the agency that manages the city’s filings.
The Central Collection Agency, CCA, is part of the City of Cleveland’s Division of Taxation. Its 2026 rate table lists 46 jurisdictions it collects for, Cleveland among them.
Some cities do it themselves. Columbus runs its own Income Tax Division. Dublin runs its own Division of Taxation.
The state collects none of this. Paying Ohio does not pay your city, and your city sends nothing back to Ohio.
Working from home decides which city gets paid
Municipal income tax follows where the work is physically performed. For a freelancer at a desk in a spare bedroom, that is whichever city the bedroom sits in.
A client in Cleveland does not create a Cleveland obligation if you never worked in Cleveland. A week on site in Cleveland can.
CCA processes refunds for days worked outside the employment municipality, going back to tax year 2021, on a log of days plus supporting proof.
That refund process exists because the location of the work decides the tax, not the location of the client or the employer.
Keep a record of where you physically were on the days you billed. It is the only evidence anyone will accept two years later.
Three calendars, one of them a month early
Ohio wants estimated payments if your expected state tax, after credits and withholding, is more than $500. The dates are April 15, June 15, September 15, and January 15 of the following year.
The same Ohio Universal Payment Coupon pays both your income tax estimate and your school district estimate. One coupon, two taxes.
Municipal estimates run on those same four dates for individuals. CCA’s published calendar puts individual estimates on April 15, June 15, September 15, and January 15.
The exception is the municipal net profit return, which entity filers use. Its fourth quarter estimate is due December 15, a month before everyone else’s.
| Due date | Ohio IT 1040 and SD 100 | Your municipality |
|---|---|---|
| April 15, 2026 | Yes | Yes |
| June 15, 2026 | Yes | Yes |
| September 15, 2026 | Yes | Yes |
| December 15, 2026 | — | Net profit filers only |
| January 15, 2027 | Yes | Yes, individuals |
How to find your own municipality and district
The Department of Taxation runs an address lookup called The Finder. Type in your street address and it returns the tax jurisdictions that cover it.
Write down three things. Your municipality and its rate. Your school district’s name and four-digit number. Whether that district uses the traditional or the earned income base.
The Department also publishes two files you can read straight through. One is the municipal rate table. One is the list of school districts with an income tax, their 2026 rates, and which base each uses.
Then contact whoever collects for your municipality and register. Doing this in your first year costs an afternoon. Doing it after the letter arrives costs the penalty and the interest as well.
What Ohio does not charge you
There is no Ohio self-employment tax. Social Security and Medicare are federal programs, and Schedule SE goes to the IRS alone.
School district income tax is not municipal income tax. Paying one earns you no credit against the other, and CCA says so explicitly.
The quarterly estimated taxes guide covers the federal half of all this, and the general state tax guide covers what other states do. Ohio’s twist is that two of your three income taxes are local.
Frequently asked questions
I work from home in a township. Do I owe a municipal tax?
Townships are not municipalities, and the Department’s municipal rate table lists cities and villages. Check your address in The Finder anyway, because the Department publishes a separate rate table for JEDD and JEDZ districts.
My district has no income tax. Am I finished after the state and the city?
For the school district, yes. The Finder lists 614 Ohio school districts and only 214 of them levied an income tax as of January 2026.
Does the business income deduction lower my city and school district tax?
No. It is a line on the Ohio return. The school district base adds it straight back through modified adjusted gross income, and municipalities compute net profit under their own rules.
I moved mid-year. Which city and which district do I file for?
Both of each. CCA tells movers to allocate tax by the income actually earned while living in each municipality, and the SD 100 has a residency schedule that does the same job.
The city never sent me anything. Do I still owe it?
Yes. The obligation exists whether or not anyone wrote to you, and registering is on you rather than on the collector.
Is an LLC treated differently?
A single member LLC filing a Schedule C uses the individual municipal return, per CCA. An LLC taxed as a partnership or corporation files the net profit return instead, and that one’s fourth quarter estimate lands on December 15.
Sources
Ohio Department of Taxation, 2025 Ohio IT 1040 and SD 100 Instructions
Ohio Department of Taxation, School Districts With an Income Tax, Effective Calendar Year 2026
Ohio Department of Taxation, The Finder
https://thefinder.tax.ohio.gov
Ohio Department of Taxation, Ohio Municipal Income Tax Rate Table
https://thefinder.tax.ohio.gov/api/file-downloads/content?target=Muni%2FOHMuniRateTable.csv
Ohio Department of Taxation, School District Income Tax Rate Table
https://thefinder.tax.ohio.gov/api/file-downloads/content?target=SD%2FOHSDRateTable.csv
CCA Division of Taxation, Tax Rates
https://www.ccaohio.gov/tax-rates
CCA Division of Taxation, Individual FAQs
https://www.ccaohio.gov/faq/individual
CCA Division of Taxation, Business FAQs
https://www.ccaohio.gov/faq/business
CCA Division of Taxation, Municipal Income Tax Due Dates Calendar
https://www.ccaohio.gov/due-dates/municipal-income-tax-calendar
CCA Division of Taxation, Individual Filing Due Dates
https://www.ccaohio.gov/due-dates/individual-filing
City of Gahanna, Income Tax
https://www.gahanna.gov/163/Income-Tax
City of Dublin, Taxation