Form 8829, Line by Line: The Home Office Form Explained
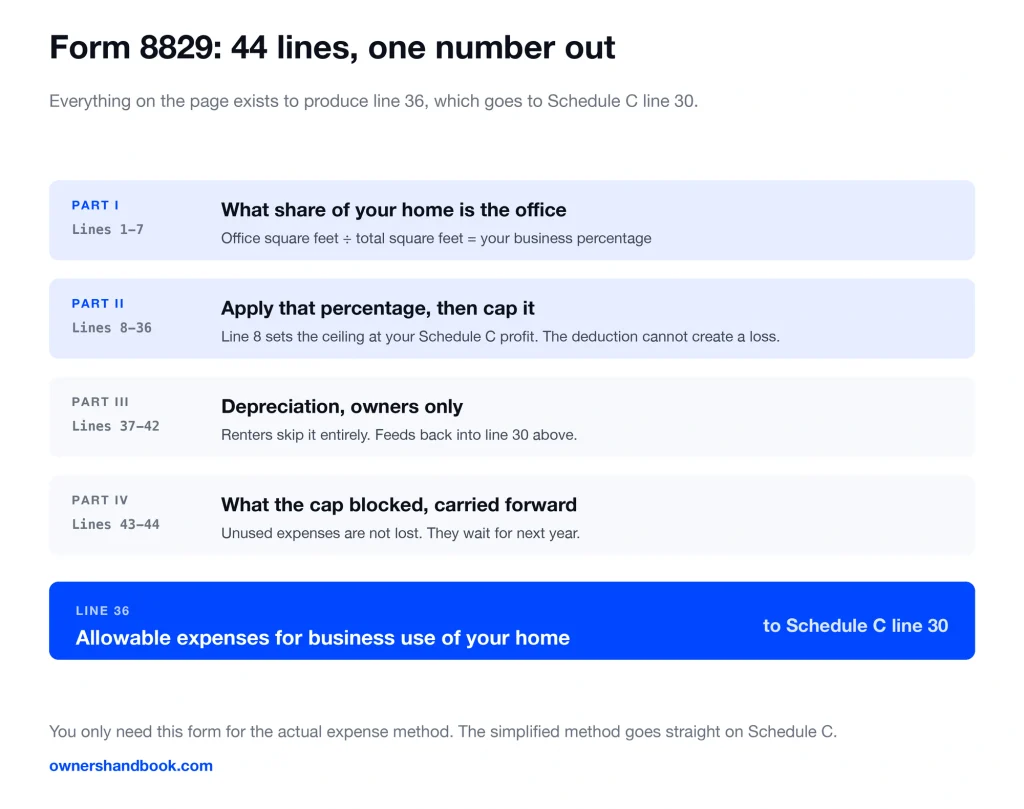
Form 8829 is one page and 44 lines, and it exists to turn what your home costs into one number on Schedule C line 30. Most of those lines are arithmetic. Four of them decide the answer.
You only need this form if you are using the actual expense method. The simplified method — square feet times $5, capped at 300 — is entered directly on Schedule C and skips this page entirely.
What the form is actually doing
Three things, in order.
Part I works out what share of your home is the office. That percentage drives everything below it.
Part II applies the percentage to what the home cost to run, then caps the result so the deduction cannot create a loss.
Parts III and IV handle depreciation if you own the place, and carry forward anything the cap blocked.
One number leaves the page: line 36, which goes to Schedule C line 30.
Part I: lines 1 through 7
| Line | What the form says | What to enter |
|---|---|---|
| 1 | Area used regularly and exclusively for business | Square feet of the office. Length times width |
| 2 | Total area of home | Finished living area. Use your lease or tax assessment |
| 3 | Divide line 1 by line 2, as a percentage | The business percentage |
| 4-6 | Daycare hours calculation | Skip unless you run a daycare |
| 7 | Business percentage | Same as line 3 for everyone but daycare |
Line 1 carries the whole exclusive-use test. The space has to be used only for business — a desk in a room where the family also watches television does not qualify, and putting the square footage on line 1 anyway is the most common way this form goes wrong.
Lines 4 through 6 exist for one situation. The form tells you directly: “For daycare facilities not used exclusively for business, go to line 4. All others, go to line 7.”
Part II: the two columns that confuse everyone
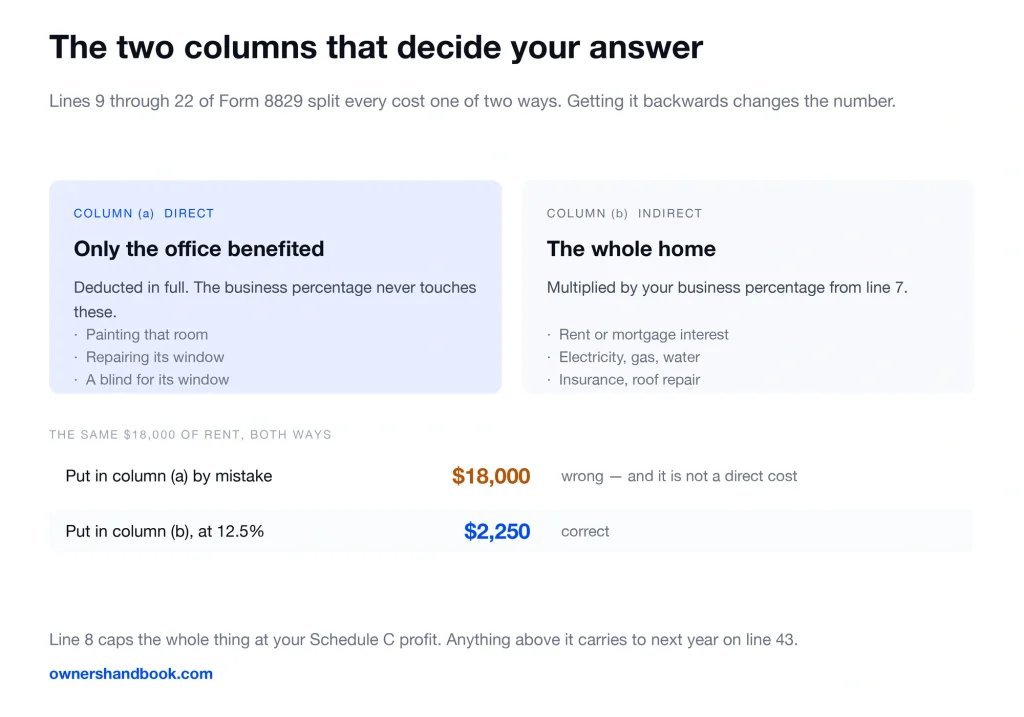
Lines 9 through 22 have two columns, and getting them backwards changes your answer.
**Column (a), direct expenses.** Costs that belong to the office alone. Painting that room. A repair to that room’s window. These are deducted in full — the business percentage never touches them.
**Column (b), indirect expenses.** Costs of running the whole home. Rent. Electricity. Insurance. These get multiplied by your business percentage from line 7.
So $600 to repaint the office is $600 in column (a). $18,000 of annual rent is $18,000 in column (b), and at 12.5% it becomes $2,250.
| What you paid | Column | Why |
|---|---|---|
| Painted the office | (a) direct | Only that room benefited |
| Fixed the office window | (a) direct | Same |
| Rent or mortgage interest | (b) indirect | The whole home |
| Electricity, gas, water | (b) indirect | The whole home |
| Homeowners or renters insurance | (b) indirect | The whole home |
| Roof repair | (b) indirect | The whole home benefits |
| New kitchen counter | Neither | No business use at all |
Line 8, and the limit that surprises people
Line 8 starts with Schedule C line 29 — your profit before the home office. That number is the ceiling.
The home office deduction cannot create or deepen a loss. If line 29 is $3,000 and your calculated home office expenses come to $4,500, you deduct $3,000 this year. The remaining $1,500 does not vanish; it lands on line 43 and carries to next year.
This catches people in slow years, and it is why the form has a Part IV at all.
The sequence that enforces it runs through lines 15, 27 and 28. Line 15 is what remains of your profit after mortgage interest and taxes. Line 27 takes “the smaller of line 15 or line 26” — the smaller of what you have left and what you spent. Line 28 is what remains for depreciation.
| Line | What it does |
|---|---|
| 8 | Your profit ceiling, from Schedule C line 29 |
| 15 | Profit left after mortgage interest and real estate taxes |
| 27 | Allowable operating expenses — the smaller of line 15 or line 26 |
| 28 | What is left for depreciation |
| 34 | Adds the three allowable pieces together |
| 36 | Your deduction. Goes to Schedule C line 30 |
A worked example, start to finish
A renter with a 150 square foot office in a 1,200 square foot apartment, $60,000 of profit, $18,000 of rent, $1,800 of utilities, $240 of renters insurance, and $600 spent painting the office.
| Line | Figure |
|---|---|
| 1. Office area | 150 |
| 2. Total home area | 1,200 |
| 3 and 7. Business percentage | 12.5% |
| 8. Profit from Schedule C line 29 | $60,000 |
| 18. Insurance, column (b) | $240 |
| 19. Rent, column (b) | $18,000 |
| 21. Utilities, column (b) | $1,800 |
| 22. Other, column (a) — the painting | $600 |
| 23. Column (b) total | $20,040 |
| 24. Line 23 (b) times 12.5% | $2,505 |
| 26. Column (a) plus line 24 | $3,105 |
| 27. Smaller of line 15 or 26 | $3,105 |
| 36. Deduction to Schedule C line 30 | $3,105 |
Against the simplified method — 150 square feet times $5 — the same office is worth $750. The gap is rent, which the simplified method never looks at.
Now run it again with $2,000 of profit instead of $60,000. Line 27 takes the smaller figure, so the deduction is $2,000, and $1,105 carries to next year on line 43.
Parts III and IV
Part III, lines 37 through 42, is depreciation, and it applies only if you own the home. You take the smaller of adjusted basis or fair market value, subtract the land, multiply by the business percentage, then by the depreciation percentage the instructions give.
Renters skip it entirely.
There is a consequence worth knowing before you start. Depreciation you claim on a home you own reduces your basis in it, which can mean tax when you sell. That is not a reason to skip the form, but it is a reason to keep the numbers.
Part IV is two lines. Line 43 carries unallowed operating expenses to next year. Line 44 carries unallowed casualty losses and depreciation. Both come from the profit cap.
What trips people up
Putting rent in column (a). It is an indirect expense. Column (a) is only for costs that benefited the office alone.
Claiming a room that is not exclusive. Line 1 asks for area used “regularly and exclusively.” A guest room that is an office four days a week fails.
Using the mortgage payment. Line 10 is deductible mortgage interest, not the payment. The principal portion is not an expense.
Forgetting the carryover. If the profit cap cut your deduction, line 43 is real money you can use next year. It only survives if you file the form again.
Filing 8829 with the simplified method. You cannot use both. Pick one per year, on that year’s original return.
Frequently asked questions
Do I need Form 8829 if I use the simplified method?
No. The simplified method is entered on Schedule C line 30 directly, using two square footage figures. Form 8829 exists only for the actual expense method.
Can I switch between the two methods?
Yes, year by year, on that year’s original return. What you cannot do is change the method for a year you already filed.
I rent. Do I skip Part III?
Yes. Depreciation applies to a home you own. Everything else on the form still applies, and rent goes on line 19 in column (b).
My business lost money. Is the form pointless?
No. Fill it in anyway. The deduction is limited to your profit, but line 43 carries the unused portion forward, and that carryover only exists if you filed.
Does claiming depreciation cause problems when I sell?
It reduces your basis, which can increase the gain. It is a real consideration for homeowners and worth discussing with a preparer before your first year of claiming it.
Sources
IRS, Form 8829
https://www.irs.gov/pub/irs-pdf/f8829.pdf
IRS, Instructions for Form 8829
https://www.irs.gov/pub/irs-pdf/i8829.pdf
IRS, Publication 587, Business Use of Your Home
https://www.irs.gov/pub/irs-pdf/p587.pdf
IRS, Home Office Deduction
https://www.irs.gov/businesses/small-businesses-self-employed/home-office-deduction
IRS, Instructions for Schedule C