What Freelancers Can Actually Deduct (and What They Cannot)
Two words decide every deduction: ordinary and necessary. Ordinary means people in your line of work commonly buy the thing. Necessary means it helps you do the work. Clear both and it comes off your income. Miss either and no receipt will save it.
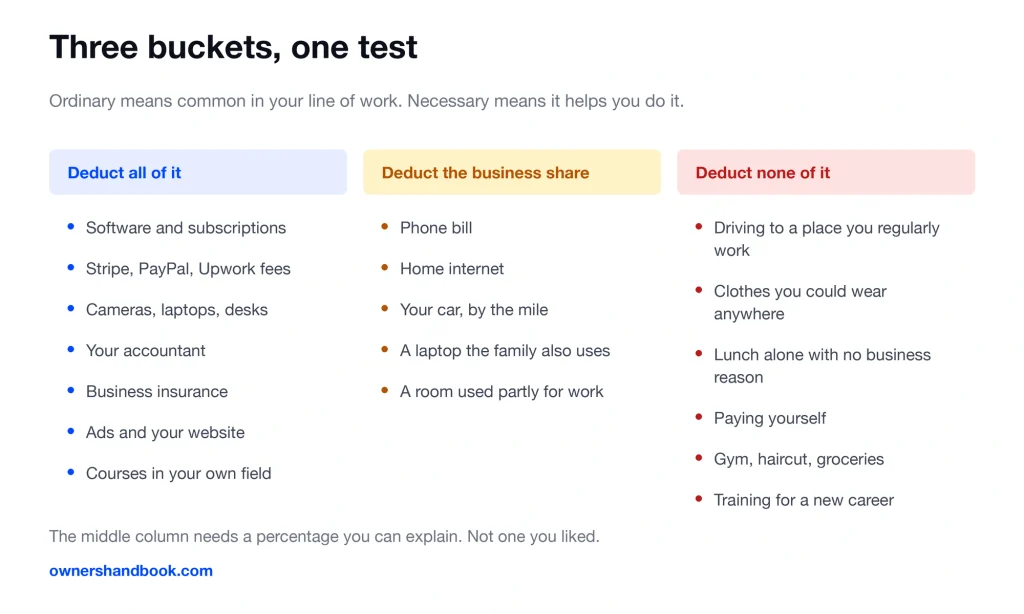
The test is two words
There is no master list of approved deductions. People go looking for one and never find it, because it does not exist.
What exists is a sentence in the tax code. A business can deduct expenses that are ordinary and necessary for carrying on that business.
Ordinary means common in your line of work. A photographer buying lenses is ordinary. A photographer buying a table saw is not.
Necessary means helpful and appropriate for the work. Not life-or-death. Just useful.
Learn to run this test yourself and you stop needing the list. You will also stop asking whether something is “a write-off,” which is the wrong question. The question is whether the money was spent to do the work.
Ordinary does not mean unavoidable
This is where people talk themselves out of real deductions.
Necessary has a plain-English meaning that is stricter than the tax meaning. In tax, an expense does not have to be indispensable. It has to be helpful and appropriate.
You could technically edit photos on a six-year-old laptop. Buying a faster one is still deductible. You could technically meet clients at a coffee shop. Renting a small studio is still deductible.
The test is not “could I have survived without it.” The test is “did I buy this to do the work.”
When something is part business and part personal
Most of what a freelancer buys sits in this middle zone, and the rule is the same everywhere: deduct the business share, leave the rest.
Your phone. If 60% of its use is work, deduct 60% of the bill.
Your internet. Same logic. A percentage, not the whole thing.
Your car. Business miles are deductible. The drive to the grocery store is not.
Your laptop, if the family uses it too. A percentage.
The percentage has to be something you can explain. Not a number you liked. If you say 60%, be ready to say why — a month of call logs, a look at your calendar, the split between work apps and everything else.
| What you bought | How much comes off |
|---|---|
| Software, platform fees, business insurance | All of it |
| Cameras, laptops, desks, your accountant | All of it |
| Phone, home internet, a shared laptop | The business share, as a percentage |
| Your car | Business miles only |
| Commuting, everyday clothes, lunch alone | None of it |
| Paying yourself, your gym, your groceries | None of it |
One shortcut that is not a shortcut: buying a second phone or a second laptop that only ever touches work. Then it is 100%, and there is nothing to estimate or defend.
Almost always yes
These clear the test for nearly everyone who bills for their own work.
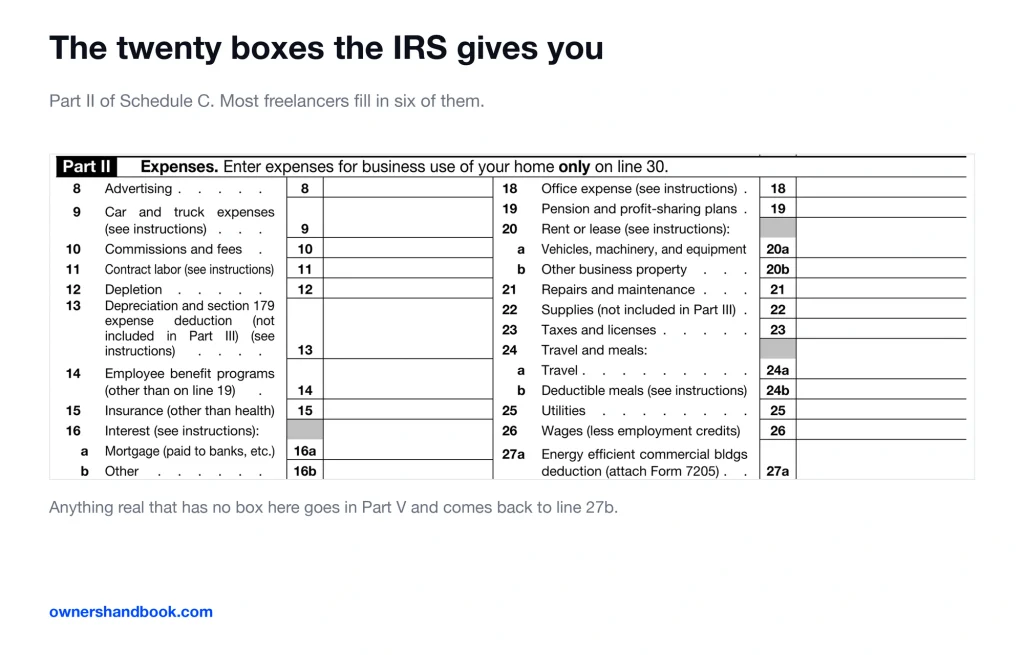
Software and subscriptions you use for the job. Design tools, accounting software, cloud storage, the domain name.
Payment processing and platform fees. Stripe’s cut, PayPal’s cut, what Upwork or Etsy keeps. This money never landed in your account, but it counted as your income, so it has to come back off as an expense.
Equipment. Computers, cameras, microphones, desks, chairs.
Professional services. Your accountant. A lawyer who reviewed a contract.
Insurance for the business. Liability, errors and omissions, equipment coverage.
Education that sharpens what you already do. A course, a conference, a book about your field.
Advertising. Your website, ads you ran, business cards.
Bank fees on a business account.
Four of these have enough moving parts to need their own page: the home office, the standard mileage rate, equipment over $2,500 under Section 179, and business meals. Each one is covered separately.
Contract labor. What you paid another freelancer to help. Pay one person $2,000 or more during 2026 and you also owe them a 1099.
Almost always no
These fail the test, and they fail it consistently.
Commuting. Driving from home to a place you regularly work is personal, not business. There is one important exception: if your home qualifies as your principal place of business, the drive from there to a client site is business mileage.
Ordinary clothing. If you can wear it anywhere else, it is not deductible. A suit for client meetings fails. A branded uniform or protective gear passes.
Meals you ate alone with no business purpose. A sandwich at your desk is lunch, not a deduction.
Meals do become deductible, usually at half, in two situations: there was a business purpose, or you were traveling away from home overnight for work.
Your own labor. You cannot pay yourself and deduct it. A sole proprietor’s profit is already their pay.
Personal life, generally. Your gym, your haircut, your regular clothes, your groceries. Being self-employed does not convert your household into a business.
Education that qualifies you for a new career. Sharpening existing skills is deductible. Training into a different profession is not.
Fines and penalties. Including the interest the IRS charges you.
A deduction is not a refund
This one costs people money in the other direction — they overspend chasing write-offs.
A deduction does not give you the dollar back. It removes the dollar from the income you are taxed on. What you get back is the tax you would have paid on it.
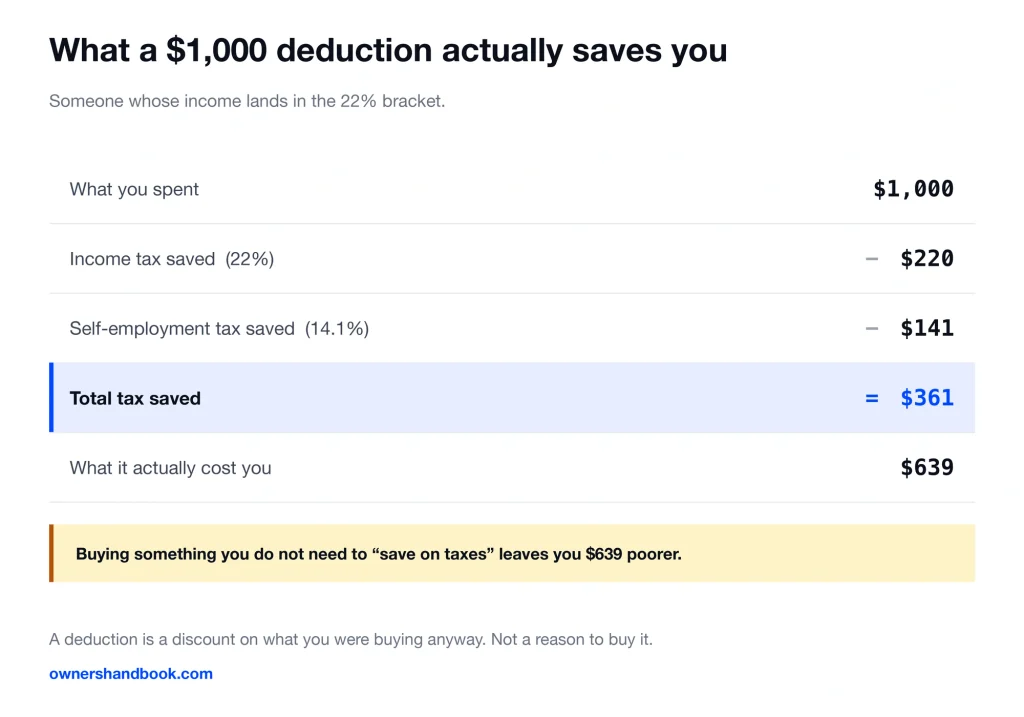
So a $1,000 expense, for someone whose income lands in the 22% bracket, saves roughly $360. Around $220 in income tax and around $141 in self-employment tax, because a Schedule C deduction comes off both.
| $1,000 spent on the business | Amount |
|---|---|
| Income tax saved, 22% bracket | $220 |
| Self-employment tax saved, 14.1% effective | $141 |
| Total tax saved | $361 |
| What the purchase actually cost you | $639 |
Second-order effects nudge that number a little in both directions, but the shape of it does not change. You get back a fraction, not the whole thing.
Which means buying something you do not need in order to “save on taxes” leaves you about $640 poorer. The deduction is a discount on things you were going to buy anyway. It is not a reason to buy them.
What a record actually has to show
Three things: what you spent, when, and why it was business.
The first two are on the receipt. The third one almost never is, and it is the one that gets challenged.
So write it down at the time.
On a meal receipt, who you ate with and what you discussed. On a mileage log, where you drove and for whom. On a $400 charge from an electronics store, what it was and what it is for.
A photo of the receipt is fine. The IRS accepts digital copies.
What does not work is reconstruction. A mileage log written in April from memory is not a record, and it is the first thing to fall apart if anyone asks.
Keep it all for three years after you file, and longer if the year was unusual. What to keep, and for how long, has its own page.
If this is your first year and none of it is set up yet, there is a checklist that walks the whole year in order.
Frequently asked questions
Do I need a receipt for everything?
Keep one whenever you can. Bank and card statements help but they show the amount, not the purpose, and purpose is what matters.
Can I deduct something I bought before I started the business?
Equipment you already owned and then converted to business use can be deducted based on its value at the time you converted it, not what you originally paid. Startup costs before you opened have their own rules.
What if I only work part time?
The test does not change. A side business deducts its ordinary and necessary expenses exactly the way a full-time one does.
Does a bigger deduction make an audit more likely?
Deductions that are wildly out of line with your income can draw attention. Legitimate ones, properly recorded, are not something to avoid. Skipping real deductions to look safe is just paying extra tax.
Can I deduct the whole cost of a laptop in the first year?
Usually yes. If the invoice is $2,500 or less, the de minimis safe harbor lets you expense it outright instead of spreading it over several years. Above that you are into Section 179 or depreciation, and the choice has to be made on the return itself.
Do deductions reduce self-employment tax too?
Schedule C deductions do, because they lower the profit that self-employment tax is calculated on. Some other deductions, like health insurance, come off later and do not.
Sources
IRS, Deducting Business Expenses
https://www.irs.gov/businesses/small-businesses-self-employed/deducting-business-expenses
IRS, Publication 535, Business Expenses
https://www.irs.gov/forms-pubs/about-publication-535
IRS, Publication 463, Travel, Gift, and Car Expenses
https://www.irs.gov/publications/p463
IRS, Instructions for Schedule C
https://www.irs.gov/instructions/i1040sc
IRS, Recordkeeping
https://www.irs.gov/businesses/small-businesses-self-employed/recordkeeping