Hairstylist and Booth Renter Taxes: You Are a Tenant, Not a Contractor
If you rent a chair, the salon is your landlord. It is not your client, not your employer, and not the company that pays you. You collect from the people whose hair you cut, and the salon collects rent from you.
That one fact changes everything about your January paperwork — and it is the fact that stylists most often get wrong, because the word “1099” gets used for two completely different arrangements.
Here is the difference, and what each of the three situations actually produces.
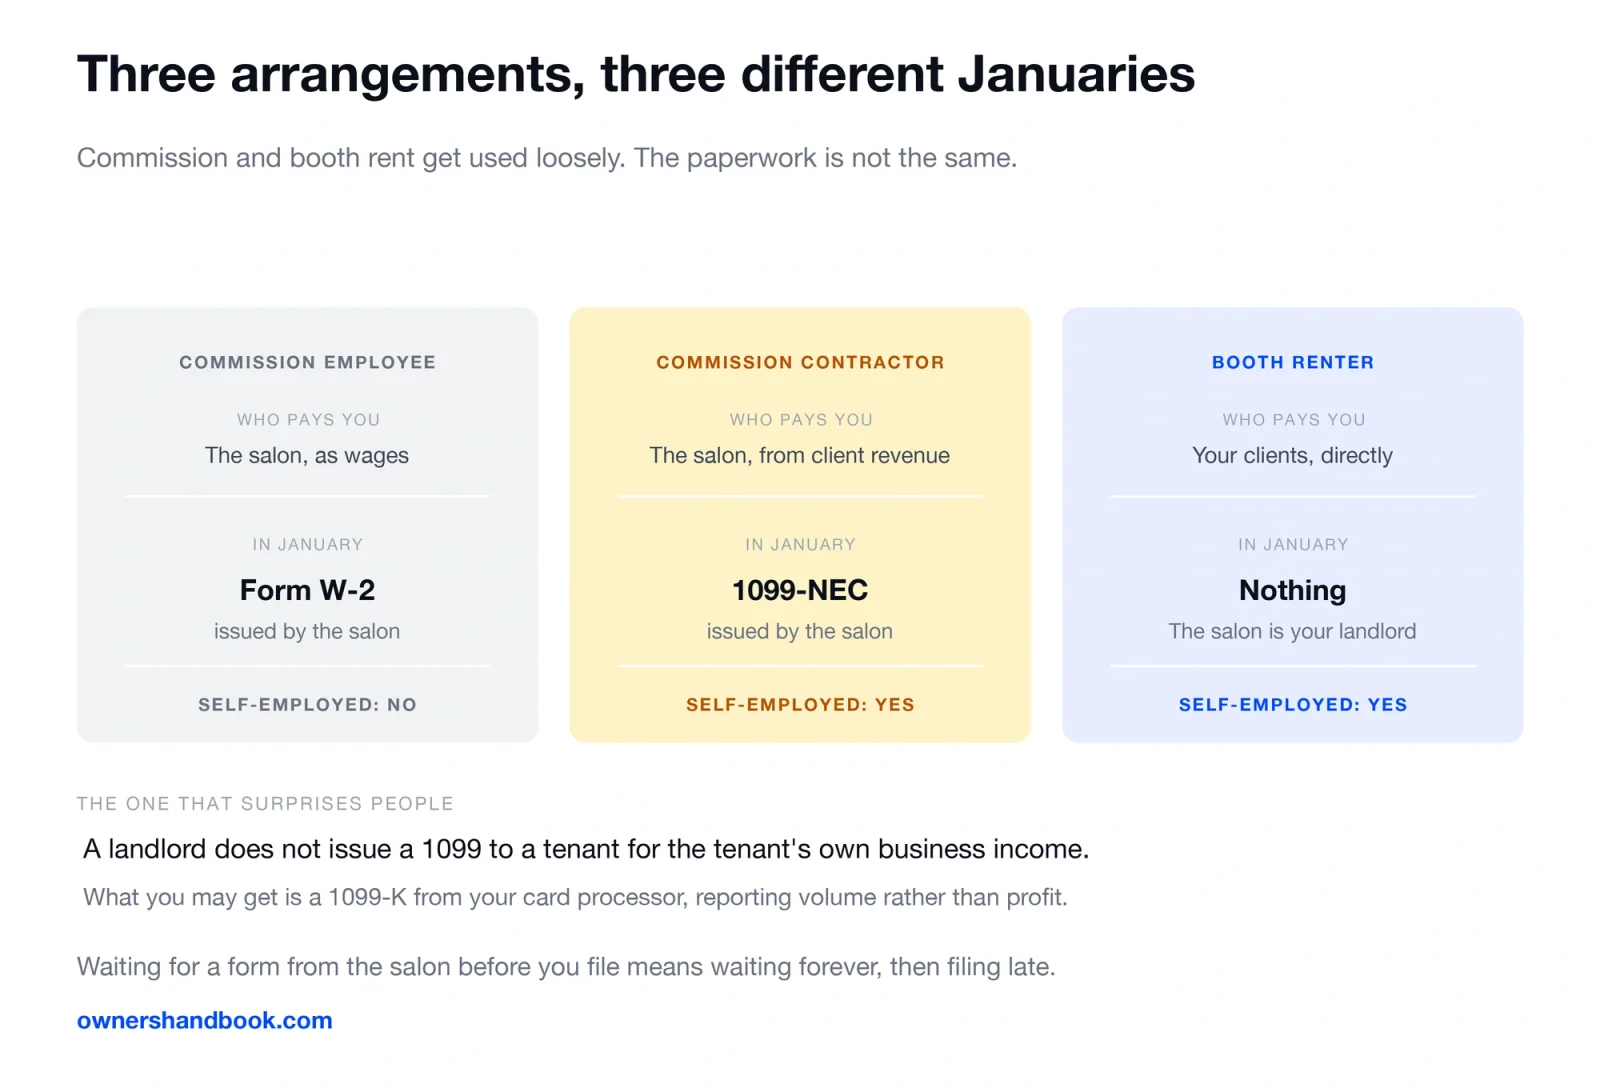
Three arrangements, three sets of paperwork
Stylists use “commission” and “booth rent” loosely, and threads full of conflicting advice are the result. The three structures are genuinely different.
| Arrangement | Who pays you | What you get in January | Self-employed |
|---|---|---|---|
| Commission employee | The salon, as wages | Form W-2 | No |
| Commission contractor | The salon, from client revenue it collected | Form 1099-NEC from the salon | Yes |
| Booth or chair renter | Your clients, directly | Nothing from the salon | Yes |
A booth renter receives no 1099-NEC from the salon, and that is not an oversight. The salon never paid you anything — you paid the salon. Money flows the other way. A landlord does not issue a 1099 to a tenant for the tenant’s own business income.
If you are a booth renter and you are waiting for a form from the salon before you file, you will wait forever and then file late.
What you may receive is a Form 1099-K from whichever card processor handles your payments — Square, Stripe, a salon-provided terminal in your own name. That reports card volume, not profit, and it is a different animal. Our comparison of 1099-NEC and 1099-K sets out which reports what.
One more thing changed. The 1099-NEC reporting threshold rose to $2,000 for tax years beginning after 2025, up from $600. A commission contractor who earned $1,800 from a salon in 2026 now gets no form at all. The income is still reportable — the threshold governs the salon’s filing duty, not your obligation.
The commission contractor’s warning
If you are treated as a contractor but the salon sets your hours, sets your prices, supplies your product, and tells you when to take lunch, the classification may be wrong. Worker classification turns on control, not on the label in the agreement.
That is a real dispute worth raising, but it does not change your filing this year: if you received a 1099-NEC, you report it on Schedule C and pay self-employment tax at 15.3% on the profit, and you make quarterly estimated payments because nobody is withholding for you.
The genuine booth renter has no such ambiguity. You are a business with a lease.
Tips now carry a deduction, and it reaches the self-employed
This is new, and it applies to people in your chair.
Section 224 created a deduction for qualified tips. The IRS states the eligibility plainly:
Employees and self-employed individuals may deduct qualified tips received in occupations that are listed by the IRS as customarily and regularly receiving tips on or before December 31, 2024.
The self-employed are inside it, not outside it. That is unusual and it is the point.
Treasury and the IRS published final regulations on April 13, 2026, effective June 12, 2026, listing the qualifying occupations by code. They are grouped into categories, and one of them is the 600s, Personal Appearance and Wellness:
| Code | Occupation |
|---|---|
| 601 | Skincare Specialists |
| 602 | Massage Therapists |
| 603 | Barbers, Hairdressers, Hairstylists, and Cosmetologists |
| 604 | Shampooers |
| 605 | Manicurists and Pedicurists |
| 606 | Eyebrow and Eyelash Technicians |
| 607 | Makeup Artists |
| 608 | Exercise Trainers and Group Fitness Instructors |
| 609 | Tattoo Artists and Piercers |
| 610 | Tailors |
| 611 | Shoe and Leather Workers and Repairers |
Code 603 is the one most readers of this post sit in. Note 602 and 609 as well — massage therapists and tattoo artists are on the same list, and as the last section explains, they usually rent their space the same way.
Two limits apply specifically to self-employed claimants. The IRS states:
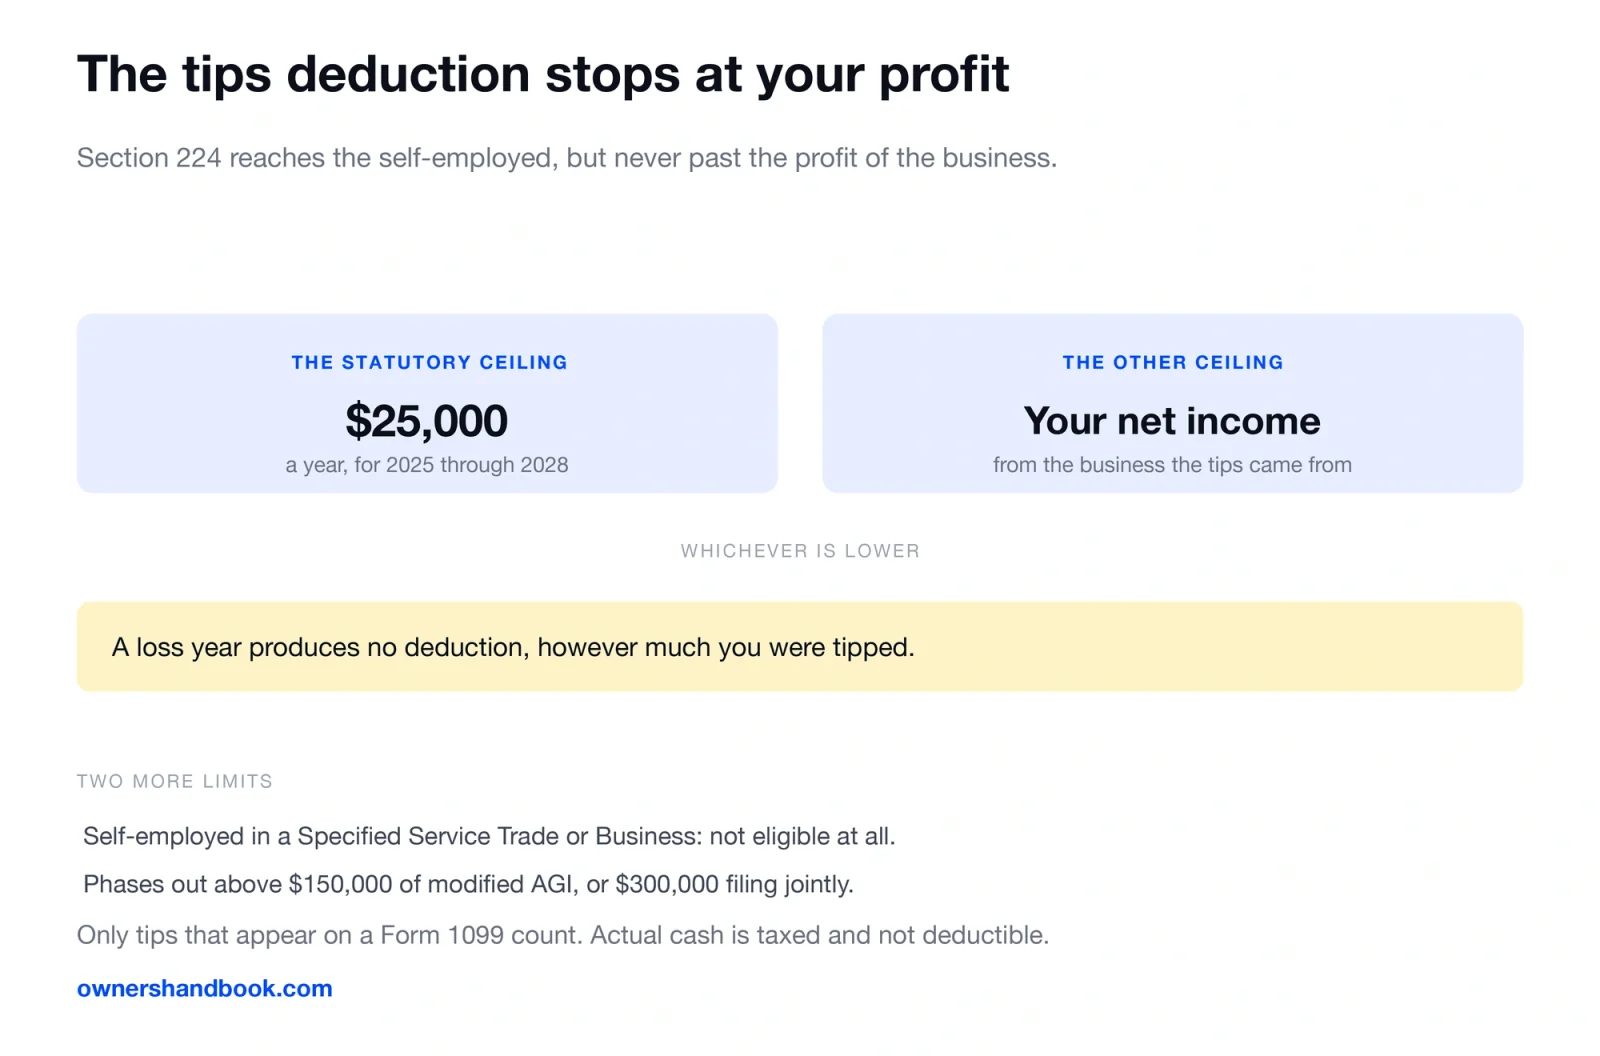
For self-employed, deduction may not exceed individual’s net income (without regard to this deduction) from the trade or business in which the tips were earned.
A loss year produces no deduction regardless of how much you were tipped. But read “net income” carefully, because it is narrower than the profit on your Schedule C. The Form 1040 instructions spell out what comes off first:
… deductions allocable to that trade or business, including the deductible part of self-employment tax; the deduction for contributions to self-employed SEP, SIMPLE, and qualified plans; and the self-employed health insurance deduction, but not including the deduction for qualified tips.
Three of those four sit on Schedule 1, not on Schedule C, so they reduce the tips ceiling without ever appearing in your business profit. The consequence is concrete: funding a retirement plan lowers the tips deduction you are allowed. Our comparison of a solo 401(k) and a SEP IRA covers those contributions, and health insurance for the self-employed covers the premium deduction.
And an exclusion that is easy to miss:
Self-employed individuals in a Specified Service Trade or Business (SSTB) under section 199A are not eligible.
Whether a particular trade is an SSTB is its own determination, and the categories include health services. If you are a massage therapist rather than a stylist, this is worth settling before you rely on the deduction.
The IRS states a maximum annual deduction of $25,000, applying for 2025 through 2028, phasing out above $150,000 of modified adjusted gross income, or $300,000 for joint filers. Those figures come from the IRS page cited in the sources below. They sit in a provision that is new and being implemented in stages, so confirm them against current IRS guidance for the year you are filing before you plan around them.
The practical consequence is narrower than it first looks, and it is the part most coverage gets wrong. For a self-employed claimant the deduction is built from Forms 1099, not from your own log. The Form 1040 instructions for Schedule 1-A say so directly:
Only amounts that appear in the aggregate on Forms 1099 can be considered qualified tips. Any “cash tips” received … in actual cash that don’t appear on Form 1099-K cannot be included in the deduction.
So a tip handed to you in cash, which no processor ever saw, is taxable income and not a deductible tip. Schedule 1-A has columns for Form 1099-NEC box 1, Form 1099-MISC box 3, and Form 1099-K box 1a, and nothing else.
Your own records still matter, but for a different job: they establish how much of a 1099 total was tips rather than service revenue. A log substantiates the tip share of a reported figure. It cannot create a deduction where no 1099 exists. See record keeping for what the log needs to show.
Booth rent is deductible, and it is your largest line
Rent paid for business space is an ordinary business expense. Weekly chair rent of $250 is $13,000 a year, and it belongs on Schedule C in full.
Two things follow that stylists often miss.
If you pay that rent in the course of your trade or business to an individual or a partnership rather than to a corporation, you may be the one with a filing obligation — rents of the threshold amount or more are reported on Form 1099-MISC, box 1, not 1099-NEC. Many salons are corporations, which are generally exempt, so check the W-9 before assuming either way.
And get the lease in writing. A booth rental agreement stating that you set your own hours, set your own prices, keep your own clients and buy your own product is the document that establishes you are a tenant rather than a misclassified worker.
Product, tools, and the line that matters
Not everything you buy is deducted the same way, and the distinction is about who ends up with the bottle.
| What you bought | How it is treated |
|---|---|
| Colour, developer, bleach, shampoo used on clients | Supplies — deduct in the year used |
| Retail product sold to clients | Inventory — deducted as cost of goods sold when sold |
| Shears, clippers, dryers, chair | Equipment — see writing off equipment |
| Capes, foils, towels, gloves | Supplies |
| Licence renewal, continuing education | Deductible |
| Liability insurance | Deductible |
| Booking software, card processing fees | Deductible |
Backbar versus retail is the line. Product you apply to a client is a supply consumed by your service. Product you sell off the shelf is stock you bought to resell, and it is not deducted when you buy it — it is deducted when it leaves the shelf. Shears at a few hundred dollars’ worth of investment are usually deductible in the year of purchase under the expensing rules, but they are a different category again.
Retail sales also bring sales tax into your life, which services often do not. Our guide to sales tax for freelancers covers registration and collection, and freelance tax deductions covers the rest of the list.
The same structure, different chair
Booth rental is not a hairdressing peculiarity. The arrangement — you rent space, you keep your clients, you collect directly, the owner is your landlord — is standard across several trades.
Tattoo artists renting a station, massage therapists renting a treatment room, nail technicians renting a table, and estheticians renting a suite are all in the identical tax position. No 1099-NEC from the owner. Rent deductible. Schedule C. Self-employment tax. Possibly a 1099-K from the processor. And, per the table above, all of them appear on the tipped occupations list.
If a colleague in a different trade tells you what their accountant said, it probably does apply to you.
Frequently asked questions
I rent a booth and got no 1099. Do I still file?
Yes. You report your actual gross receipts on Schedule C whether or not any form was issued. Forms are informational; the obligation is on the income.
I am a commission stylist with a 1099-NEC. Am I a booth renter?
No. Those are opposite arrangements. You were paid by the salon; a booth renter pays the salon. Do not apply booth rent advice to your situation.
Can I deduct booth rent if I also rent a chair elsewhere one day a week?
Yes. Both are business premises costs. Keep the agreements and the payment records for each.
Does the tips deduction reduce my self-employment tax?
It is an income tax deduction. Self-employment tax is computed on net earnings from self-employment, which this deduction does not reduce.
What about tips left in cash?
Reportable as income, and not deductible. The Form 1040 instructions limit qualified tips for a self-employed claimant to amounts appearing in the aggregate on Forms 1099, so actual cash that no processor reported is taxed and gets no deduction. The absence of a card trail does not make cash tips untaxed, and it does not make them deductible either.
I rent a room and also sell retail. Do I need a separate registration?
Probably, for sales tax. Selling tangible goods is a different activity from performing services, and most states treat them differently.
Sources
IRS, One Big Beautiful Bill Act: Tax deductions for working Americans and seniors
Electronic Code of Federal Regulations, 26 CFR § 1.224-1
https://www.ecfr.gov/current/title-26/section-1.224-1
Federal Register, Occupations That Customarily and Regularly Received Tips; Definition of Qualified Tips
IRS, Instructions for Forms 1099-MISC and 1099-NEC
https://www.irs.gov/instructions/i1099mec
IRS, About Schedule C (Form 1040), Profit or Loss From Business
https://www.irs.gov/forms-pubs/about-schedule-c-form-1040
IRS, Instructions for Form 1040, Schedule 1-A
https://www.irs.gov/pub/irs-pdf/i1040gi.pdf
IRS, Occupations That Customarily and Regularly Received Tips on or Before Dec. 31, 2024