Indiana’s Flat Rate Is Low. Every County Adds Its Own.
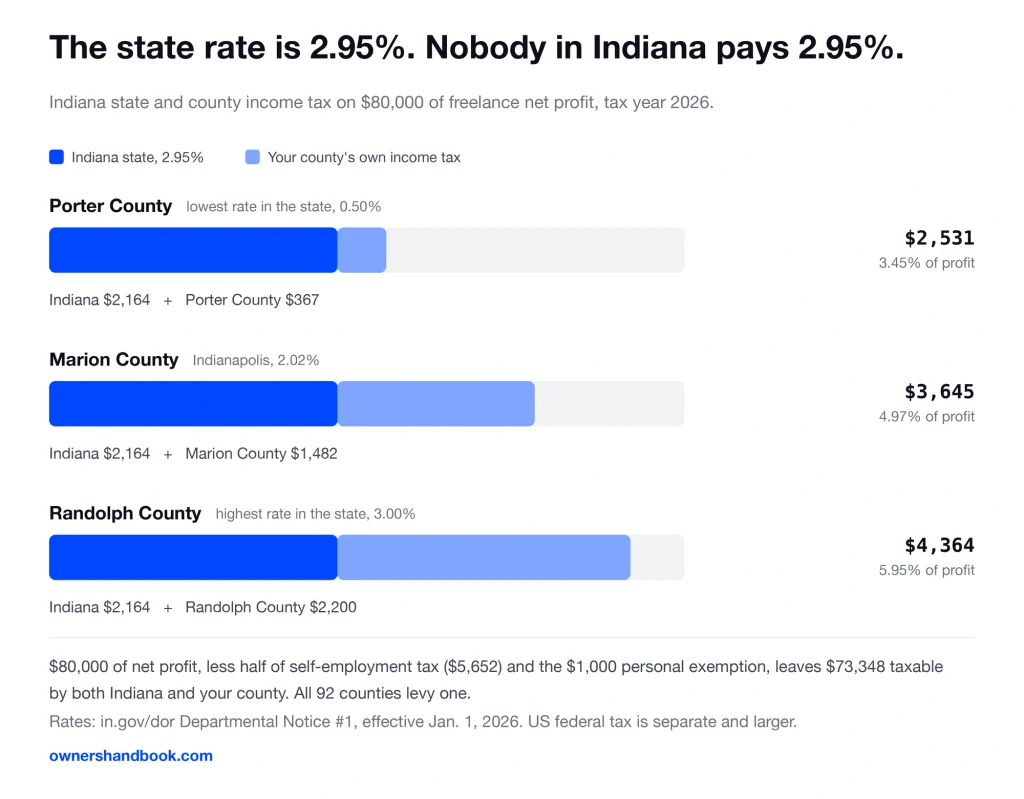
Indiana taxes your freelance profit at a flat 2.95% in 2026. Every one of its 92 counties then adds an income tax of its own. In Marion County, where Indianapolis sits, that second rate is 2.02%, so the real number is 4.97%.
On $80,000 of net profit that comes to roughly $3,645 in Indiana state and county tax. In Porter County, which charges 0.5%, the same freelancer pays about $2,531.
All of this is Indiana state and county tax sitting on top of United States federal tax. It is an addition to the federal bill, not a replacement for it.
Nobody in Indiana pays only the state rate
The Department of Revenue puts the 2026 individual adjusted gross income tax rate at 2.95%, and says it adjusts to 2.90% in 2027. It is flat. There are no brackets.
That 2.95% is the number the low-tax-state rankings quote. It is also a rate no Indiana resident actually pays.
Every county levies a local income tax, called LIT — a single county rate applied to the same income the state taxes. Bulletin #32 states that all counties in Indiana have enacted one.
So the honest Indiana rate is 2.95% plus whatever your county charges. That second piece ranges from 0.5% to 3%.
The county spread is wider than the state rate itself
Departmental Notice #1 is the list. The Department reissues it whenever counties move their rates, and the January 2026 edition carries what is in force for this tax year.
Porter County is the lowest at 0.5%. Randolph County is the highest at 3%, which is more than the state rate on its own.
Marion County sits at 2.02%. Hamilton County, the suburb north of Indianapolis that people move to, is 1.1%.
| County | County rate, 2026 | Combined with the 2.95% state rate |
|---|---|---|
| Porter, lowest in the state | 0.50% | 3.45% |
| Hamilton | 1.10% | 4.05% |
| Allen, Fort Wayne | 1.59% | 4.54% |
| Marion, Indianapolis | 2.02% | 4.97% |
| Monroe, Bloomington | 2.14% | 5.09% |
| Randolph, highest in the state | 3.00% | 5.95% |
The spread between the cheapest and the most expensive county is 2.5 points. The entire state rate is 2.95 points. Your county is nearly as big a decision as the state.
$80,000 of profit, county by county
Start with $80,000 of net profit on your Schedule C, the federal form where a sole proprietor reports business income and expenses.
Deduct half your self-employment tax first. On $80,000 that half is $5,652, and because it comes out before federal adjusted gross income, it lowers your Indiana income too.
Bulletin #32 lists one-half of self-employment tax among the deductions that apply to county tax as well, so it works on both halves of the Indiana bill.
Subtract Indiana’s $1,000 personal exemption and you are taxed on $73,348.
The state takes 2.95% of that, which is $2,164. Marion County takes 2.02% of the same figure, another $1,482. Combined, $3,645.
In Porter County the county share is $367 instead of $1,482. Same profit, same state return, $1,115 less.
That is not a rounding difference. It is decided entirely by which side of a county line you were sleeping on, on one particular morning.
January 1 decides your county for the entire year
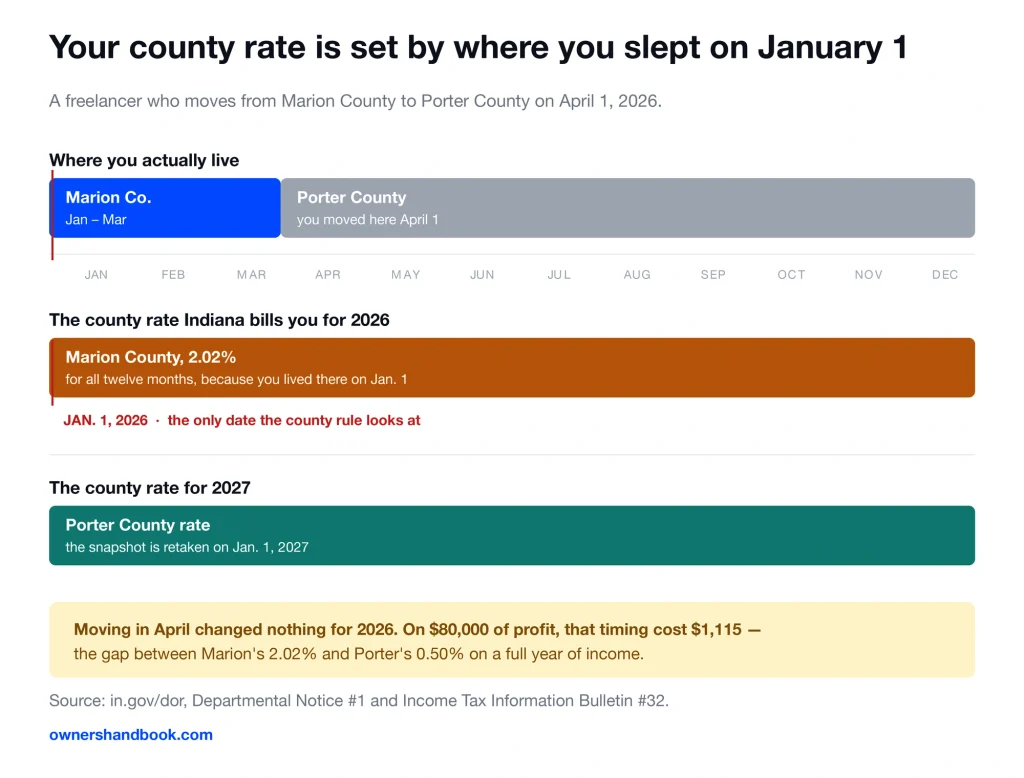
Your county rate is fixed by where you lived on January 1 of the tax year. Move in February and nothing changes until the following January 1.
Departmental Notice #1 says it directly. Both the county of residence and the county of principal business or employment are determined on January 1 of the calendar year.
Bulletin #32 goes further. Any change in your county during the year will not affect the county for which you are liable.
There is a second half of the rule aimed at self-employed people. If you live outside Indiana, your county is wherever your principal place of business sat on that same January 1.
This is where movers get caught. You leave Marion County in March, file the following April, and owe Marion’s 2.02% on the whole prior year anyway.
It cuts the other way too. Move into an expensive county in February and you finish the year at your old, cheaper rate.
It is one return with a separate schedule
You file Form IT-40 as a full-year Indiana resident. The county tax is not a second return to a second government.
It goes on Schedule CT-40, the County Tax Schedule for Indiana Residents. The Department lists CT-40 among the schedules you must include with the IT-40.
You enter your county, its rate, and your income. The result carries back onto the IT-40, and you pay one combined amount.
Payment runs through INTIME, the Department’s online portal, or by mail.
Four dates, a $1,000 threshold, and Form ES-40
Indiana calls its system pay-as-you-go. If you expect to owe $1,000 or more in state and county tax that withholding will not cover, the state wants quarterly estimated taxes.
The dates copy the federal ones exactly: April 15, June 15, September 15, and January 15 of the following year.
Pay through INTIME, or mail Form ES-40, the estimated tax payment voucher, with a check.
| Rule | What it means |
|---|---|
| Under $1,000 owed after withholding | No estimated payments required |
| 90% of this year’s tax | Requires forecasting your year accurately |
| 100% of last year’s tax | Safe harbor. Easiest one to hit. |
| 110% of last year’s tax | If federal AGI is over $150,000, or $75,000 filing separately |
| Miss an installment | 10% penalty on the underpayment, for that period |
The 10% is worth pausing on. Indiana charges a flat penalty of 10% of the underpayment for each installment period, rather than interest that accrues by the day.
If your income is lumpy, Schedule IT-2210A lets you annualize — match each payment to when the money actually arrived instead of splitting the year into four equal parts.
What Indiana does not give you
There is no Indiana standard deduction. There is no state version of the federal qualified business income deduction either, because Indiana starts from federal adjusted gross income and QBI is subtracted below that line.
What you get instead are exemptions. Departmental Notice #1 puts them at $1,000 per personal exemption for 2026, $1,500 per qualifying dependent, and $3,000 per adopted child.
Some federal deductions have to be added back on Schedule 1 of the IT-40. Ordinary business expenses are not among them, because they already reduced your profit before any of this begins.
And there is no state self-employment tax. Indiana does not run one, and neither does anywhere else. Social Security and Medicare go to the IRS alone.
The federal bill is still the larger one
On $80,000 of net profit the federal self-employment tax by itself is $11,304, before a single dollar of federal income tax. Indiana’s $3,645 is under a third of that.
That is the right way to read Indiana’s rate. Real, low, and not the thing that will catch you out.
The general state tax guide covers how other states handle this, and the quarterly estimated taxes guide covers the federal half. If you have never sent a payment before, how to pay estimated taxes walks through the mechanics.
Frequently asked questions
I moved from Marion County to Hamilton County in June. Which rate do I use?
Marion’s, for the entire year. Your county is fixed by where you lived on January 1, and Hamilton’s cheaper rate does not start until the following January 1.
I live out of state but all my work happens in an Indiana county. Do I owe county tax?
Likely yes. If your principal place of business is in an Indiana county, the income derived from that county is taxed at the same rate residents pay. Reciprocal agreements between states do not cover county tax.
Does Indiana charge self-employment tax?
No. Social Security and Medicare are federal, and Schedule SE goes to the IRS. Indiana taxes your profit as income, and your county then taxes the same figure again.
Do I file a separate county return?
No. Schedule CT-40 attaches to your Form IT-40. One return, one payment, two rates.
My profit was $9,000 this year. Do I still need quarterly payments?
Probably not. The trigger is owing $1,000 or more in state and county tax not covered by withholding, and at a combined 4.97% that takes roughly $20,000 of taxable income to reach.
Where do I look up my own county rate?
Departmental Notice #1 on the Department of Revenue site. It lists all 92 counties with a code and a rate, and it is reissued whenever a county changes.
Sources
Indiana Department of Revenue, Rates, Fees & Penalties
https://www.in.gov/dor/resources/tax-rates-and-reports/rates-fees-and-penalties
Indiana Department of Revenue, Departmental Notice #1, Effective Jan. 1, 2026
https://www.in.gov/dor/files/reference/dn01.pdf
Indiana Department of Revenue, Income Tax Information Bulletin #32, General Information on Local Income Taxes
https://www.in.gov/dor/files/ib32.pdf
Indiana Department of Revenue, Estimated Payments
https://www.in.gov/dor/i-need-to/make-a-payment/estimated-payments
Indiana Department of Revenue, Current Year Individual Tax Forms
https://www.in.gov/dor/tax-forms/individual/current
Indiana Department of Revenue, Individual Income Tax Overview
https://www.in.gov/dor/i-am-a/individual/individual-income-tax-overview
IRS, Self-Employment Tax