Do You Have to File? The $400 Rule for Self-Employed Americans
If your net self-employment earnings for 2026 are $400 or more, you must file a US federal tax return. That threshold sits far below the standard deduction, and it catches people who earned almost nothing.
Everything on this page is United States federal tax, for people filing a US return. Your state may have its own separate rule.
This page answers whether you file. How much to set aside from each payment is a different question, and the self-employment tax article covers that math in full.
Two thresholds that get confused
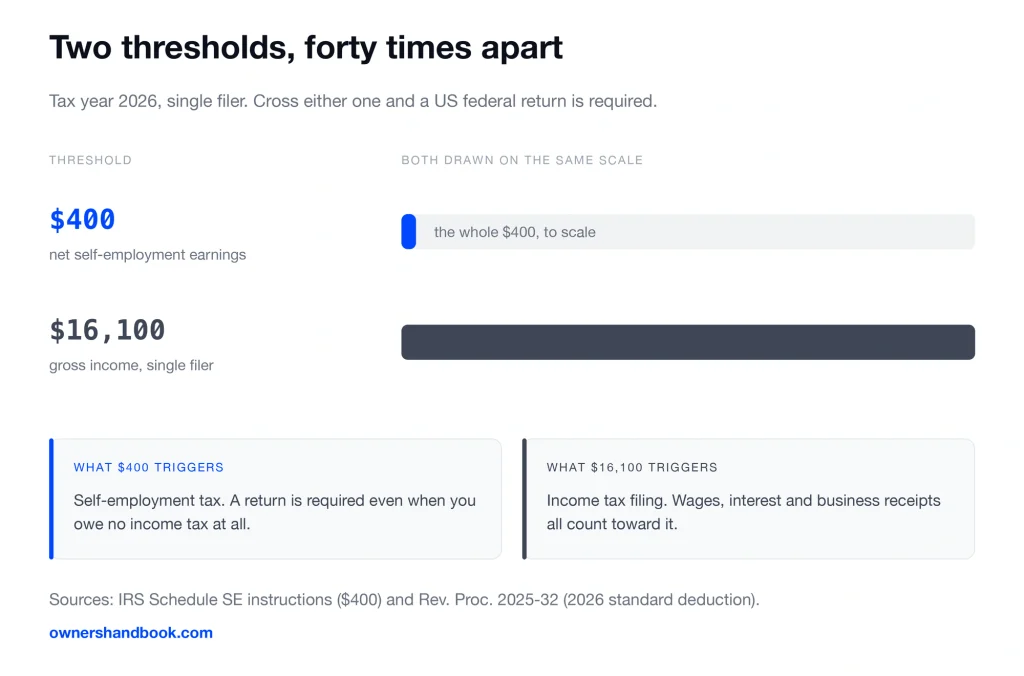
There are two numbers, and they answer two different questions.
The $400 one exists because of self-employment tax, the Social Security and Medicare tax you owe as your own employer. Reach $400 in net earnings and a return is required.
The other is the standard deduction, $16,100 for a single filer in 2026. That number is about income tax, and it is forty times higher.
Either one can force a return. You only have to cross one of them.
The $400 rule, in dollars
Net earnings means revenue minus business expenses. Not what clients paid you.
You earned $2,600 designing logos and spent $1,100 on software and a monitor. Net earnings: $1,500. You file.
You earned $1,900 and spent $1,600. Net earnings: $300. The $400 rule does not reach you.
The line the IRS actually tests is line 4c of Schedule SE, the form where self-employment tax is calculated. That line is your Schedule C net profit multiplied by 92.35%.
That multiplier matters right at the edge. A net profit of $433 becomes $399.88 on Schedule SE, which is under the line. At $434 of profit you cross it.
The $400 is a full-year total across everything you did for yourself. Three clients, a weekend market stall, and one afternoon of consulting all get added together first.
There is a second, much smaller trigger. Church employee income of $108.28 or more requires the same return, and that applies if a church pays you without withholding Social Security and Medicare tax.
What crossing $400 actually costs
Once you are over, self-employment tax is 15.3% of that 92.35% figure.
Earn $410 net for the entire year and you owe about $58. Small, and still a required return.
Earn $4,000 net and it is about $565. Earn $12,000 and it is about $1,696.
None of that is income tax. If $12,000 is your only income, the standard deduction erases your income tax completely, and the $1,696 is still owed before any credits.
That is the part people find unfair, and it is also the part that makes the $400 rule matter.
One consolation. Half of whatever self-employment tax you pay comes back as a deduction against your income tax, which softens the bill once your income is large enough to owe any.
The standard deduction threshold
The other trigger is gross income, and the number tracks the standard deduction for your filing status.
| Filing status | 2026 standard deduction |
|---|---|
| Single | $16,100 |
| Married filing jointly | $32,200 |
| Head of household | $24,150 |
| Married filing separately | $16,100 |
| Dependent | Greater of $1,350 or earned income plus $450 |
These come from the IRS inflation adjustments for tax year 2026. Add $1,650 if you are 65 or older or blind, or $2,050 if you are also unmarried.
Married filing separately is the trap. The gross income filing threshold for that status is $5, not $16,100.
Gross income means income before expenses. Wages, interest, and your business receipts, not your profit.
Who files and who does not
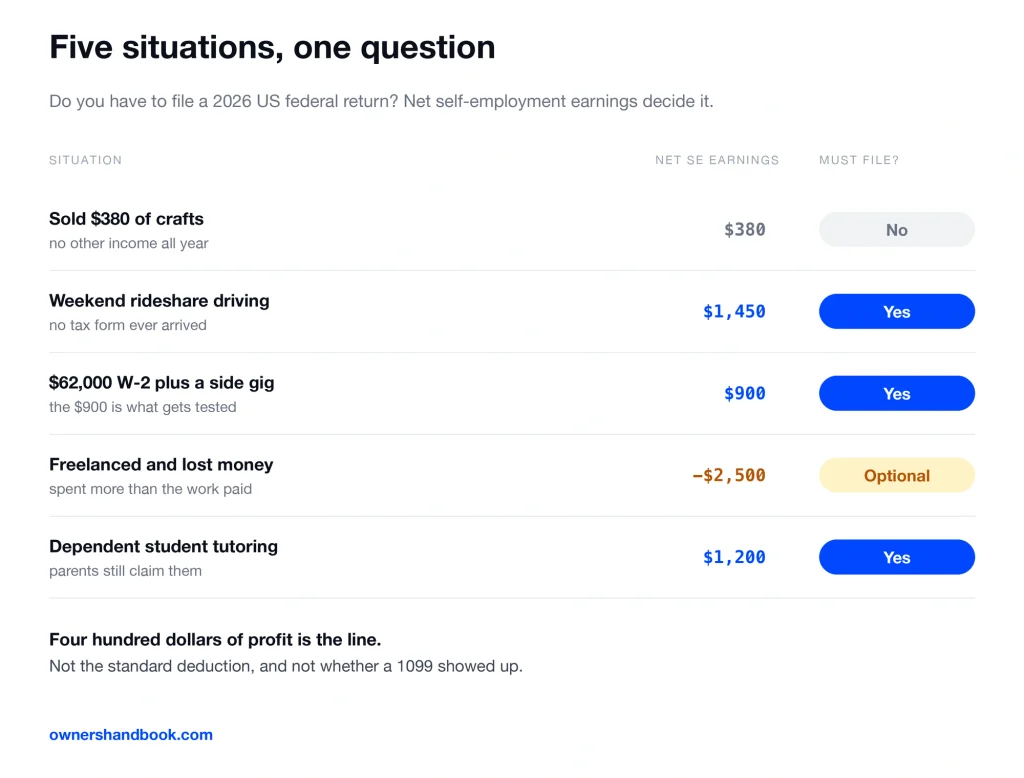
| Situation | Net self-employment earnings | Must file? |
|---|---|---|
| Sold $380 of crafts, no other income | $380 | No |
| Weekend rideshare driving, no forms arrived | $1,450 | Yes |
| $62,000 W-2 job plus a small side gig | $900 | Yes |
| Freelanced and lost money | -$2,500 | Not required |
| Dependent student tutoring | $1,200 | Yes |
The crafts seller in row one has another question to settle first. Occasional selling can be a hobby or business, and the answer changes what you can deduct.
Everyone else in the table is over $400, and that is the only test that runs.
Notice what is missing from the table. Nobody’s verdict turned on whether a form arrived, on how the client paid, or on what their day job earned.
A side gig next to a W-2 job
This is the most common case and the most commonly missed.
Your employer withheld tax all year. It feels handled. It is not, because the $400 rule looks only at the self-employment side of your income.
Earn $62,000 on a W-2 and $900 of net profit from weekend work, and you owe roughly $127 of self-employment tax on that $900.
It goes on the same return as the wages. Your employer never knew the side income existed, so nothing was withheld against it.
Once the side income grows past a few thousand dollars, quarterly estimated taxes start to matter. Raising your W-4 withholding at the day job is the easier alternative.
The reverse case is worth naming too. A W-2 job that pays $62,000 already puts you over the standard deduction, so the return was required regardless of the side work.
No 1099 arrived
A 1099 is a report your client files with the IRS. It is not what makes the income taxable.
Three clients paid you $450, $900, and $700. Each payment sits under the reporting threshold, so no 1099-NEC ever shows up in your mailbox.
You still took in $2,050. Subtract $600 of expenses and net earnings are $1,450. Over $400, so you file, and the self-employment tax runs about $205.
The IRS states this directly. Gig income must be reported even when it is not reported on an information return form, and that includes cash.
Missing forms change your paperwork. They do not change what you owe.
Expect more of this going forward. The 1099-NEC reporting floor rose in 2026, so smaller clients now have no obligation to send you anything at all.
A loss year, and why filing anyway can pay
Spend more than you brought in and your net earnings fall below $400. The self-employment rule stops requiring a return.
Filing can still be the better move.
A $2,500 loss on Schedule C reduces your other income. Next to a W-2 job taxed at 22%, that loss is worth about $550 back.
A return also recovers any tax that was withheld from you, and it starts a clock. The IRS generally has three years from when a return was due or filed to assess more tax.
If you never file, that clock never starts.
There is a separate reason in years when you bought health coverage through the Marketplace. Advance premium tax credits have to be reconciled on a return whether or not you owe tax.
One caution. A business that loses money year after year invites the hobby question, and hobby losses are not deductible.
A dependent with freelance income
Being claimed on someone else’s return changes nothing about the $400 rule.
A 19-year-old claimed by their parents earns $1,200 tutoring. They file their own return.
Their income tax is zero. A dependent’s 2026 standard deduction is the greater of $1,350 or earned income plus $450, which comes to $1,650 here, more than the $1,200 they earned.
Self-employment tax is still about $170. The standard deduction does not touch it.
The parents keep the dependent claim. The student files a separate return. Both are true at the same time.
Frequently asked questions
Is the $400 measured before or after expenses?
After. It is net earnings, which is your Schedule C profit reduced further by the 92.35% multiplier on Schedule SE.
I made $350 freelancing and had no other income. Do I file?
Not because of the $400 rule. File anyway if you had tax withheld somewhere and want it back, or if you qualify for a refundable credit.
Do my W-2 wages count toward the $400?
No. Wages already had Social Security and Medicare withheld. The $400 test looks only at self-employment net earnings.
I got a 1099-NEC for $300. Do I have to file?
The form does not create the requirement. If $300 is your total net self-employment earnings for the year and you have no other filing trigger, no return is required. Report it if you file for another reason.
Does my state use the same $400 rule?
No. State filing thresholds are set separately and are often much lower than the federal standard deduction. Check your state revenue department.
Which forms does a $500 profit require?
Form 1040, Schedule C for the profit, and Schedule SE for the self-employment tax. Three forms for about $71 of tax.
Sources
IRS, Self-Employment Tax (Social Security and Medicare Taxes)
IRS, Instructions for Schedule SE (Form 1040)
IRS, Rev. Proc. 2025-32 (tax year 2026 inflation adjustments)
https://www.irs.gov/pub/irs-drop/rp-25-32.pdf
IRS, Publication 501, Dependents, Standard Deduction, and Filing Information
IRS, Gig Economy Tax Center
IRS, Reporting Payments to Independent Contractors
IRS, About Schedule C (Form 1040)
IRS, IRS Audits