What to Do Before December 31: A Freelancer’s Year-End Tax List
Most of what you read about year-end tax moves is written for people with employers. For a freelancer the list is shorter than it looks — and one item on it is invisible, cannot be fixed in April, and costs more than everything else combined.
This is what actually expires on December 31, 2026, and what does not.
The one that cannot be fixed later
If you have a solo 401(k), the election to defer part of your own pay has to be in place before the year closes. The money can arrive later. The decision cannot.
The IRS states it plainly for owner-employees: the deferrals must be elected by the end of the tax year, and can then be made by the tax return filing deadline, including extensions.
Nothing happens on December 31 to remind you. No form is filed, no money moves, no notice arrives. You simply either made the election or you did not — and in April there is no way back.
For 2026 that election is worth up to $24,500, plus $8,000 more if you are 50 or older. If you are between 60 and 63, the catch-up is $11,250 instead.
That is the most expensive deadline on this page, and the only one with nothing to show for missing it.
The rest of December 31 is shorter than you think
Two other things genuinely turn over at midnight.
| What | Why December 31 |
|---|---|
| Your age for the long-term care cap | The cap is set by your age at the end of the year |
| Equipment placed in service | It has to be in use, not merely ordered or paid for |
The second one catches people who buy a laptop on December 29 and leave it in the box. The test is whether the thing was ready and available for use, not whether the card was charged. More on that in our guide to writing off equipment.
That is the list. Everything else people tell you to rush is not actually due.
What does not expire on December 31
This is the useful half, and almost nobody writes it.
| Lever | Real deadline for tax year 2026 |
|---|---|
| SEP-IRA — open and fund it | October 15, 2027, if you extend |
| Solo 401(k) — open it, first year, sole proprietor | April 15, 2027, no extensions |
| Solo 401(k) — fund the deferral you elected | Filing deadline, extensions included |
| Traditional or Roth IRA | April 15, 2027, no extensions |
| HSA | April 15, 2027, no extensions |
| Your Q4 estimated payment | January 15, 2027 |
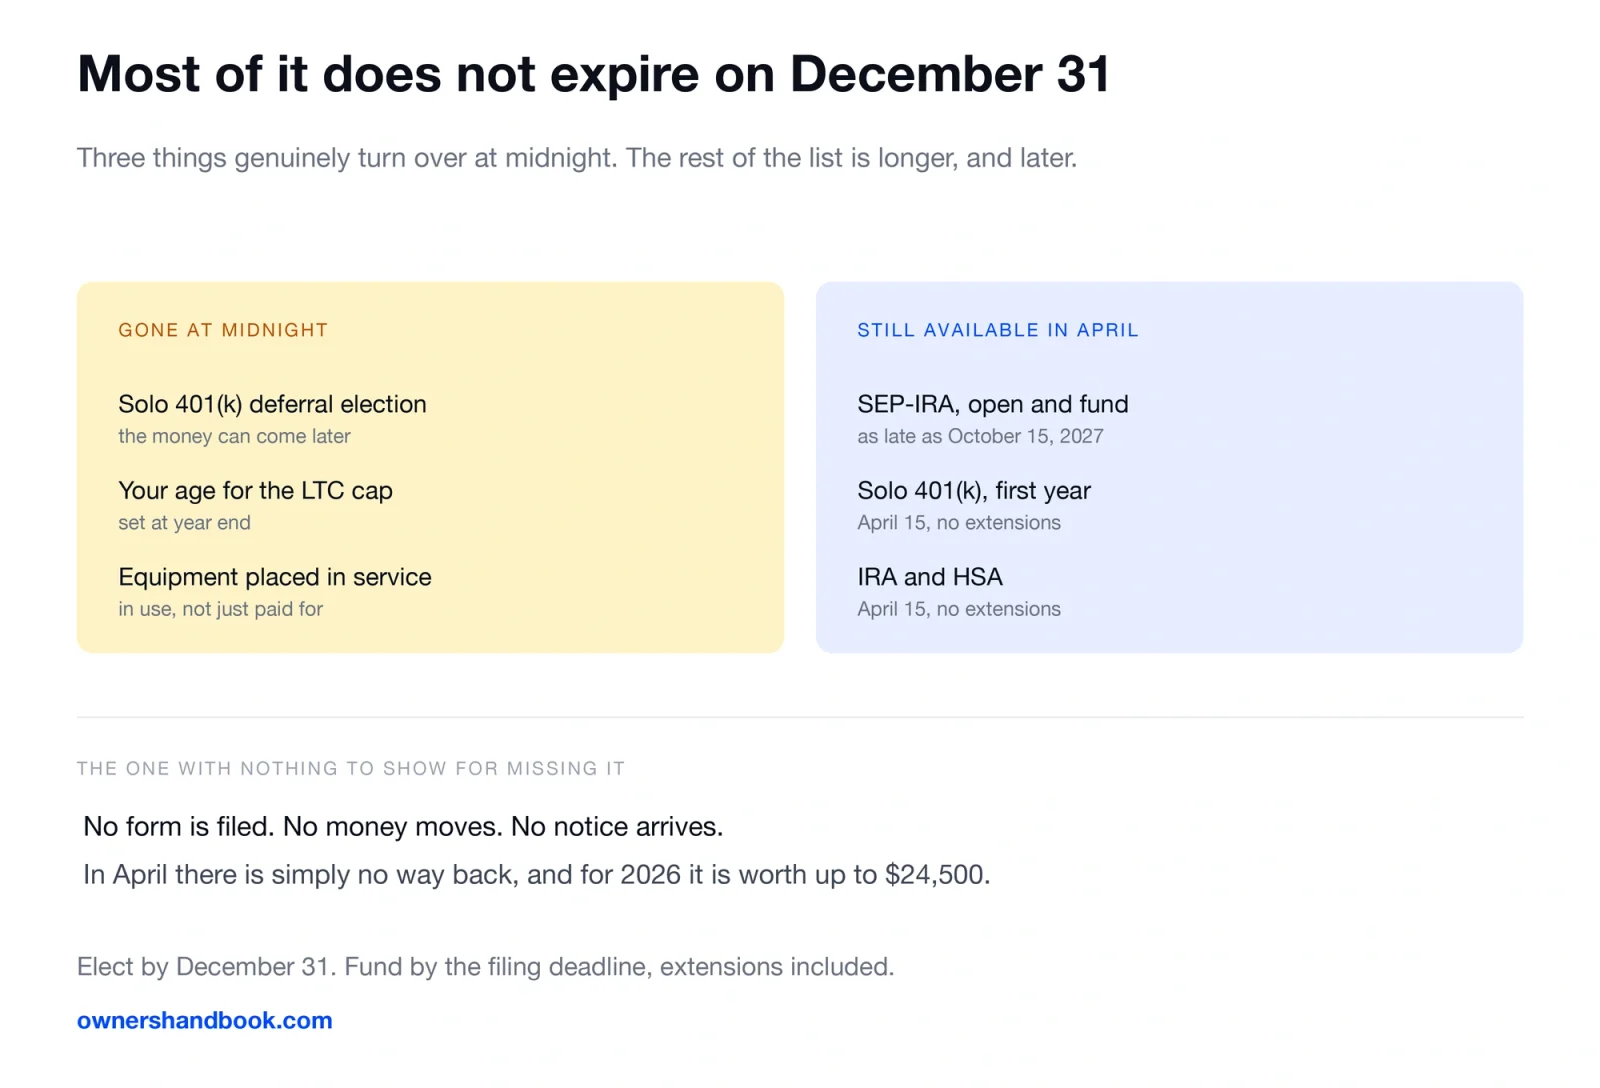
The SEP is the standout. You can open one and fund it as late as October 15, 2027 for the 2026 tax year — the only meaningful retroactive tax lever a freelancer has after the year has ended. Total contributions to a SEP or a solo 401(k) can reach $72,000 for 2026.
Note the two rows that say *no extensions*. Filing Form 4868 buys you six months for the return and zero extra days for an IRA or an HSA. Those are April 15 regardless.
Our comparison of solo 401(k) and SEP-IRA goes through which one fits which kind of year.
One thing that is not a deadline at all any more
If you have a single-member LLC, you have probably read that you must file a beneficial ownership report with FinCEN.
You do not. FinCEN exempted US companies in March 2025, and a final rule effective August 14, 2026 made it permanent. The exemption covers all entities created in the United States and their beneficial owners. Only certain foreign entities still report.
Nearly every article written about LLCs in 2024 says otherwise. They have not been updated.
What December is actually for
The real work in December is not moving money. It is getting ready for a January deadline that has no extension.
Chase your W-9s while you still have leverage. Pull a list of everyone you paid $2,000 or more for services this year. That floor stood at $600 from 1954 until the end of 2025 — the IRS instructions now say the minimum “increased to $2,000 and may be adjusted for inflation beginning in calendar year 2027.” Most of what you will read online still prints $600.
Anyone on that list without a W-9 on file, chase now — while you may still be holding an unpaid invoice.
This matters more than it sounds. If you pay a contractor who has not furnished a taxpayer identification number, you are required to withhold 24% of the payment and remit it, and you are on the hook for it if you do not. “Get the W-9 before you pay” is not an organising tip. It is the cheap way to avoid a legal obligation.
Know what January costs if you are late. Form 1099-NEC has no extension. None. The 30-day extension that covers other 1099s does not apply to it.
| When you fix it | Per form | Small business cap |
|---|---|---|
| Within 30 days | $60 | $239,000 |
| By August 1 | $130 | $683,000 |
| After August 1, or never | $340 | $1,366,000 |
| Intentional disregard | at least $680 | no cap |
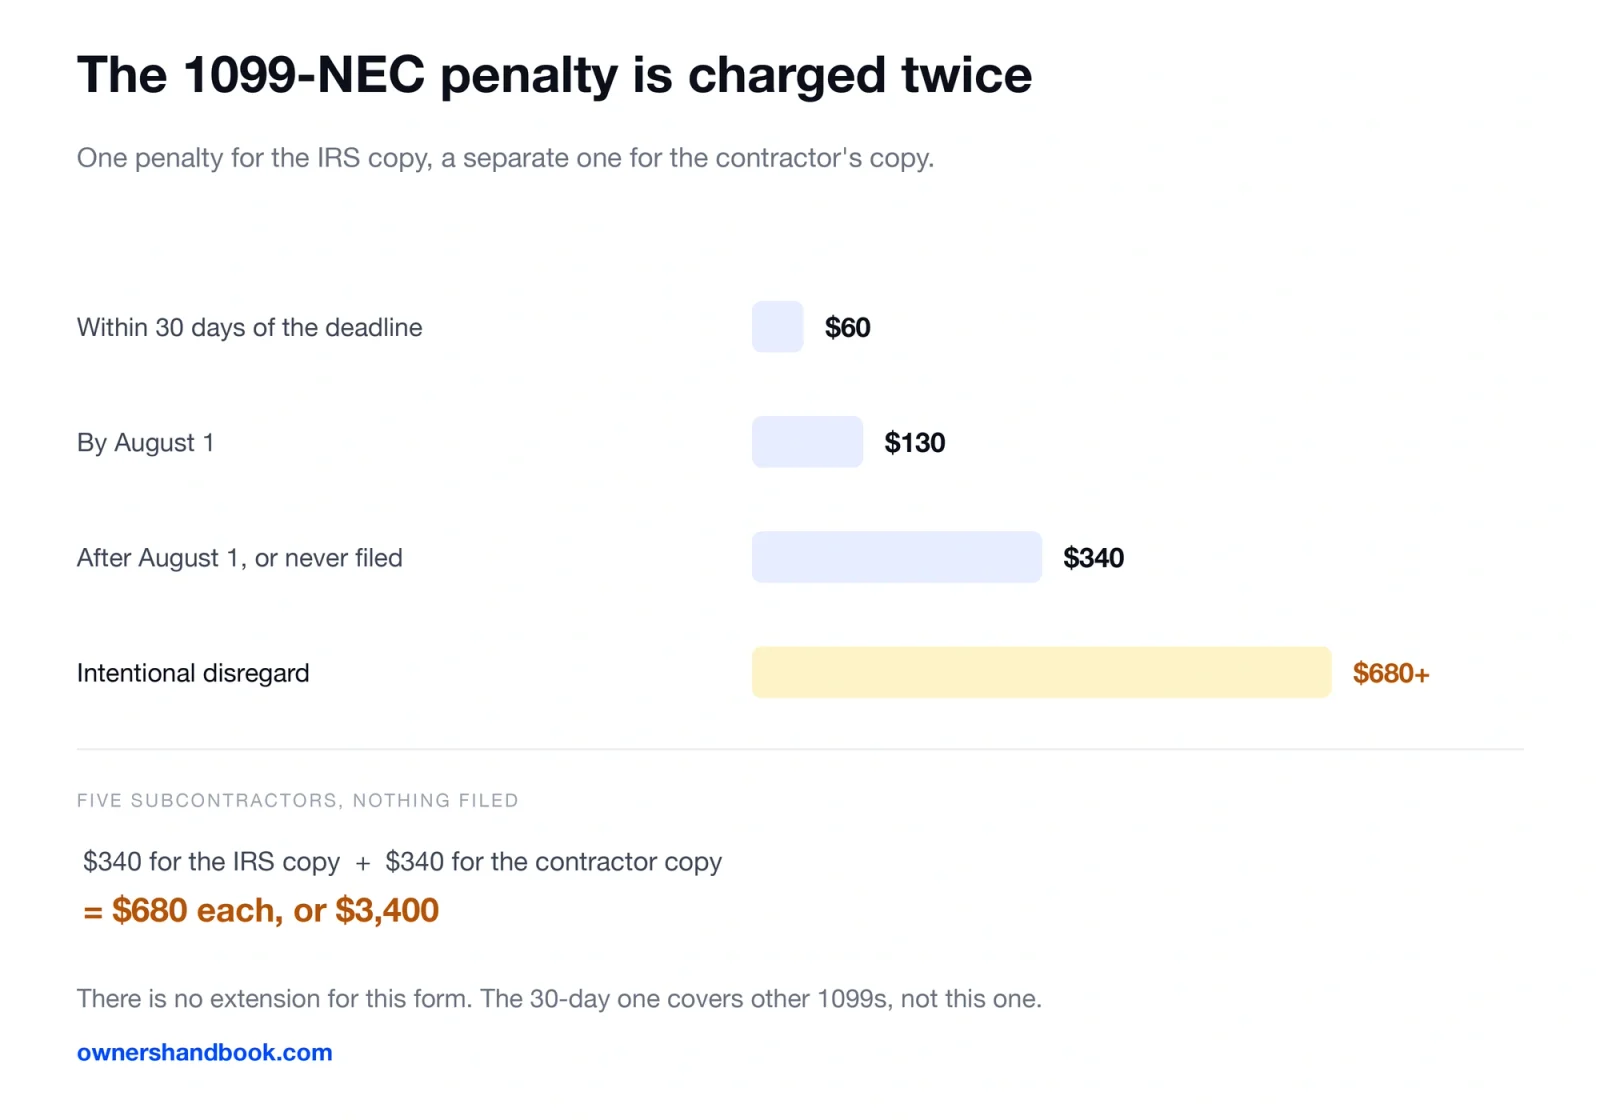
And there is a detail most coverage misses: these are two separate penalties. One for failing to file the IRS copy, one for failing to furnish the contractor’s copy. Blow the deadline and you miss both.
So a freelancer who subcontracted to five people and filed nothing is looking at $680 each — $3,400, not $1,700. Our guide to issuing a 1099-NEC walks through the mechanics.
Reasonable-cause relief does exist for these, but First Time Abate does not cover information returns. It is a different route with a higher bar.
The Q4 payment, and the way to skip it
Your fourth estimated payment for 2026 is due January 15, 2027.
There is a published alternative, and it is genuinely useful if January is tight: file your 2026 return by February 1, 2027 and pay the whole balance with it, and you do not have to make the January 15 payment at all.
That is not a loophole. It is stated in Form 1040-ES. You are trading a January payment for a much earlier filing date — which is a good trade if your records are already in order, and a bad one if they are not.
If you are working out what to send, our quarterly tax calculator handles the safe harbor.
If you are thinking about an S corporation
The election for the 2027 tax year is due March 15, 2027. That feels far away. It is not, because the election is the easy part.
Before you file Form 2553 you need an EIN, a defensible reasonable-compensation figure, and payroll able to run W-2s and quarterly returns from January 1. That is a Q4 project, not a March one.
This is also the deadline with no penalty and the largest cost. Nothing is assessed if you miss it. You simply pay self-employment tax on your full net profit for an entire extra year. Our guide to whether the S corp election is worth it has the arithmetic.
A note on timing your invoices
If you report on the cash method — which nearly every freelancer does — income counts in the year you receive it, not the year you billed it.
That gives you a genuine decision in late December about whether to send an invoice now or on January 2.
It does not give you the option of leaving a cheque uncashed. Money that was made available to you counts, whether or not you went and got it. Delay the billing if you want to; do not delay the deposit and call it planning.
Frequently asked questions
Do I have to spend money before December 31 to lower my taxes?
Rarely. Buying something you did not need to save 30 cents on the dollar leaves you 70 cents poorer. The one exception is a purchase you were going to make in January anyway — and even then, the thing has to be in use before the year ends, not just paid for.
Can I still open a retirement account for 2026 after January 1?
Yes, for a SEP-IRA — as late as October 15, 2027 if you extend. Also yes for a first-year solo 401(k) if you are a sole proprietor with no employees, but only until April 15, 2027, with no extension. What you cannot do after December 31 is make the deferral election on a solo 401(k) you already had.
I missed the September estimated payment. Should I catch up now or wait?
Now. The underpayment penalty is figured per period, for the number of days each shortfall stays unpaid — so every day you wait costs a little more. Paying early does not erase the days already run, but it stops them. Our guide on missed estimated payments covers what happens next.
Does filing an extension give me longer to fund an IRA?
No. The IRA and HSA deadlines are April 15 with no extensions, which is exactly why they trip people who extended and assumed everything moved with them.
Do I need to file a beneficial ownership report for my LLC?
Not if the LLC was created in the United States. FinCEN’s final rule, effective August 14, 2026, exempts US entities permanently.
What if my income was all in the fourth quarter?
The default rule assumes your income arrived evenly across the year, which can produce a penalty on a Q1 you had not earned yet. There is an alternative — the annualized income installment method on Schedule AI of Form 2210 — but it requires closing your books at March 31, May 31, August 31 and December 31. Worth it for genuinely lumpy years, not for ordinary ones.
Sources
IRS, Publication 560, Retirement Plans for Small Business
https://www.irs.gov/pub/irs-pdf/p560.pdf
IRS, Notice 2025-67, 2026 retirement plan limitations
https://www.irs.gov/pub/irs-drop/n-25-67.pdf
IRS, 401(k) limit increases to $24,500 for 2026
https://www.irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500
IRS, Form 1040-ES, Estimated Tax for Individuals (2026)
https://www.irs.gov/pub/irs-pdf/f1040es.pdf
IRS, Publication 509, Tax Calendars (2026)
https://www.irs.gov/pub/irs-pdf/p509.pdf
IRS, Publication 590-A, Contributions to Individual Retirement Arrangements
https://www.irs.gov/pub/irs-pdf/p590a.pdf
IRS, Publication 969, Health Savings Accounts
https://www.irs.gov/pub/irs-pdf/p969.pdf
IRS, Information return penalties
https://www.irs.gov/payments/information-return-penalties
IRS, Instructions for Form 2553
https://www.irs.gov/instructions/i2553
IRS, Instructions for Form 2210
https://www.irs.gov/pub/irs-pdf/i2210.pdf
FinCEN, Beneficial Ownership Information