You Owe and Cannot Pay: IRS Payment Plans for 1099 Filers
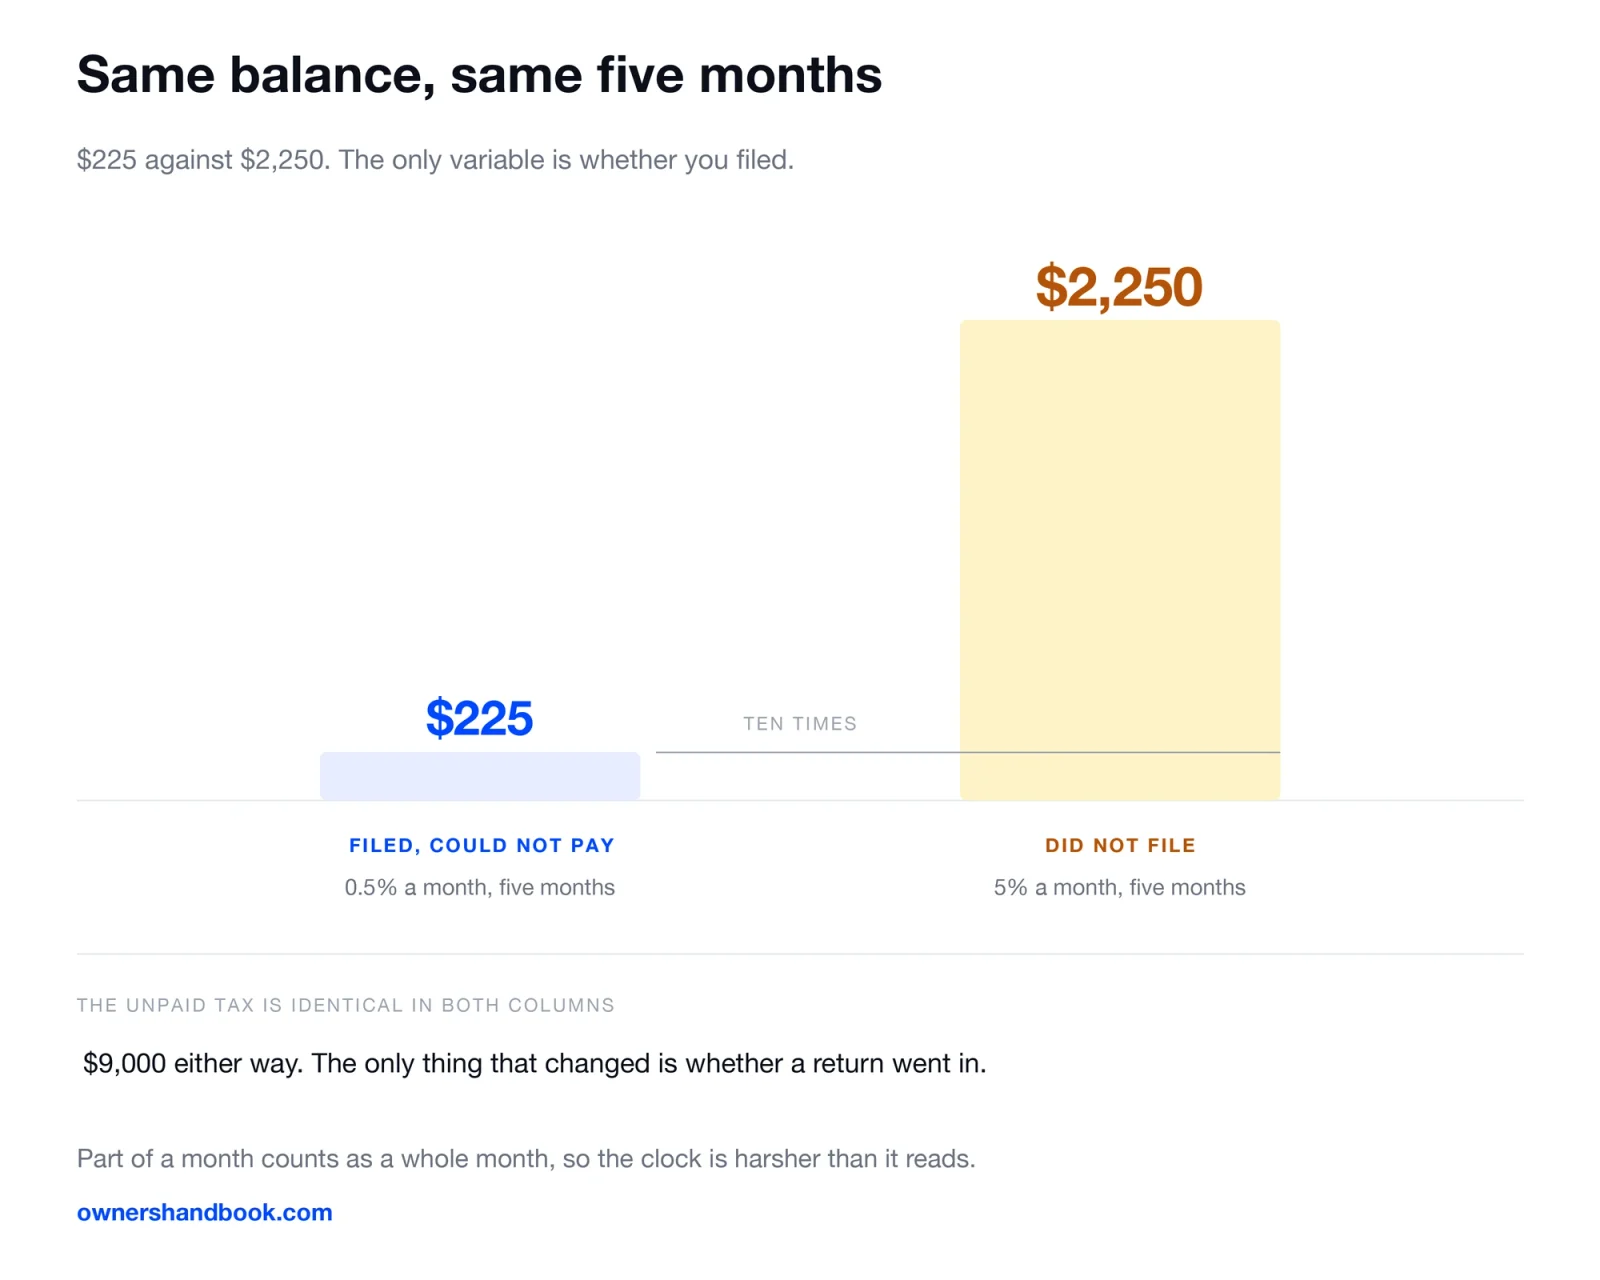
File the return. That is the first move, and it is not a formality — the penalty for not filing is ten times the penalty for not paying. On a $9,000 balance, five months of not filing costs $2,250. Five months of filing and not paying costs $225. The missing money is identical in both cases. The only difference is whether a return went in.
An extension to file is not an extension to pay
This is the single most common mistake, and it costs people real money every October.
Form 4868 moves the filing deadline. It does not move the payment deadline. Both deadlines sit on the same April date, and the extension touches exactly one of them.
So the balance was due in April whether or not you filed a 4868, and interest has been running on it since that day. Our walkthrough of what an extension actually does has the full timeline.
Filing an extension you cannot fund is still worth doing. It removes the 5% penalty. It does nothing about the 0.5% penalty or the interest.
The two penalties are different sizes
There are two, they run on the same unpaid tax, and one is ten times the other.
| Penalty | Rate | Cap | Trigger |
|---|---|---|---|
| Failure to file | 5% a month | 25% | No return and no extension by the due date |
| Failure to pay | 0.5% a month | 25% | Tax unpaid after the due date |
| Both in one month | 5% combined | — | File penalty drops to 4.5%, pay penalty stays 0.5% |
The IRS states the interaction directly: when both apply, the failure to file penalty is reduced by the amount of the failure to pay penalty, so instead of 5% for the month it applies 4.5% plus 0.5%. After five months the failure to file penalty maxes out, but the failure to pay penalty continues.
Part of a month counts as a whole month. The IRS applies full monthly charges even if you pay in full before the month ends.
There is a floor under the file penalty too. If a return is more than 60 days late, the minimum is $525 or 100% of the underpayment, whichever is less, for returns due after December 31, 2025. For returns that were due during 2025 it is $510.
Two rate changes are worth knowing about before they happen to you. If you filed on time and have an approved payment plan, the failure to pay penalty is reduced to 0.25% per month. And if you do not pay within 10 days of a notice of intent to levy, it rises to 1% per month.
What the delay actually costs
Penalties are one clock. Interest is a separate one, and it does not stop for anything.
The rate is the federal short-term rate plus three percentage points, compounded daily. The IRS resets it quarterly. Through 2026 it has run 7%, then 6%, then 7%, then 7% again.
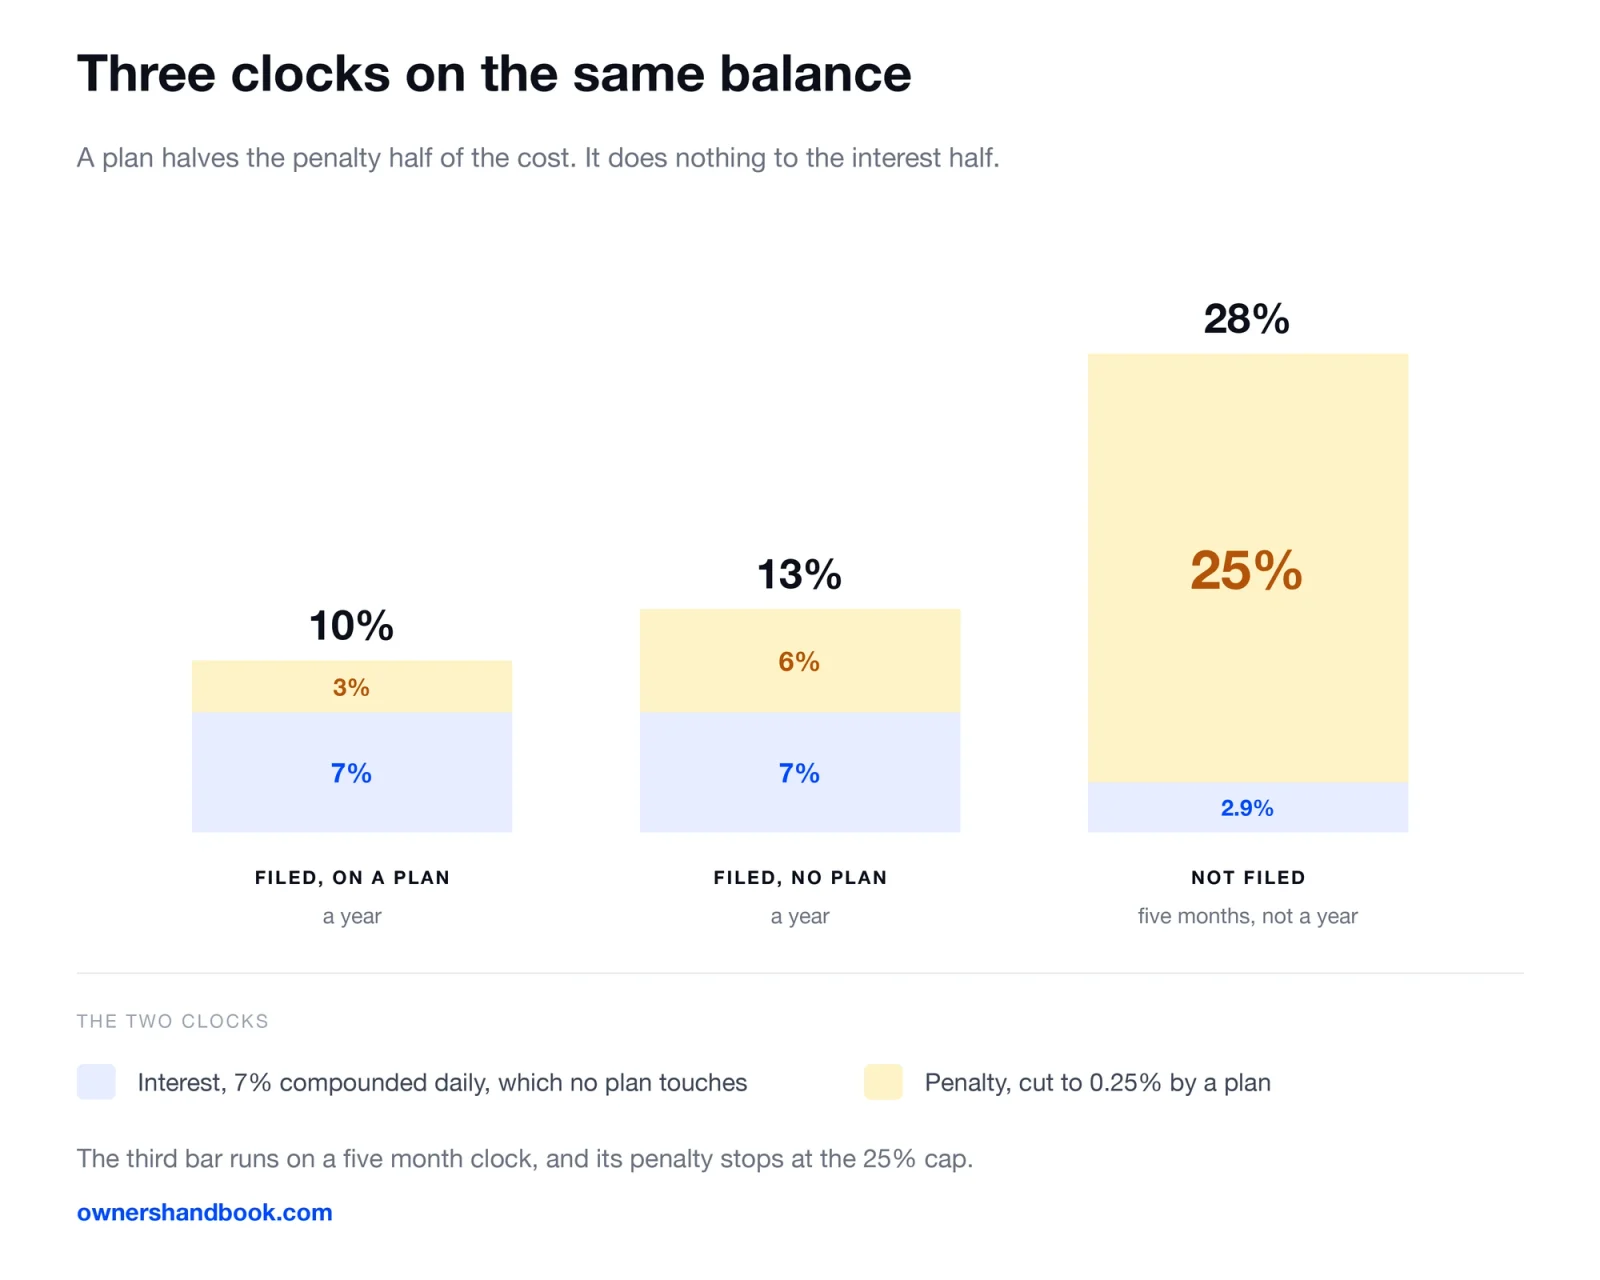
Stack the two and you get the real annual cost of carrying an unpaid balance.
| Situation | Interest | Penalty | Cost of carrying the balance |
|---|---|---|---|
| Filed, on an approved plan | 7% | 0.25% a month | About 10% a year |
| Filed, no plan | 7% | 0.5% a month | About 13% a year |
| Not filed | 7% | 5% a month, 25% cap | 25% in the first five months |
The third row is why the advice is never “wait until you have the money.” Ten or thirteen percent a year is an expensive loan. Losing a quarter of the balance in five months is not a loan at all.
Your three options, and what each one costs
The IRS runs two plans and accepts cards. Here is the whole menu with the fees as the IRS publishes them.
| Option | You qualify if | Setup fee | Then |
|---|---|---|---|
| Pay in full today | — | $0 | Nothing accrues |
| Short-term plan, 180 days or less | You owe less than $100,000 in combined tax, penalties and interest | $0 | Interest and applicable penalties keep accruing |
| Long-term plan, direct debit | You owe $50,000 or less combined | $29 online, $107 by phone, mail or in person | Interest plus the reduced penalty, if you filed on time |
| Long-term plan, other payment method | Same $50,000 limit | $69 online, $178 by phone, mail or in person | Same |
| Credit card | — | 1.75% or 1.85% of the payment | Whatever your card charges |
Note where the money actually is. The difference between applying online and applying by phone or on paper is $78 for a direct debit plan and $109 otherwise. Nothing about the plan changes. The application channel is the entire difference.
If your adjusted gross income for the most recent year available is at or below 250% of the federal poverty guidelines, the direct debit setup fee is waived outright, and the non-direct-debit fee drops to $43 and may be reimbursed. You apply for that with Form 13844.
Two more fee lines people hit later. Revising a plan costs $6 online or $89 by phone, mail or in person, and changes to an existing direct debit plan are free.
The short-term plan is the underused one. There is no user fee at any application channel, and 180 days is six months — long enough for most freelance cash flow problems to resolve themselves.
Paying by card: run the break-even
The IRS does not take cards directly. Two processors do, and they charge you, not the IRS.
| Processor | Debit card | Credit card |
|---|---|---|
| Pay1040 | $2.15 flat | 1.75%, $2.50 minimum |
| ACI Payments | $2.10 flat | 1.85%, $2.50 minimum |
A debit card is simple arithmetic. Two dollars and change to move any amount is cheaper than almost anything else on this page, if the money is in the account.
A credit card needs the comparison run properly, because paying the IRS with a card does not make the debt go away. It moves it to a lender whose rate you should look up.
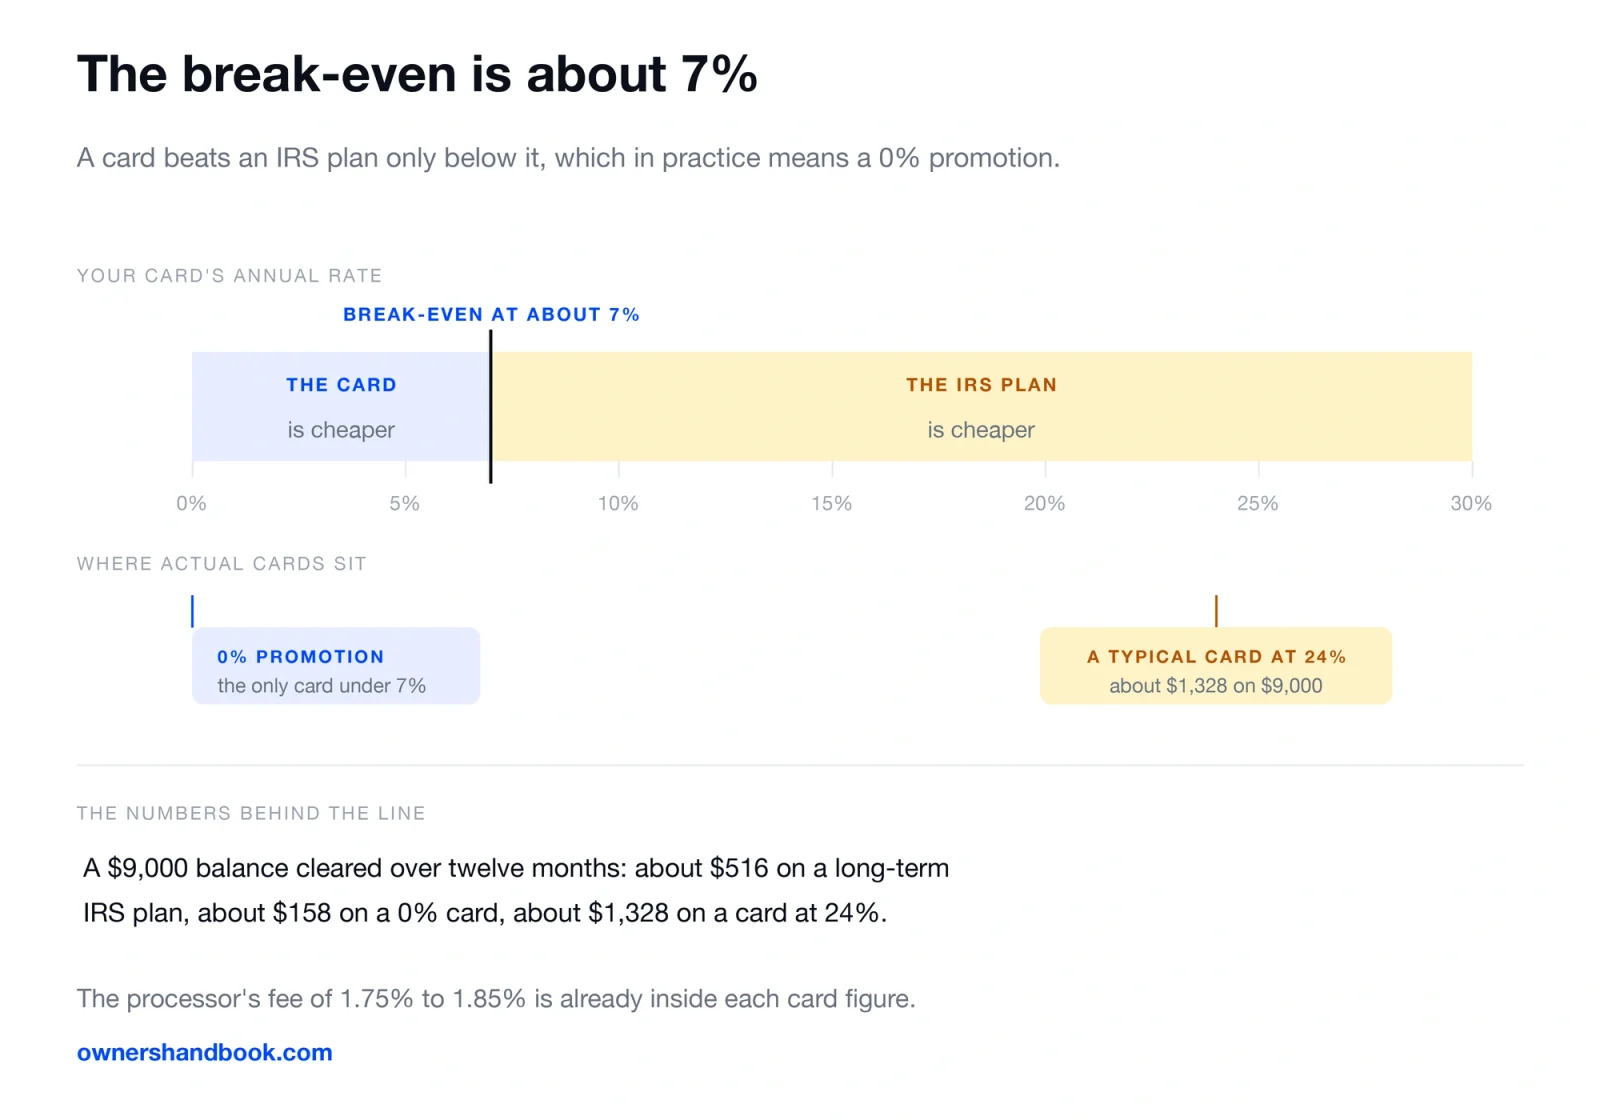
Take the $9,000 balance and twelve months to clear it. Average outstanding balance is about $4,875.
| Route | Up front | Over twelve months | Total |
|---|---|---|---|
| Long-term plan | $29 setup | 7% interest plus 0.25% a month ≈ $487 | About $516 |
| Credit card at 0% promo | $157.50 fee | $0 | About $158 |
| Credit card at 24% | $157.50 fee | $4,875 × 24% ≈ $1,170 | About $1,328 |
Set the two equal and the break-even card rate is about 7%. Below that the card wins. Above it the IRS plan wins, and most cards are well above it.
So the card is the right answer in one specific case — a genuine 0% promotional period long enough to clear the balance — and the wrong answer otherwise. That is a question about your card’s terms, not about the IRS.
The hardship form almost nobody files
Form 1127 asks for an extension of time to pay under section 6161. It is not a payment plan and it is not an extension to file.
The standard is undue hardship, and the form defines it: more than an inconvenience. You must show you will have a substantial financial loss — the form’s own example is selling property at a sacrifice price — if you pay the tax on the date it is due.
The timing is strict. For tax shown on a return, Form 1127 must be received on or before the due date of that return, not including extensions. An extension of more than six months is generally not granted.
Interest still runs. The form says so on its face. What an approved 1127 does is move the date prescribed for payment, and the failure to pay penalty under section 6651(a)(2) is figured with regard to any extension of time for payment. So it stops the 0.5% half of the problem and does nothing to the 7% half.
It is a narrow tool and most people will not qualify. It is also free, and it exists, which is more than can be said for most of what gets advertised to people in this position.
Before any of it: be current
A payment plan request will not be considered unless you are current on all filing and payment requirements. That sentence is doing a lot of work.
It means an unfiled year blocks the plan for the year you did file. If you are behind on returns for earlier years, those have to go in first, and the order matters.
It also means future-year compliance is part of the deal. The installment agreement terms require enough withholding or estimated payments that next year’s tax is paid when due. A plan that triggers a new balance next April defaults itself.
For most self-employed filers that means fixing the quarterly estimated payments at the same time as the plan, not after it. If you skipped them this year, the charge for that is interest rather than a fine, and our walkthrough of missed estimated payments has the arithmetic.
What this is not
Three things get sold to people who owe money. None of them are first moves.
An offer in compromise settles a liability for less than the full amount. It has real eligibility rules, the IRS requires that you have filed all required returns, and every application carries a $205 fee and a first payment unless you meet the low-income qualifications. It is a real statutory program. It is not a shortcut, and the IRS’s own eligibility tool is the place to start rather than anyone’s sales page.
A temporary delay of collection is available if you genuinely cannot pay anything. The IRS is explicit about the cost: your debt continues to accrue interest and penalties up to the maximum allowed by law until it is paid.
And nothing on this page requires paying anyone to arrange it. Every plan here is applied for directly, the online channel is the cheapest one, and the fee schedule is published. If you want help with the return itself rather than the payment, that is a different question, and software or a CPA is a threshold rather than a preference.
Frequently asked questions
Should I file if I know I cannot pay anything at all?
Yes. The failure to file penalty is 5% a month against 0.5% for failure to pay, and filing is what makes a payment plan available at all. Our guide to doing your own freelance return covers the filing side.
Does a payment plan stop the interest?
No. Interest accrues on any unpaid tax, penalties and interest until the balance is paid in full. A plan reduces the failure to pay penalty to 0.25% a month if you filed on time, and that is all it does to the meter.
Can I set up a plan before the IRS sends me a bill?
Yes. The IRS says you may establish a pre-assessed agreement by entering the balance you will owe from your return, without waiting for a notice.
What if I owe more than $50,000?
The long-term online application tops out there. Above it you are into a Collection Information Statement on Form 433-F, 433-A or 433-B and a lien determination, which means a conversation with the IRS rather than a web form.
Is there a plan with better terms for a small balance?
There is a guaranteed installment agreement if you are an individual, owe $10,000 or less excluding interest and penalties, have timely filed and paid for the past five years, have not had an installment agreement in those five years, agree to pay in full within three years, and cannot pay in full now.
Should I just send a partial payment with no plan?
It helps. Both the penalty and the interest run only on the unpaid part, so every dollar you send shrinks both. Direct Pay takes a payment from a checking account at no charge on any day you choose.
Why is my bill so much bigger than I expected?
Usually because self-employment tax is 15.3% on top of income tax and nothing was withheld. If this is your first year with 1099 income, the arithmetic in a first freelance year is the place to look.
Sources
IRS, Failure to File Penalty
https://www.irs.gov/payments/failure-to-file-penalty
IRS, Failure to Pay Penalty
https://www.irs.gov/payments/failure-to-pay-penalty
IRS, Quarterly Interest Rates
https://www.irs.gov/payments/quarterly-interest-rates
IRS, Payment Plans; Installment Agreements
https://www.irs.gov/payments/payment-plans-installment-agreements
IRS, Topic 202: Tax Payment Options
https://www.irs.gov/taxtopics/tc202
IRS, Pay Your Taxes by Debit or Credit Card or Digital Wallet
https://www.irs.gov/payments/pay-your-taxes-by-debit-or-credit-card
IRS, Form 1127 (Rev. December 2024), Application for Extension of Time for Payment of Tax Due to Undue Hardship
https://www.irs.gov/pub/irs-pdf/f1127.pdf
IRS, Offer in Compromise
https://www.irs.gov/payments/offer-in-compromise
26 U.S.C. § 6651, Failure to file tax return or to pay tax