Your Client Never Sent a 1099. File Without It.
February is over and the 1099 from your biggest client never came. No envelope, no email, no portal link. You are now trying to work out whether you can file, whether you should chase them, and whether the IRS is going to notice.
This is the opposite problem from the one most pages answer. If a form did arrive and the number on it is wrong, our guide to a 1099 with the wrong amount covers what you file when the client refuses to correct it. Here there is no form at all — and that case is simpler, because nothing on your return was ever waiting for it.
Three of the most common reasons no form came are the client doing exactly what the rules require.
The rule is one sentence in Publication 334
The IRS puts it at the top of the chapter on business income:
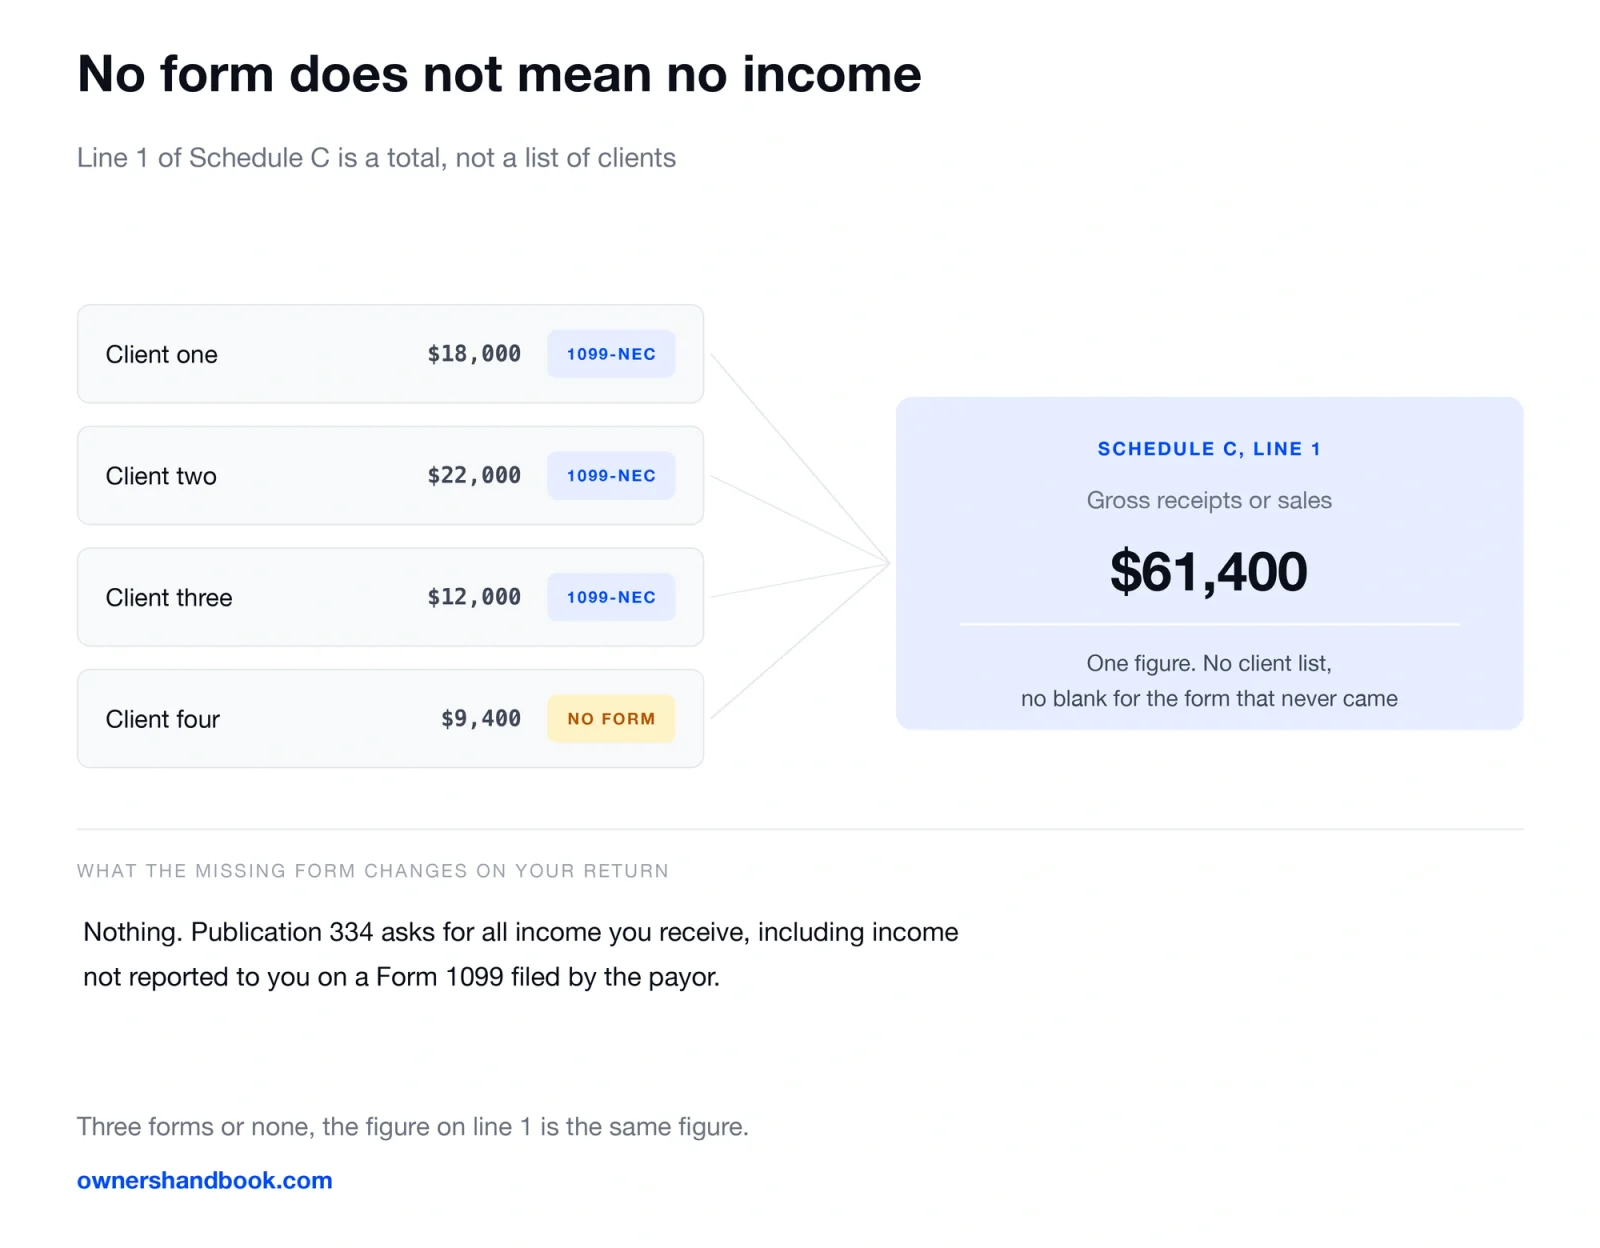
You must report on your tax return all income you receive from your business, including income not reported to you on a Form 1099 filed by the payor, unless it is excluded by law.
The Gig Economy Tax Center says the same thing from the other direction. You must report the income even when it is:
Not reported on an information return form — like a Form 1099-K, 1099-MISC, 1099-NEC, W-2 or other income statement
A 1099 is a copy of somebody else’s arithmetic about you. Your return reports your receipts. Line 1 of Schedule C asks for gross receipts as a single total — it does not itemise clients, so there is no blank on the form where the missing 1099 would have gone.
That is the whole of the filing problem. What is left is getting your own number right.
Why no form came, and whether anyone did anything wrong
Work through this before you send the client an email you will regret.
| Why no form came | Did the client get it wrong? | What it means |
|---|---|---|
| They paid you under $2,000 during 2026 | No | Below the threshold. No form is due |
| They paid by card, PayPal, Stripe, or a marketplace | No | The processor reports it on a 1099-K, not the client on a 1099-NEC |
| The client is outside the US | No | Foreign payers generally file no US information return |
| Your business is taxed as an S corp or C corp | No | Payments to corporations are generally not reported on a 1099-NEC |
| The payment was personal, not for their business | No | Reporting applies only to trade or business payments |
| None of the above | Yes | Their penalty. Your income either way |
The threshold is the row that changed. The December 2026 instructions for Forms 1099-MISC and 1099-NEC state it:
For tax years beginning after 2025, the minimum threshold amount for reporting certain payments required to be reported on certain information returns and/or perform backup withholding on those payments increased to $2,000 and may be adjusted for inflation beginning in calendar year 2027.
So a client who paid you $1,900 across 2026 owes you nothing. The same $1,900 paid during 2025 was over the old $600 floor and did require a form. Two rules are sitting next to each other right now, and our guide to issuing 1099s walks the payer side of both.
The payment-method row is the one almost nobody knows. The same instructions say card and third party network payments:
must be reported on Form 1099-K by the payment settlement entity under section 6050W and are not subject to reporting on Form 1099-MISC or Form 1099-NEC
A client who paid you $40,000 through Stripe files nothing and is correct. Whether a 1099-K then reaches you is a separate question with a much higher bar, which the 1099-K thresholds covers. For money that arrived from abroad, getting paid by overseas clients covers what does and does not get reported.
Rebuild the number from your own records
Publication 583 is unusually relaxed about how:
Except in a few cases, the law does not require any specific kind of records. You can choose any recordkeeping system suited to your business that clearly shows your income and expenses.
It then lists what counts as evidence of gross receipts: cash register tapes, bank deposit slips, receipt books, invoices, credit card charge slips, and Forms 1099-MISC and 1099-NEC. The forms are one item on a list of six. They were never the foundation.
In practice, for one client:
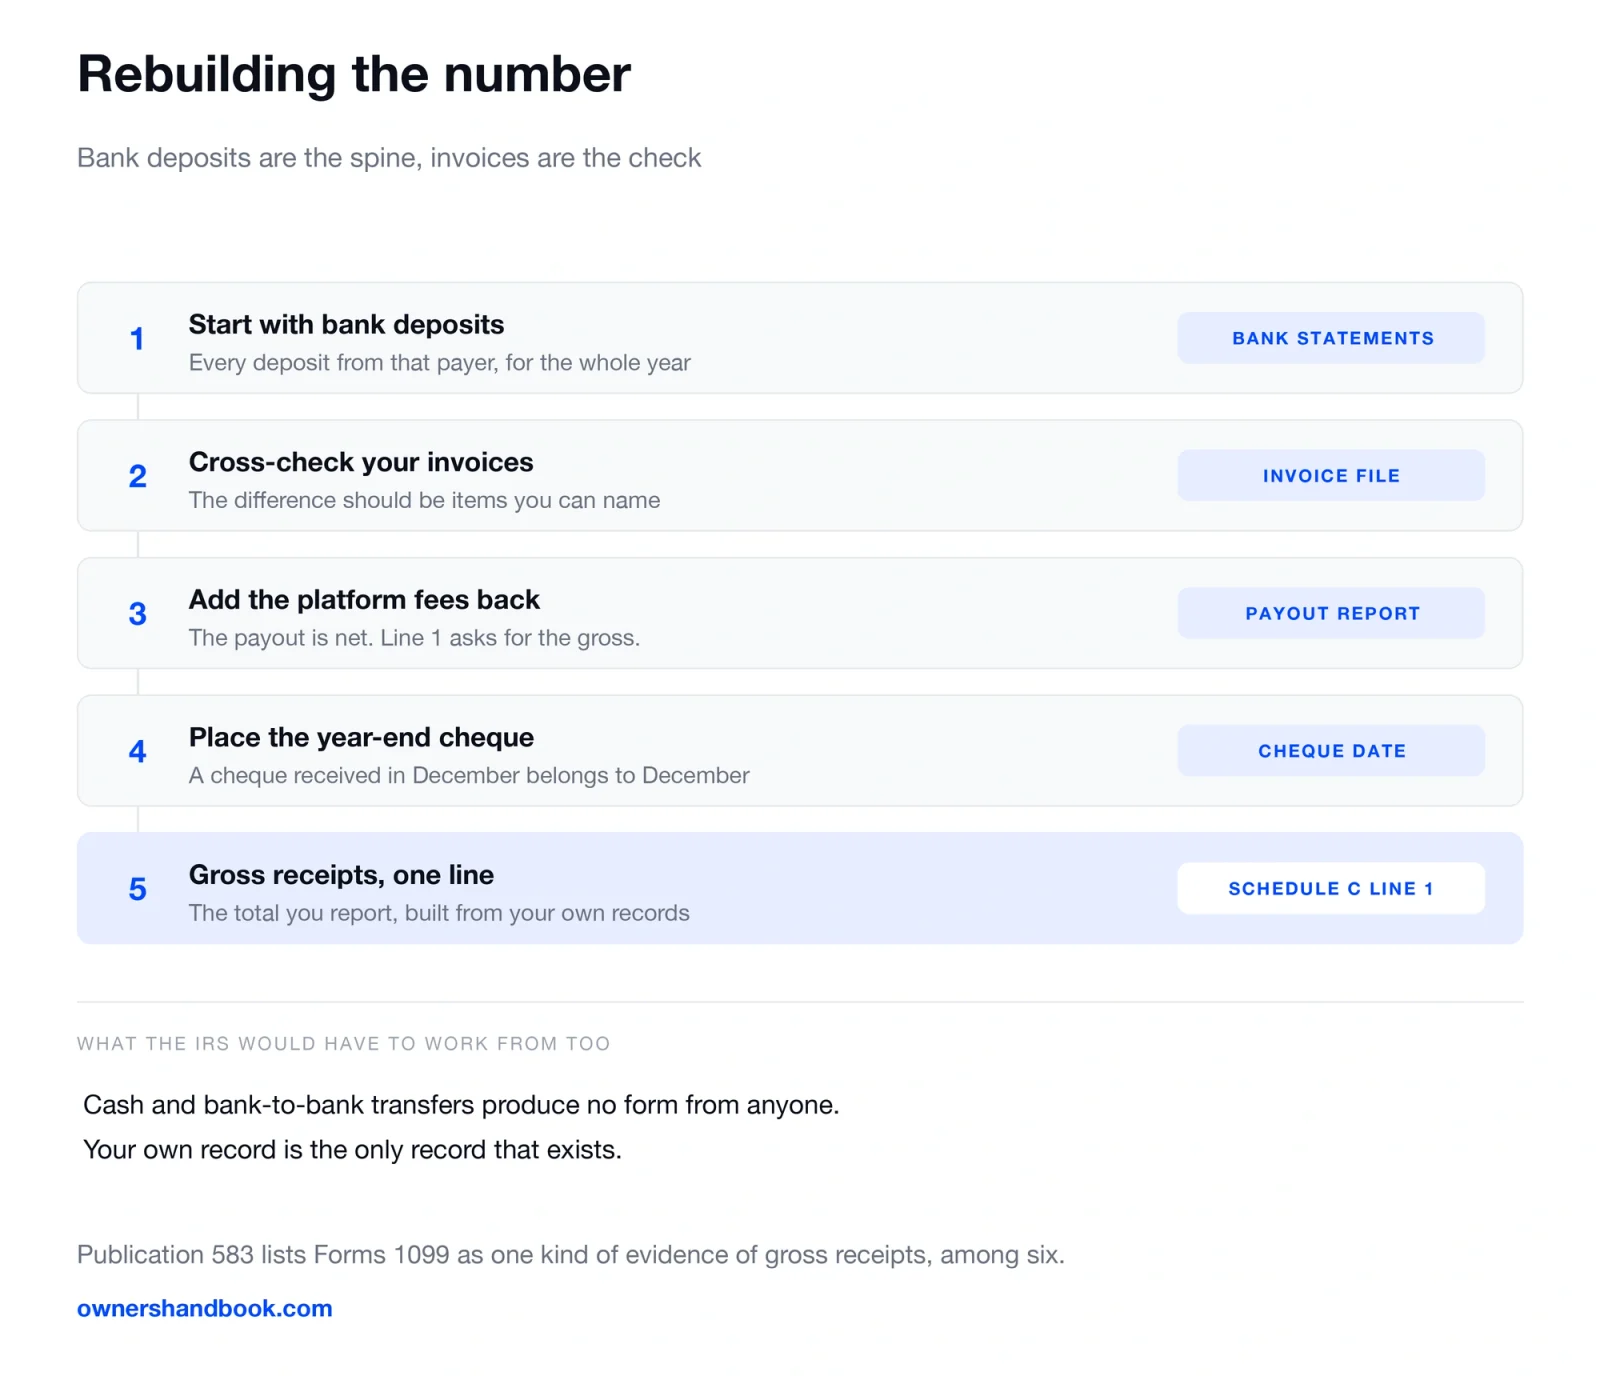
Start with bank deposits. Pull every deposit from that payer for the year. This is the primary evidence of what you received.
Cross-check against your invoices. Invoice totals and deposit totals should differ only by items you can name — a fee, a chargeback, an invoice paid in January.
Add back platform fees. If the money came through a marketplace, the deposit is net. Gross receipts on line 1 are the gross amount, and the fee is a separate expense. Netting them understates both sides of your return.
Write one page. Client name, every payment with its date, the total. Do it while you still remember which invoice was which. Our guide to tax record keeping covers how long to keep it, and receipt rules covers the expense side.
Cash and bank-to-bank transfers deserve a line of their own. Nobody files a form about them. If you were paid in cash or through a direct bank transfer app, your own record is the only record that exists, which makes it the one the IRS would have to work from too.
Check what was actually filed about you
There is a free way to see what the IRS has, and it settles most of the anxiety.
The Wage and Income Transcript, in the IRS description, “shows data from information returns we receive such as Forms W-2, 1098, 1099, and 5498.” It covers the current year plus nine prior years. You can view it in your Individual Online Account, request it with Form 4506-T, order it by mail, or call 800-908-9946.
Two caveats matter more than the transcript itself. Information for the current processing year generally becomes available in the first week of February, which is days after the forms were due — so an early transcript can be incomplete simply because a late filer has not been processed. And the IRS says plainly:
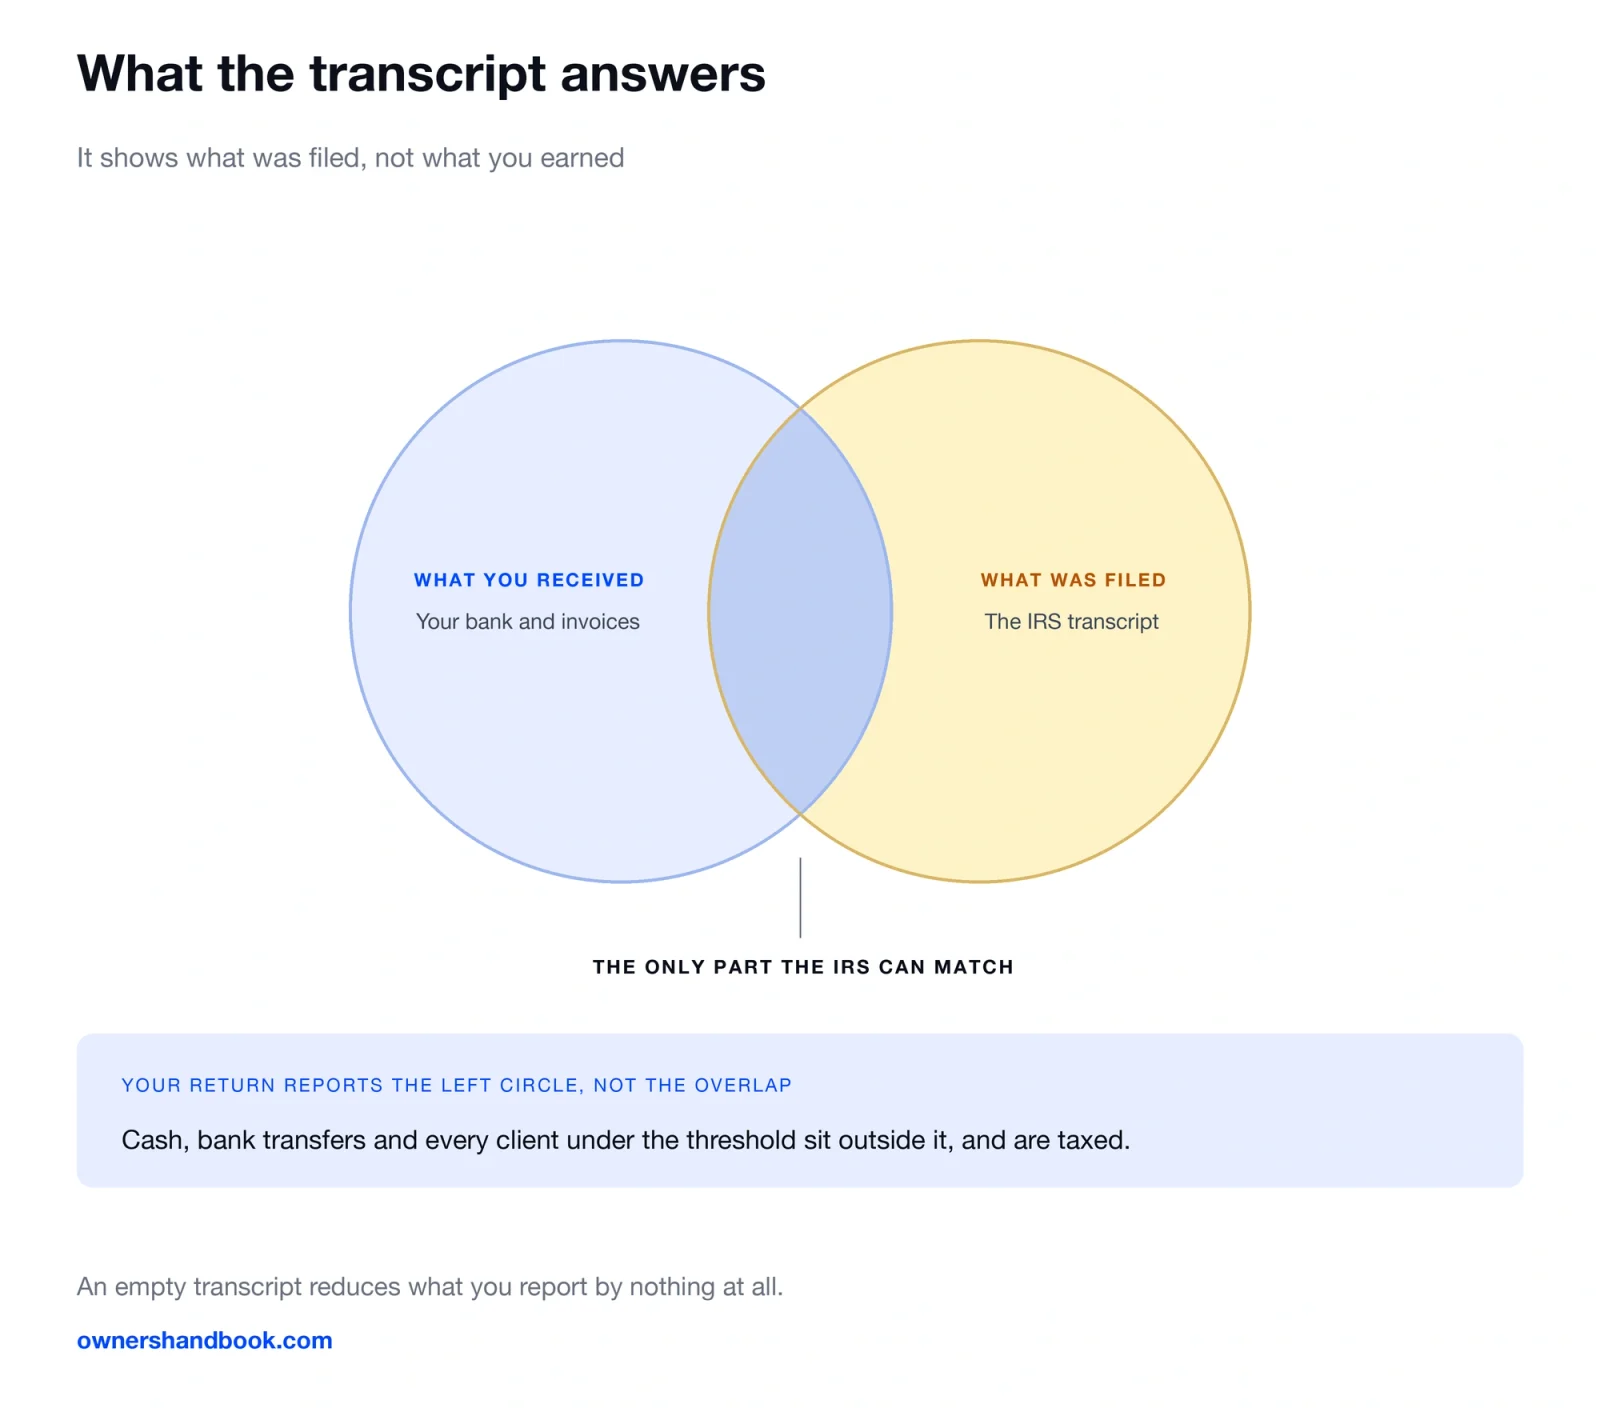
The transcript will only display information return documents that have been filed with the IRS which may not reflect all the information return documents issued to you.
Read it for what it is: a list of what the IRS will match your return against. If a client filed a 1099 you never received, it appears here and you now know the figure they used. If nothing appears, there is nothing to reconcile — which does not reduce what you report by a dollar.
When their number will differ from yours
If a form was filed and your copy went missing, you are in the mismatch case after all — just without the paperwork that would have warned you.
Most gaps have innocent explanations. A client reports by the date they paid. Publication 334 is explicit about the year-end version of this:
Receipt of a valid check by the end of the tax year is constructive receipt of income in that year, even if you can’t cash or deposit the check until the following year.
A cheque mailed December 28 and banked January 4 can legitimately sit in different years on the two sides. Reimbursed expenses can appear in the client’s total. A 1099-K reports gross, before fees and refunds.
The position you want is the same one you would want with a wrong form in hand: your actual income on the return, and the reconciliation ready. If the figures diverge enough to be noticed, what arrives is a CP2000, which the IRS describes as a mismatch notice rather than an audit:
The income or payment information we received from third parties, such as employers or financial institutions, doesn’t match what you reported on your tax return.
This notice isn’t a bill and your response may be required.
The full drill for answering one is in the companion guide linked at the top of this page. The short version: you tick disagree, attach the bank statements and the one-page reconciliation, and explain the difference in a paragraph.
When to contact the IRS, and what it can do
Almost every search for a missing form lands on IRS Topic 154. Read its scope before you follow it.
Topic 154 addresses Form W-2 and Form 1099-R. Its remedy — contact the payer, then call 800-829-1040 after the end of February, and the IRS sends you Form 4852 — produces a substitute for a W-2 or a 1099-R. That is what Form 4852 is. There is no equivalent substitute form for a 1099-NEC, and no IRS process that hands you a figure for one.
So the sequence that actually works has no IRS step in the middle:
Ask the client once, in writing, and keep the request. A late 1099 costs them far less than a missing one, so it is worth telling them so.
Pull the transcript to see whether a form exists.
File on your own records, on time.
The client’s failure is still a failure. Section 6722 penalises not furnishing a correct payee statement, and the amounts for 2027 run from $60 to $340 per statement, with the identical amount charged again on the IRS copy under section 6721. None of that is payable to you. It is the IRS’s leverage, not your remedy, and it is not a reason to delay your own return.
What you file, and the thresholds that are actually yours
The $2,000 figure is the client’s filing threshold. It is not a floor on your income.
Your own numbers are different. The Instructions for Schedule SE put the self-employment tax line at the bottom:
You must pay SE tax if you had net earnings of $400 or more as a self-employed person.
Four hundred dollars of net earnings, with no form anywhere in sight, is a filing obligation. Our guide to the filing threshold covers how that interacts with the standard deduction, and self-employment tax covers the rate once you are over the line.
File on time with the right number. A missing form is not a reason for an extension, and a late return carries its own penalty charged from the due date, unrelated to anything the client did or did not send. If the missing income also means your estimated payments were short, quarterly estimated taxes covers catching up.
What not to do
Do not leave the income off. This is the only genuinely expensive mistake available here, and it is the one the absence of a form invites.
Do not wait. No 1099 arrives in April. A client who missed January 31 has usually stopped thinking about it.
Do not file Form 4852. It substitutes for a W-2 or a 1099-R. It is not a substitute 1099-NEC, and filing one here answers a question nobody asked.
Do not guess at a round number. Reconstruct from deposits. A figure you can show beats a figure you can defend.
Do not report less than your records show out of worry that a mismatch looks worse. The mismatch that generates a notice is reporting *less* than the forms on file, not more.
Do not demand a form the client does not owe you. Check the amount and the payment method first. Asking a client who paid you through Stripe to issue a 1099-NEC asks them to file something the instructions forbid.
Frequently asked questions
A client paid me $12,000 by bank transfer and never sent a 1099. Is that illegal?
They had an obligation and missed it, and the penalty is theirs under sections 6721 and 6722. It changes nothing about your return — the $12,000 goes in gross receipts because you received it.
Can I ask them to file it late?
Yes, and it is a fair thing to tell them: filing within 30 days of the due date costs a fraction of never filing. The payer-side repair for a form already sent with the wrong figures is correcting a 1099 you issued.
Nothing shows on my transcript. Do I still have to report it?
Yes. The transcript shows what was filed about you, not what you earned. The Publication 334 rule covers income “not reported to you on a Form 1099 filed by the payor.”
Every client paid me under $2,000, so no forms at all. Am I below the filing threshold?
No. Those are two different thresholds. The $2,000 governs whether a client must file a form. Your own trigger is $400 of net earnings for self-employment tax.
I was paid through Upwork and got no 1099-K either. Why not?
The 1099-K threshold is far higher than the 1099-NEC one and most freelancers never reach it. Taxes by platform covers what each marketplace does and does not report.
I need proof of income and the 1099 was going to be it. Now what?
Invoices, bank statements and a filed Schedule C do the same job, and usually better. Our guide to proving your income covers what lenders and landlords actually accept.
Sources
IRS, Publication 334, Tax Guide for Small Business
https://www.irs.gov/pub/irs-pdf/p334.pdf
IRS, Gig Economy Tax Center
https://www.irs.gov/businesses/gig-economy-tax-center
IRS, Publication 583, Starting a Business and Keeping Records
https://www.irs.gov/pub/irs-pdf/p583.pdf
IRS, Transcript types and ways to order them
https://www.irs.gov/individuals/transcript-types-and-ways-to-order-them
IRS, Topic no. 154, Form W-2 and Form 1099-R, what to do if incorrect or not received
https://www.irs.gov/taxtopics/tc154
IRS, Instructions for Forms 1099-MISC and 1099-NEC (Rev. December 2026)
https://www.irs.gov/pub/irs-pdf/i1099mec.pdf
IRS, Instructions for Schedule SE (Form 1040)
https://www.irs.gov/pub/irs-pdf/i1040sse.pdf
IRS, Understanding your CP2000 series notice
https://www.irs.gov/individuals/understanding-your-cp2000-series-notice