How to Prove Freelance Income to a Landlord
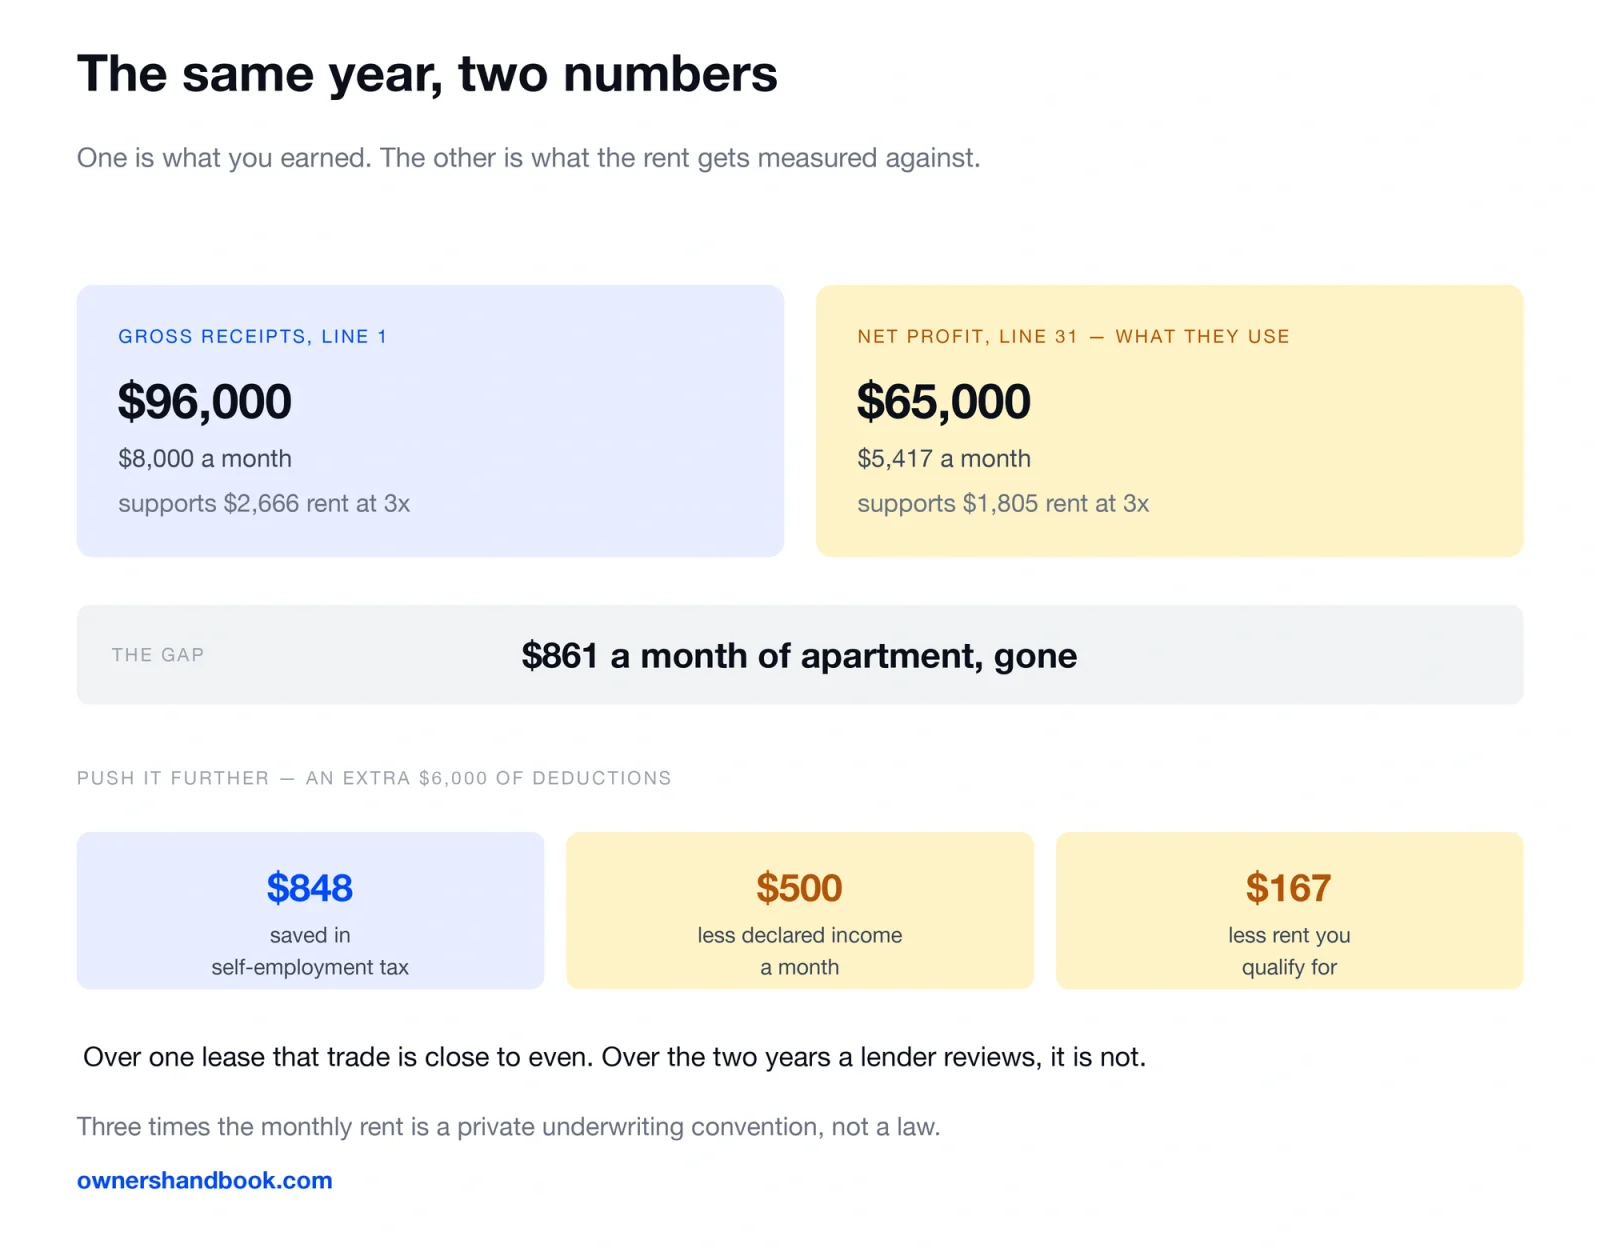
The number a landlord ends up judging you on is line 31 of your Schedule C — net profit — not the money your clients actually sent you. On a $96,000 year with $31,000 of deductions, the figure that gets measured against the rent is $65,000. Everything else about proving freelance income follows from that one fact, and almost nothing written for renters mentions it.
Here is what actually carries weight, in what order, and why the paperwork that feels most official is often the weakest.
What each document really proves
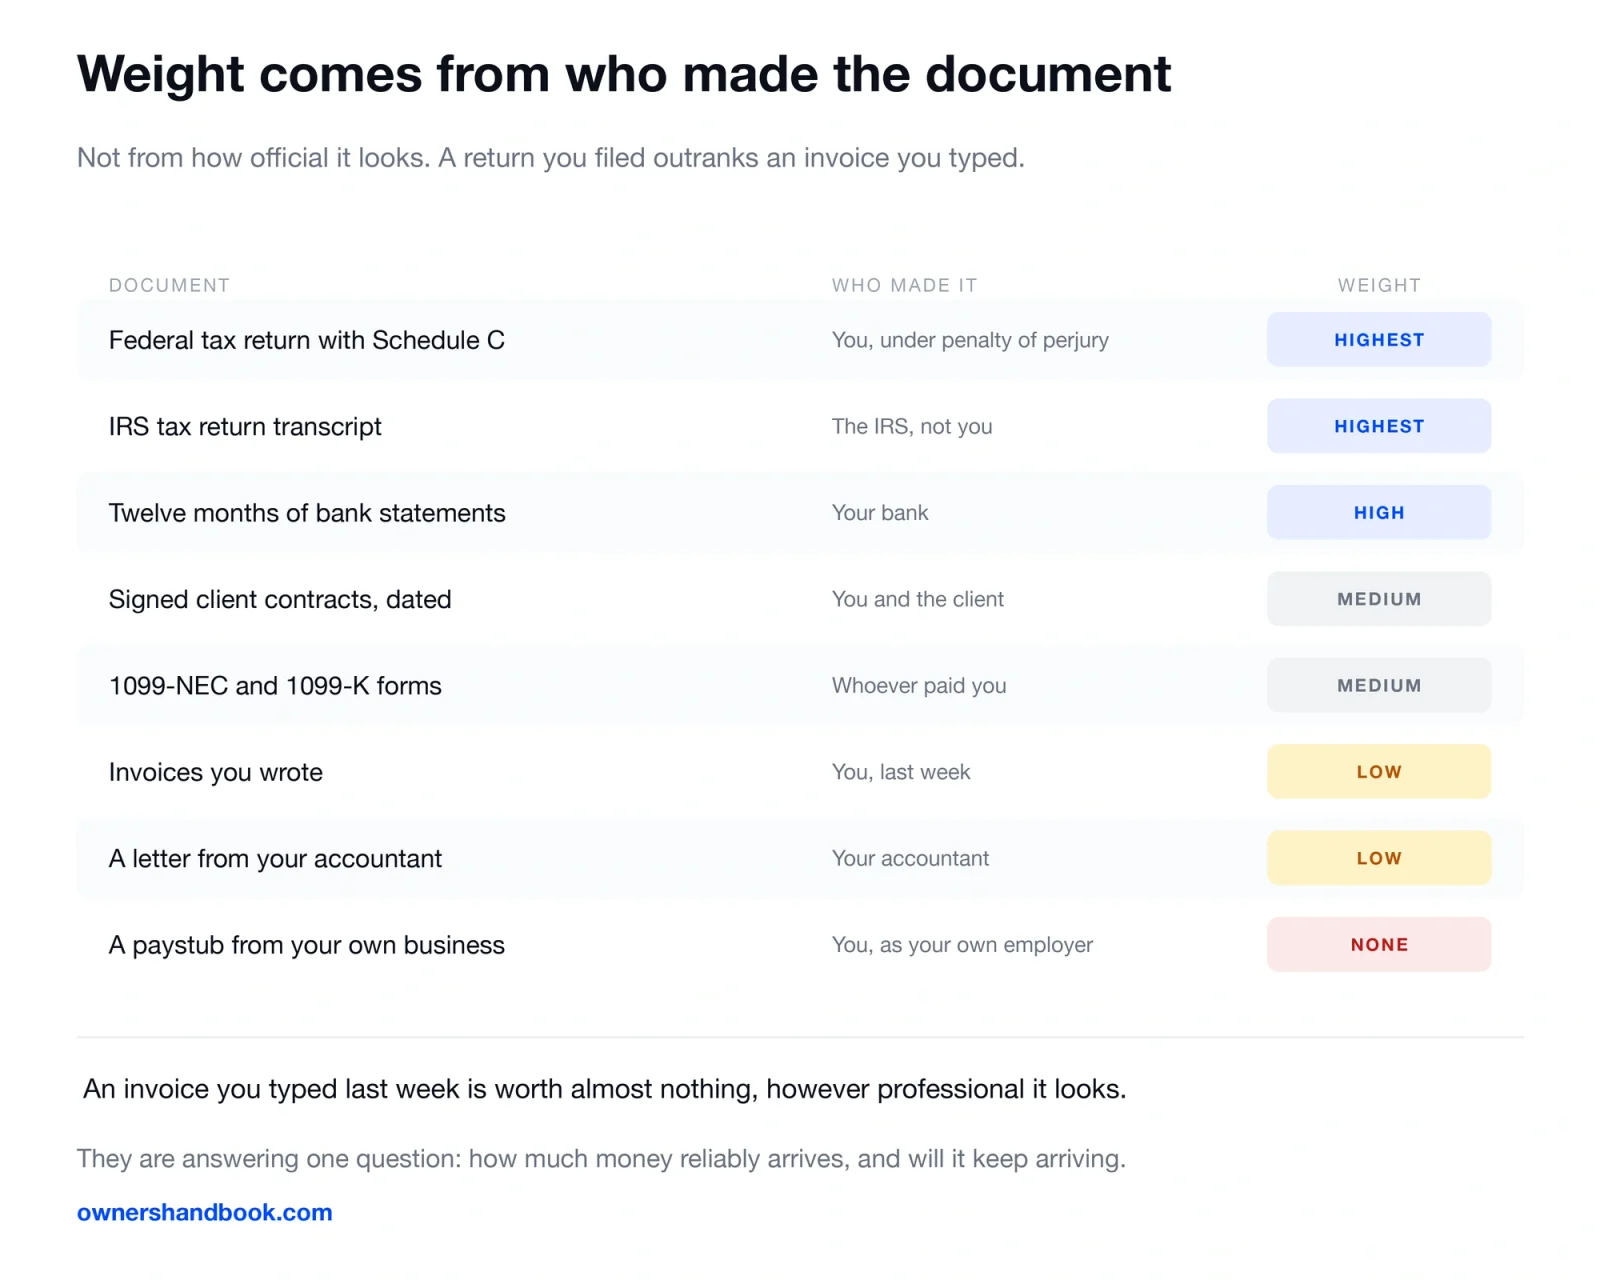
Landlords and lenders are answering one question: how much money reliably arrives, and will it keep arriving.
| Document | What it proves | Weight |
|---|---|---|
| Federal tax return with Schedule C | Net profit, declared under penalty of perjury | Highest |
| IRS tax return transcript | The same figures, confirmed by the IRS rather than by you | Highest |
| Twelve months of bank statements | Money that actually landed | High |
| Signed client contracts with dates and rates | Income likely to continue | Medium |
| 1099-NEC and 1099-K forms | Part of your income, reported by someone else | Medium |
| Invoices you wrote | What you billed, which is not what you were paid | Low |
| A letter from your accountant | That an accountant prepared your return | Low |
| A paystub from your own business | Nothing, unless you genuinely run payroll | None |
The pattern is simple. Documents get weight from being made by someone other than you. A return you filed is strong because lying on it is a federal offence; a transcript is stronger because the IRS hands it over. An invoice you typed last week is worth almost nothing, however professional it looks.
Why your deductions work against you here
Most leasing offices apply a multiple of monthly income to the rent. Three times the monthly rent is the usual convention — a private underwriting rule, not a law, and it varies by landlord. What does not vary is which income figure goes into it. They use net profit, because that is the number on your tax return.
| Figure | Annual | Monthly | Rent it supports at 3x |
|---|---|---|---|
| Gross receipts, Schedule C line 1 | $96,000 | $8,000 | $2,666 |
| Net profit, Schedule C line 31 | $65,000 | $5,417 | $1,805 |
That is $861 a month of apartment, gone, on the difference between what you earned and what you declared as profit.
Push it further. An extra $6,000 of deductions you are fully entitled to take saves about $848 in self-employment tax, which runs at 15.3% on 92.35% of net earnings, plus income tax on top. In exchange your declared monthly income falls by $500 and the rent you qualify for falls by about $167. Over one lease that trade is close to even; over the two years a mortgage underwriter reviews, it is not. Our guide to freelance tax deductions covers what you can claim, and lowering your freelance tax legally is worth reading with this timing in mind.
The tax transcript, and why it beats a PDF of your return
Anyone can edit a PDF. That is why a transcript exists, and it is the most useful document in this process. A tax return transcript, in the IRS’s words:
shows most line items from your original Form 1040-series tax return as filed, along with any forms and schedules.
And the line that makes it worth asking for:
A tax return transcript usually meets the needs of lending institutions offering mortgages.
It is free, covers the current and three prior tax years, and downloads in minutes from your IRS online account. By post it takes 5 to 10 calendar days and goes to the address the IRS has on file, which is worth checking first.
Two other types help occasionally. The wage and income transcript “shows data from information returns we receive such as Forms W-2, 1098, 1099, and 5498” and goes back nine years, which recovers a lost 1099. The verification of non-filing letter “states that the IRS has no record of a processed Form 1040-series tax return as of the date of the request” — what a first-year freelancer needs to explain the gap. Mortgage lenders often bypass you entirely with Form 4506-C, the “IVES Request for Transcript of Tax Return”.
Bank statements, and the one thing that ruins them
Twelve months of statements showing client deposits is the second-strongest document you have, and it corroborates the return rather than competing with it. It only works if the account is clean. If freelance income lands in the same account as your rent, your partner’s transfers and Venmo reimbursements, nobody can pick the income out and the reviewer falls back on the return. A separate business account fixes that; our guide to tax record keeping covers setting one up, and receipt rules for freelancers covers the expense side.
Export the bank’s own PDFs, header intact, every page. Screenshots of a banking app are treated, correctly, as unverifiable.
Your 1099s prove less than they used to
There is a recent change here that has not filtered through to anyone writing about renting. The reporting threshold for Form 1099-NEC has risen: a payer now files one only if they paid you at least $2,000 during the year.
For tax years beginning after 2025, the minimum threshold amount for reporting certain payments required to be reported on certain information returns and/or perform backup withholding on those payments increased to $2,000 and may be adjusted for inflation beginning in calendar year 2027.
The old figure was $600, and it had stood since 1954. If your work is spread across many small clients you will now receive noticeably fewer 1099s than the same income produced last year, and a landlord treating them as a proxy for income will undercount you.
Two further limits. A 1099-K reports gross, before platform fees, refunds and chargebacks, so it overstates what reached you — our comparison of 1099-NEC and 1099-K explains why. And plenty of legitimate income produces no form at all: foreign clients, individuals, anyone below the threshold. The Form W-9 you sign for a new client only produces a 1099 if that client pays you enough. Absence of a form is not absence of income, which is why the return outranks the forms.
What a letter from your accountant can and cannot say
People ask their accountant for a letter confirming their income and are surprised to be refused. The refusal is standard. Guidance issued through the AICPA’s professional liability programme lists the requests accountants should decline, and it is exactly the list you were about to make: “Confirmation of a client’s self-employment status,” “Verification of income from self-employment,” “Verification of a self-employed borrower’s business ownership percentage,” and “Profitability or sustainability of a self-employed client’s business.” The reasons are liability and client confidentiality — if the loan later fails, the lender can argue it relied on the letter.
What you can get is a letter confirming the firm “prepared the 20XX federal individual income tax return” for you, usually carrying a disclaimer that “This information was neither audited nor verified by me, and I make no representation nor provide any assurance regarding the accuracy and completeness of this information.”
That confirms a real accountant and a real filed return. It is not income verification.
Do not buy a paystub
Search results for proving freelance income are full of paystub generators. Using one is the worst decision available.
A paystub records wages paid to an employee by an employer who withheld payroll taxes. You are not an employee of your own sole proprietorship — you take draws, not wages — so a paystub describing you as one describes something that did not happen, and anyone who checks finds no employer and no withholding.
On a mortgage or credit application the exposure is not merely embarrassment. Knowingly making a false statement to influence a wide range of lenders and mortgage businesses carries a federal penalty of being:
fined not more than $1,000,000 or imprisoned not more than 30 years, or both.
For a rental application the criminal exposure is a matter of state fraud law rather than that statute, but the outcome is the same: denial, and a lease obtained with a false document can be terminated for misrepresentation after you move in.
When the documents are genuinely thin
First year freelancing, or a return that no longer reflects where you are.
| Offer | Why it works |
|---|---|
| A larger deposit, within your state’s legal cap | Converts a risk question into a money question |
| Several months of rent prepaid | Same, more directly |
| A guarantor or co-signer | Substitutes someone else’s verifiable income |
| Signed contracts running past the lease term | Evidence the income continues |
| Recent bank statements plus a short income summary | Shows current reality when the return is stale |
Write the summary yourself: one page listing each client, what they pay, how often, and since when, with bank statements attached. As an index to documents that are proof, it is persuasive. Our freelance invoice template will at least make an inconsistent stack of invoices look like a business.
If you are the landlord, ask for these
Nobody writes this side, and it has the harder problem: verifying a self-employed applicant without either taking their word for it or excluding a large slice of the workforce.
| Ask for | Because |
|---|---|
| The last two federal returns, all schedules included | Two years shows a trend; one year shows a moment |
| A tax return transcript, or Form 4506-C | The IRS supplies it, so it cannot have been edited |
| Three months of complete bank statements, every page | Deposits should corroborate the return |
| Schedule C line 31, not line 1 | Net profit is the money available for rent |
Two calibrations. Mortgage underwriting asks for two years because one good year proves little — Fannie Mae requires lenders to obtain “a two-year history of the borrower’s prior earnings as a means of demonstrating the likelihood that the income will continue to be received.” A lease is a shorter commitment, so two years is reasonable but a harsh screen.
And self-employed income is lumpy. Someone earning $70,000 may bank $14,000 in March and $1,100 in August. Judging them on a single month, which is what a paystub-shaped process does, is wrong in both directions. Annual net profit divided by twelve is the honest comparison.
Frequently asked questions
What if my tax return shows a low net profit because of deductions?
Explain it rather than hide it. Bring bank statements showing gross deposits, and be ready to point out which deductions were one-off equipment purchases. Our explanation of Schedule C is worth reading before that conversation.
I have not filed a return yet. What can I show?
Bank statements, signed contracts, and a verification of non-filing letter from the IRS to account for the missing return. Expect to be asked for a larger deposit or a guarantor.
Can I use invoices as proof?
Only as support. An invoice shows what you billed, and nobody can tell from it that you were paid. Pair each with the matching bank deposit.
How far back should I be ready to go?
Two years of returns covers most rental and lending requests. Transcripts run to the current and three prior tax years.
Sources
IRS, Transcript types for individuals and ways to order them
https://www.irs.gov/individuals/transcript-types-for-individuals-and-ways-to-order-them
IRS, Get transcript
https://www.irs.gov/individuals/get-transcript
IRS, Schedule C (Form 1040), Profit or Loss From Business
https://www.irs.gov/pub/irs-pdf/f1040sc.pdf
IRS, Form 4506-C, IVES Request for Transcript of Tax Return
https://www.irs.gov/pub/irs-pdf/f4506c.pdf
IRS, Instructions for Forms 1099-MISC and 1099-NEC
https://www.irs.gov/instructions/i1099mec
IRS, Self-employment tax (Social Security and Medicare taxes)
Fannie Mae Selling Guide, B3-3.2-01, Underwriting Factors and Documentation for a Self-Employed Borrower
CNA and AICPA Professional Liability Insurance Program, Third-Party Verification Letters
https://www.cpai.com/Education-Resources/my-firm/Tax-Services/Third-Party-Verification-Letters
18 U.S.C. 1014, Loan and credit applications generally